How Quest Diagnostics' Financial Assistance Actually Works
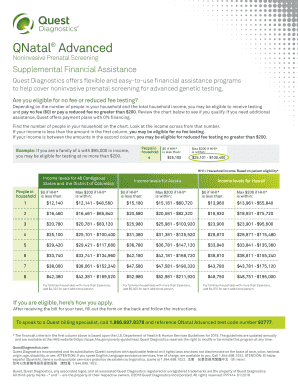
The financial assistance program at Quest Diagnostics is a patient discount program for people without insurance or with incomes under a certain threshold. It exists, but it doesn't come with a welcome banner or a prompt at checkout. You have to find it, request it, and fill out paperwork before or shortly after your test. Most people never do, and they get billed the full commercial rate for labs that could cost a fraction of that. Start at questdiagnostics.com/financial-assistance. There is an online application you can submit, or you can call their financial assistance line at 1-800-367-6780. The online form asks for your name, address, date of birth, proof of income for the most recent 90 days, and whether you have insurance. Upload a copy of your most recent tax return, pay stubs, or a letter from your employer. If you're self-employed, a simple profit-and-loss statement works. Approval typically comes back within five to ten business days. You will get an email confirmation with an eligibility number. This number ties to your patient record and applies to charges going forward, though you can also apply it to prior charges if they fall within the 90-day window from your test date. Call the number on your bill and reference the eligibility number. They will reprocess the account at the discounted rate and either cancel the balance or reduce it to zero depending on your income bracket.
Who Qualifies and What It Actually Covers
Eligibility runs on a sliding scale tied to the Federal Poverty Guidelines. Households at or below 200% of the FPL generally qualify for free tests. Between 200% and 400% of the FPL, you get discounted pricing. Above 400%, you are out of luck under this program. A family of four in 2024 hits the 400% mark at roughly $108,000 in annual income, but those numbers shift every year. Check the current table on the Quest site before you apply. The program covers lab tests ordered by a licensed provider. It does not cover things like employer-mandated drug screens, pre-employment physicals, or tests ordered as part of a legal proceeding. It also does not cover the physician's office visit fee, only the lab portion. If you go to an urgent care and get blood drawn there, the lab work through Quest may qualify but the facility fee won't.
Common Pitfalls That Cost People Money
The biggest mistake I see is people assuming the program applies automatically because they mentioned low income at check-in. It does not. Quest's front desk staff are not trained to screen for financial assistance. They will process your insurance, deny the claim if the lab is out of network, and send you a bill. Only the formal application triggers the discount. Bring it up before the blood draw if you can, but if you forget, apply within 90 days of the test date. Another issue involves dual coverage. If you have Medicaid and a secondary plan, Quest will bill both. The financial assistance program generally only applies when you have no insurance at all. Being enrolled in any plan, even a minimal one, can disqualify you. I had a patient once who was on a state waiver program that looked like insurance but wasn't recognized by Quest's system. She ended up getting denied for financial assistance because the application asked "do you have insurance" and she checked yes. The workaround was getting her state caseworker to confirm in writing that the waiver was not traditional insurance, then resubmitting the application with that letter attached. Took three weeks and two phone calls, but it went through.
Get the Full Details

The Uninsured Discount Option
If you do not qualify for full financial assistance, Quest does offer a prompt-pay discount for uninsured patients. It is not advertised anywhere. Ask for it at check-in. It usually knocks 30 to 50 percent off the charged rate on standard panels like CMPs and lipid profiles. You have to pay at the time of service, and you need to bring a valid ID and proof that you do not have insurance. This is not the same as the financial assistance program. It is a separate cash-price reduction, and it is easier to get approved on the spot. Financial assistance through Quest is not a payment plan. It is a discount or waiver applied after approval. If you already have a bill in collections, the program will not reach into collection agencies and reverse charges. You have to apply before the account goes to Collections, which usually happens around day 120. Once it leaves Quest's internal billing, you are dealing with a third party and the financial assistance approval may not transfer. It also does not cover tests done at Quest-affiliated physician offices. The program applies only to tests processed through Quest Diagnostics labs. If your doctor orders a test and sends it to a different lab network, Quest's program does not touch it. This sounds obvious but it trips people up constantly when they switch doctors and the new office sends labs to LabCorp instead.
Documentation You Should Gather Before Applying
Have the following ready before you start the application. It saves time and prevents partial submissions that get flagged for review: Recent pay stubs: the last three consecutive months, or the last one if you are self-employed. Tax return: the most recent filed return, page one plus the W-2 or 1099 summary page.
Proof of household size: a copy of your tax return shows this, but if you share income with someone not listed on the return, include a simple written statement explaining the arrangement. Test information: the CPT codes from your order, the date of service, and the name of the ordering provider. The application asks for this but you can fill it in later. Having it on hand speeds things up. The whole process from application to approval usually takes between five and ten business days. If it has been longer than two weeks and you have not heard back, call the financial assistance line. Reference your application number and ask for a status update. Do not resubmit the entire application. Duplicate submissions reset the review clock and add two to three extra days with no benefit.

One practical note about appeal: if your application gets denied and you believe it is wrong, you have the right to appeal. The denial letter will include instructions. Submit the appeal within 60 days of the denial date. Include the same documentation you submitted originally plus any additional proof that addresses the reason for denial. Most appeals are resolved within ten business days. The approval rate on appeal is reasonable if the initial denial was based on missing documentation rather than genuine ineligibility.
Bottom Line
The program exists and it can meaningfully reduce or eliminate your lab bill, but it requires proactive steps on your part. Find the application, submit complete documentation, and follow up if you hear nothing within two weeks. If you are uninsured and do not qualify, ask for the prompt-pay discount at check-in. These are small actions that most people skip, and skipping them is the difference between a zero balance and a bill you cannot pay.