What Actually Comes Up When You're Sitting Across From Someone Asking Questions Asked In Finance Interview
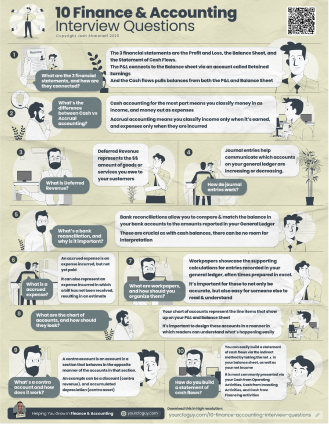
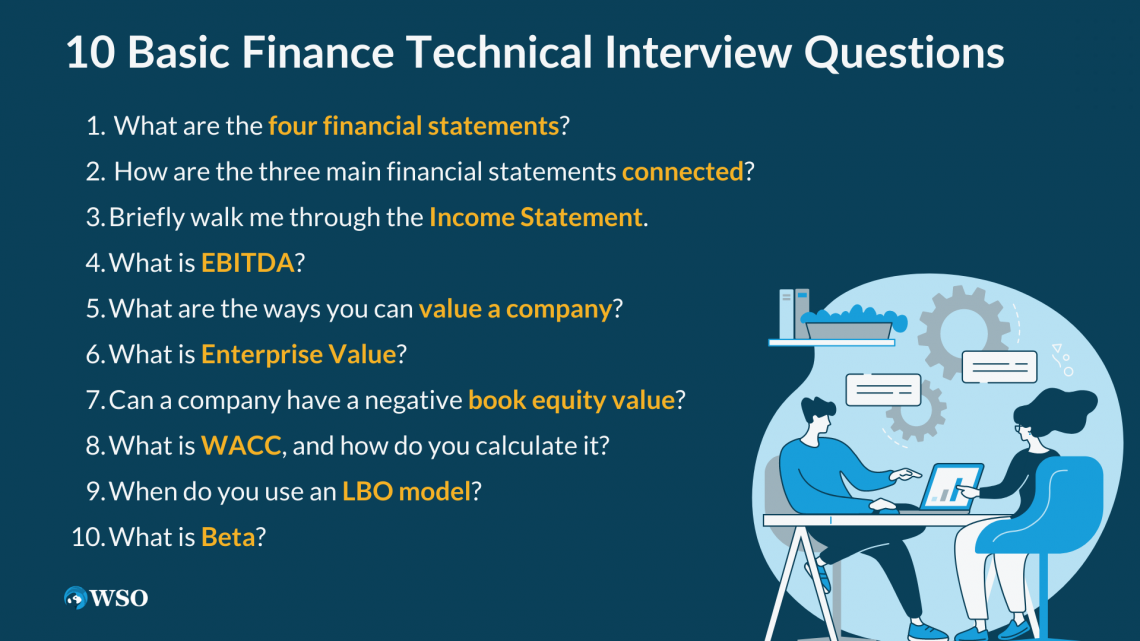
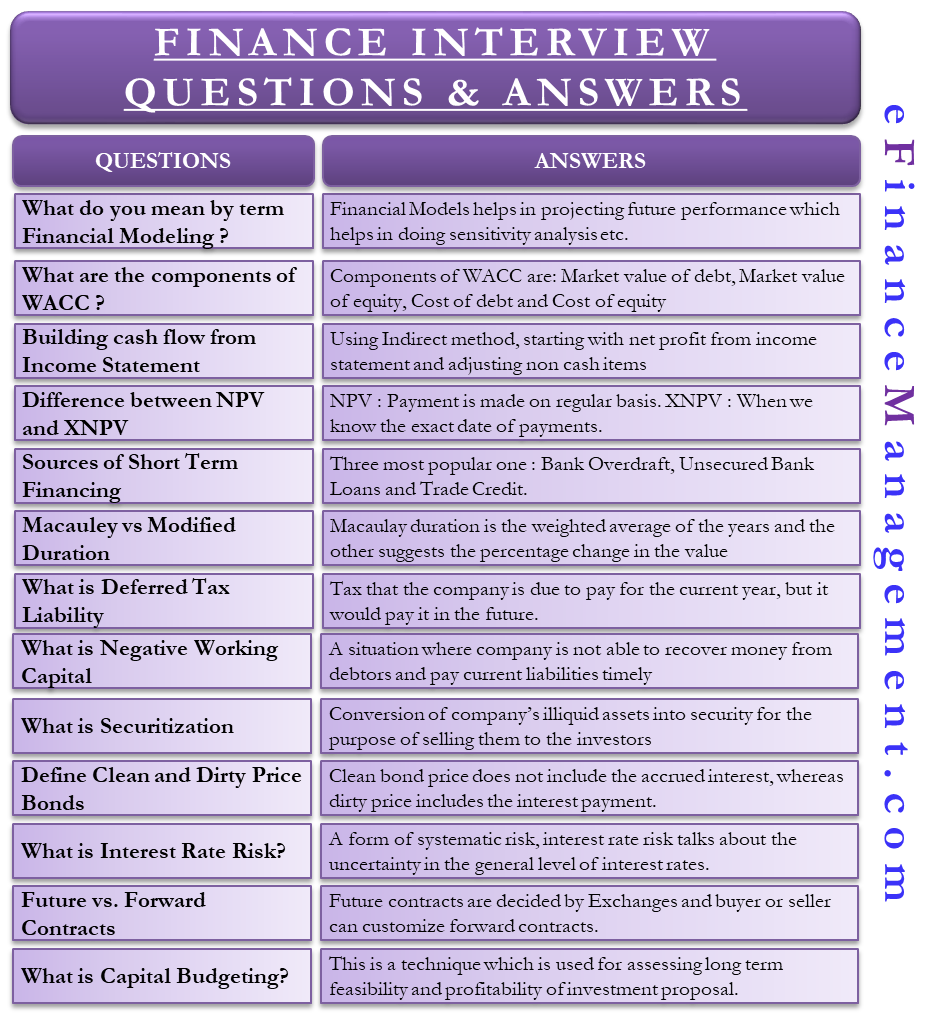
The finance interview isn't one thing. It depends entirely on which side of the desk you are on. Investment banking, corporate finance, equity research, and fintech all run completely different interview loops, and the questions reflect that. If you walk into an IB screen and start talking about discounted cash flow models like you're in a corporate FP&A round, you'll look like you didn't do basic homework. Most people prep the wrong questions because they don't realize how narrowly differentiated these tracks actually are. There are four buckets, roughly. Technicals, case studies, behavioral, and the weird ones that don't fit anywhere. I've sat on both sides of the table enough times to tell you what actually matters in each. The technical bucket is where most candidates fall apart, and not for the reason people think. They memorize formulas. That's almost useless. What they need to understand is the relationship between the components. Take a simple three-statement model. If depreciation goes up by $10 million, you can't just say "cash flow goes down." It flows through the income statement, the balance sheet, and the cash flow statement in a specific way. The right answer walks through each statement in order. Most candidates jump straight to the CFS line item and miss the tax shield effect on net income. I once watched a candidate who aced every valuation question bomb a straightforward working capital question because they couldn't explain why an increase in accounts receivable is a use of cash. They had memorized the formula but hadn't built anything from scratch themselves.
Case studies show up differently depending on the role. In investment banking, you might get a one-pager with a company's financials and be asked to value it under two methods. In corporate finance, it's more likely to be a capital allocation problem — should the company invest here or there, and what's the payback period? Equity research leans toward a stock pitch, and they want to hear a thesis, not just numbers. The common mistake across all of them is spending too long on setup and not enough on conclusions. Give me a 90-second summary before you dive into the ten assumptions. Behavioral questions in finance are surprisingly narrow. "Tell me about yourself," "Why this firm," "Walk me through your resume." The reason they ask these isn't curiosity. It's a filter for communication ability under mild pressure. Can you structure a thought without rambling for three minutes? I've seen people spend eight minutes on "why investment banking" and still not mention anything about the actual day-to-day work. That's a red flag, not because they lack passion, but because it signals they haven't thought about what the job actually entails. Then there are the edge cases. The kind of questions that don't have a textbook answer and catch people off guard. Here's a real one that came up in my round: a candidate was given a simplified cap table and asked to explain what happens to ownership percentages when a Series B at a higher valuation closes after a previous convertible note round. Most people could do the math on paper. Few could explain it cleanly out loud in under a minute. The workaround I found useful was to practice these with a whiteboard or scrap paper, not in your head. Verbal clarity under distraction is what they're actually testing.
How to Prep Without Wasting Three Weeks on the Wrong Stuff
Start with the role. The preparation for a credit analyst at a regional bank is fundamentally different from the preparation for a buy-side equity research associate. Map out which questions belong to which track before you open a single flashcard deck. For technicals, building a model from scratch is worth more than reading about one. I'd estimate that actually constructing a three-statement model in Excel takes you about four to six hours if you're doing it properly, but it teaches you more than any interview guide combined. You learn how the statements connect, where the circular references hide, and why a model that looks clean on the surface breaks as soon as you change one assumption. When I was prepping for my own interviews back when this was still the standard path, I built a DCF for a company I actually followed — not a practice template from a prep service. The specificity forced me to engage with real data, and that showed in the room. Interviewers can tell the difference between someone who has seen a model and someone who has built one. For valuation questions specifically, know when each method applies and when it doesn't. DCF is sensitive to terminal value assumptions to an uncomfortable degree. A 2% shift in your terminal growth rate can swing your valuation by 15 to 20 percent. LROIC multiples are cleaner but depend entirely on finding truly comparable companies. The pitfall most candidates hit is treating enterprise value and equity value as interchangeable. They're not. Enterprise value includes debt and excludes cash. If a company has $2 billion in debt and $500 million in cash, the equity value is significantly lower than the enterprise value, and missing that distinction in an interview will cost you more points than you'd expect.
Get the Full Details
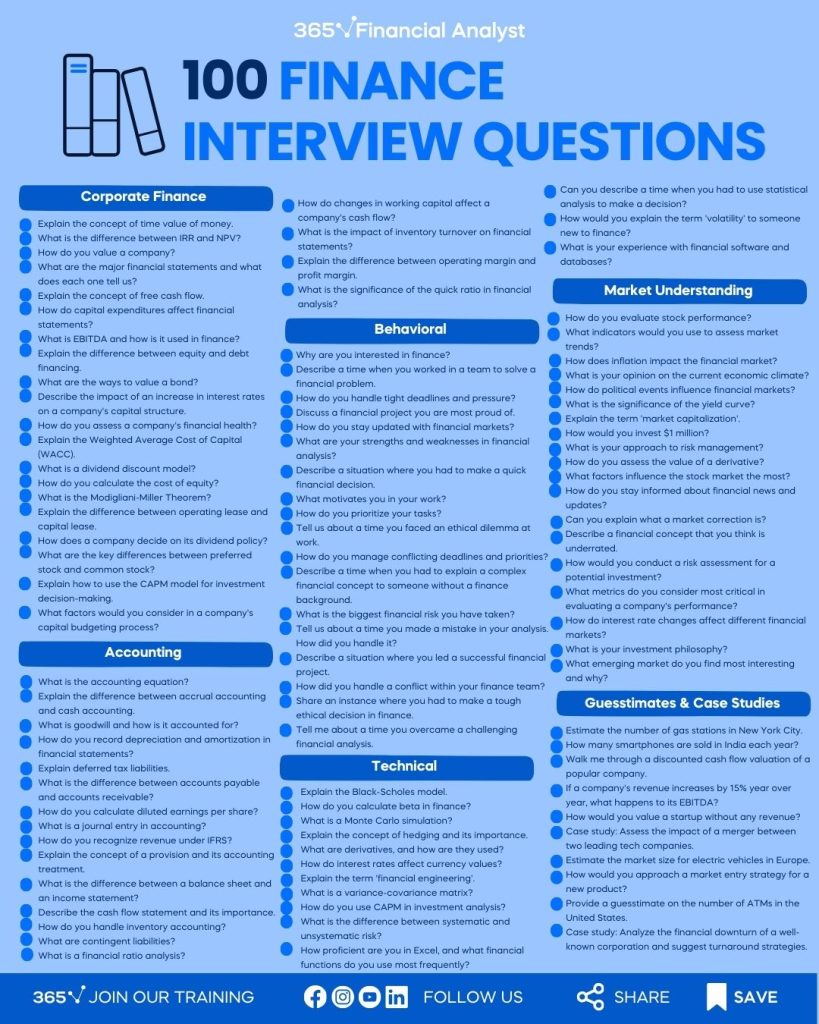
Case study prep should focus on speed, not perfection. In a real interview, you'll have maybe twenty minutes for a full case. Practice under time pressure. Set a timer. If you're not able to reach a defensible conclusion within that window, you're going to struggle in the actual room. I recommend using public company annual reports — grab a 10-K, pull the last three years of income statements and balance sheets, and walk through a quick valuation on your own. It's free, it's real data, and it builds muscle memory faster than any pre-packaged case. Behavioral prep is the most underrated part. Write down five stories from your experience that can answer at least three different behavioral questions each. A project failure, a time you disagreed with a teammate, a moment you had to explain something complex to a non-expert. Structure them using a simple framework: situation, action, result. Keep each story under two minutes when spoken aloud. Record yourself. You'll immediately notice where you drift.
When Standard Prep Doesn't Work
There are scenarios where the typical preparation strategy breaks down. If you're pivoting from a non-finance background — engineering, consulting, operations — your technical gaps will be more visible, and generic prep won't close them. I worked with someone who came from a data science background and could handle any quantitative question but kept freezing on accounting mechanics. He could build a Monte Carlo simulation in his sleep but couldn't explain why goodwill isn't amortized under current US GAAP. The fix wasn't more practice problems. It was going back to the source material — the actual accounting standards and understanding the logic behind the rules, not just memorizing them. Another limitation of most interview prep resources is that they over-index on investment banking questions and ignore the growing number of fintech and quantitative finance roles. If you're targeting a role at a payment processor, a neobank, or a quantitative hedge fund, the technical questions will involve probability, statistics, and sometimes basic coding. A standard finance interview guide won't cover that. You'd be better off working through probability puzzles and reviewing basic Python or SQL unless the role specifically calls for it. These questions test analytical thinking, not accounting knowledge, and treating them like finance questions is a waste of your prep time. The biggest blind spot in interview preparation, honestly, is not practicing the questions you're already good at. Everyone drills DCFs and LBOs until they can do them in their sleep. But the questions that actually separate candidates are often the simpler ones asked under time pressure — walk me through a recent transaction, what's the difference between EBITDA and operating cash flow, explain a concept you don't know the answer to. Those are the moments where composure matters more than content. I've seen candidates who knew less overall but handled uncertainty better land offers over people who had memorized every formula but panicked when asked something unexpected.
The whole process of preparing for Questions Asked In Finance Interview is less about accumulating knowledge and more about building the ability to retrieve and communicate it clearly under mild stress. That's the part nobody really talks about. The knowledge is the easy part. The retrieval under pressure is what actually determines the outcome.