The Real Quick Accounting Checklist Most People Ignore
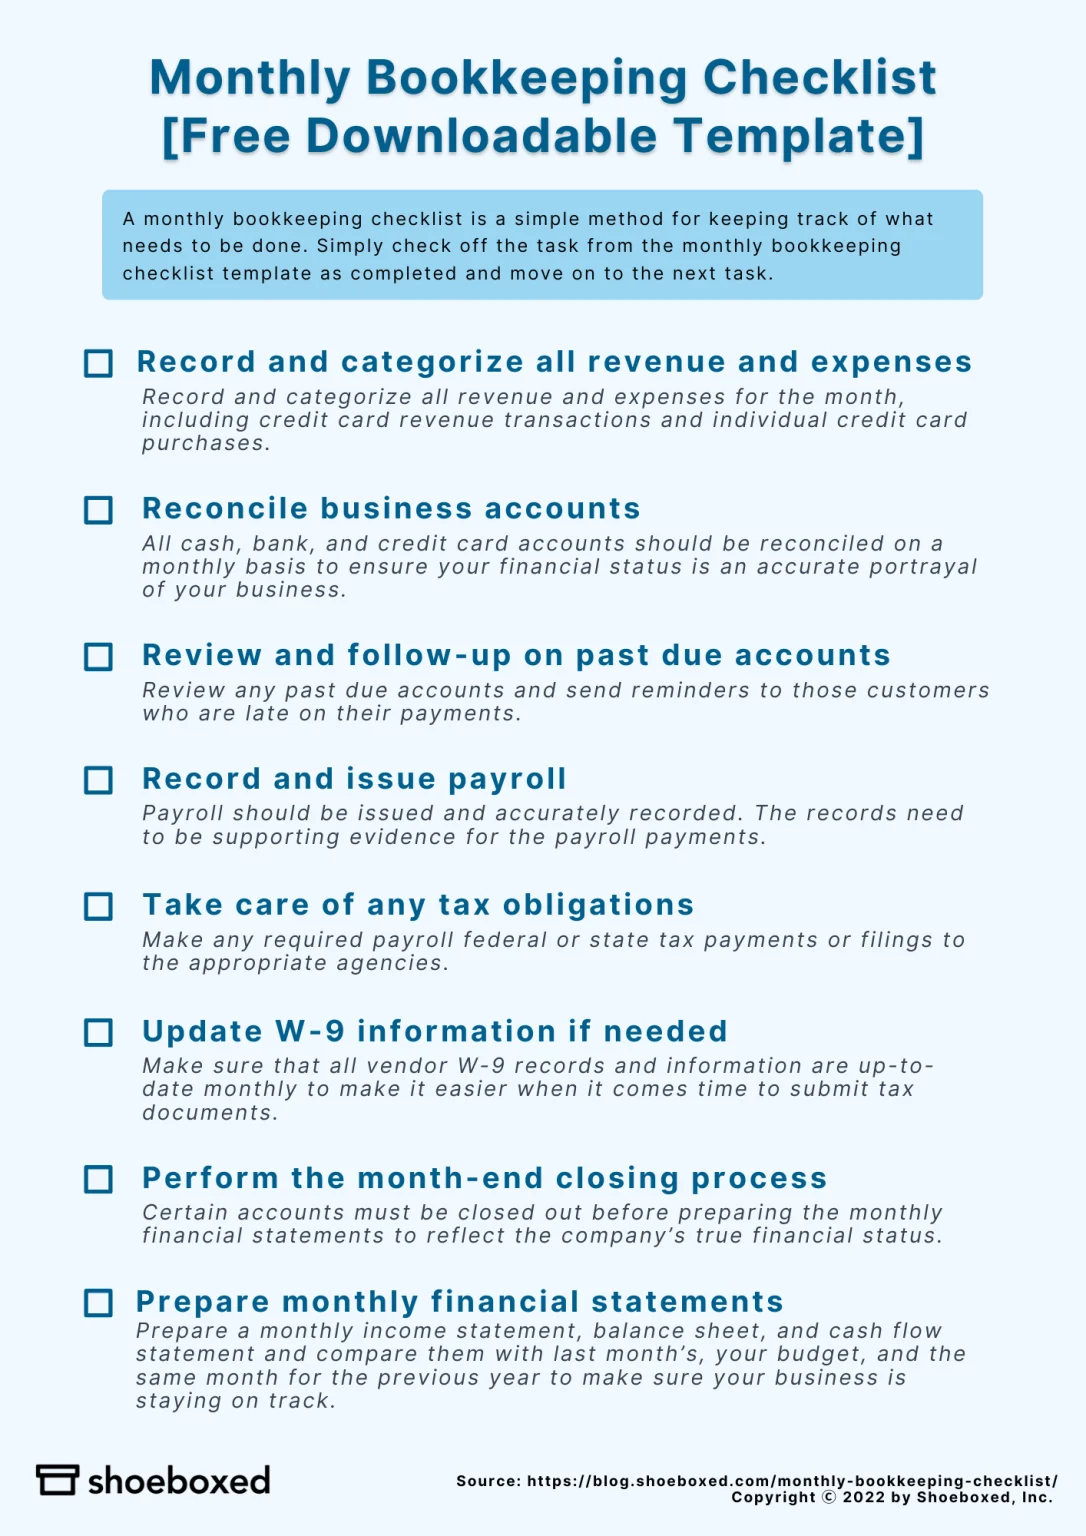
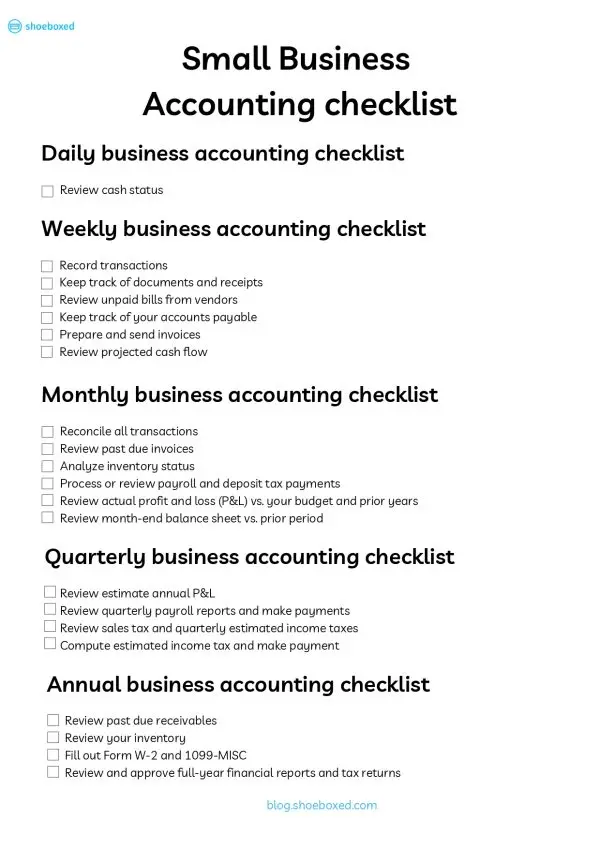
Accounting close is supposed to be mechanical. Run through the steps, verify the numbers, be done. In practice it is rarely that clean. I have been running monthly closes for small businesses for a while now, and the ones that hold up are the ones built around a quick accounting checklist that actually matches how the work gets done, not how textbooks describe it. Here is what yours should look like. I lay this out in the order that actually saves time, which is sometimes backward from how people think about it. 1. Lock the period before you start reviewing anything. This sounds backwards but it matters. If your team can still post entries while you are trying to reconcile, you will lose hours going in circles. Set the books to read-only mode for the period, then work. One client of mine had a bookkeeper who routinely backdated adjusting entries three weeks into the next month because she "found receipts after the fact." That single habit blew out our close timelines every single month until we forced the lock from the software side.
2. Bank and credit card reconciliations first. Not last. Not at the end when you are exhausted. These take the longest when they are messy, so do them while your brain is fresh. Match the general ledger balances against actual bank statements line by line. Any discrepancy over $50 needs a ticket, not a shrug. The threshold depends on your transaction volume but $50 is a sane floor for anything above sole proprietorship level. 3. Run the trial balance and compare it to last month. Don't just look at the totals. Pull the prior month trial balance side by side. Highlight anything that moved more than 10 percent or more than a thousand dollars, whichever is smaller for your operation. A 40 percent jump in office supplies is worth checking. A ten percent jump in accounts receivable from a single large invoice is usually fine and not worth chasing. 4. Verify accruals and deferrals. This is where most small business closes go soft. If you received a service in December but the invoice hasn't arrived, you still record the expense in December. Same logic on revenue you billed but haven't collected yet. I once caught a client who was deferring all vendor invoices until they hit the bank instead of when the service was received. They were consistently understating expenses by roughly fourteen percent during peak months. That compounded into material misstatements that showed up during a lender audit. Took six months to untangle.
5. Review fixed asset depreciation schedules. Pull the schedule. Verify additions this month. Verify disposals. Make sure the depreciation expense matches what the system calculated. A common mistake I see is people adding assets above the capitalization threshold without updating the schedule, which means depreciation gets skipped entirely for quarters at a time. Set a policy threshold, probably a thousand dollars, and stick to it. Write it down somewhere visible. 6. Check intercompany and clearing accounts. If you move money between your own accounts or between entity and entity, those clearing accounts should hit zero every month. If they do not, you have a ghost entry hiding in there somewhere. I found a recurring five hundred dollar discrepancy in an intercompany transfer account that had been sitting unresolved for eleven months. Turns out a single payment was recorded against the wrong entity code. Easy to miss if you only glance at the total. 7. Run management reports. Profit and loss, balance sheet, cash flow. Not because investors care right now but because you need to see the shape of the month. If gross margin shifted five points without a clear reason, investigate before you move to the next month. Small drifts compound into structural problems.
Get the Full Details
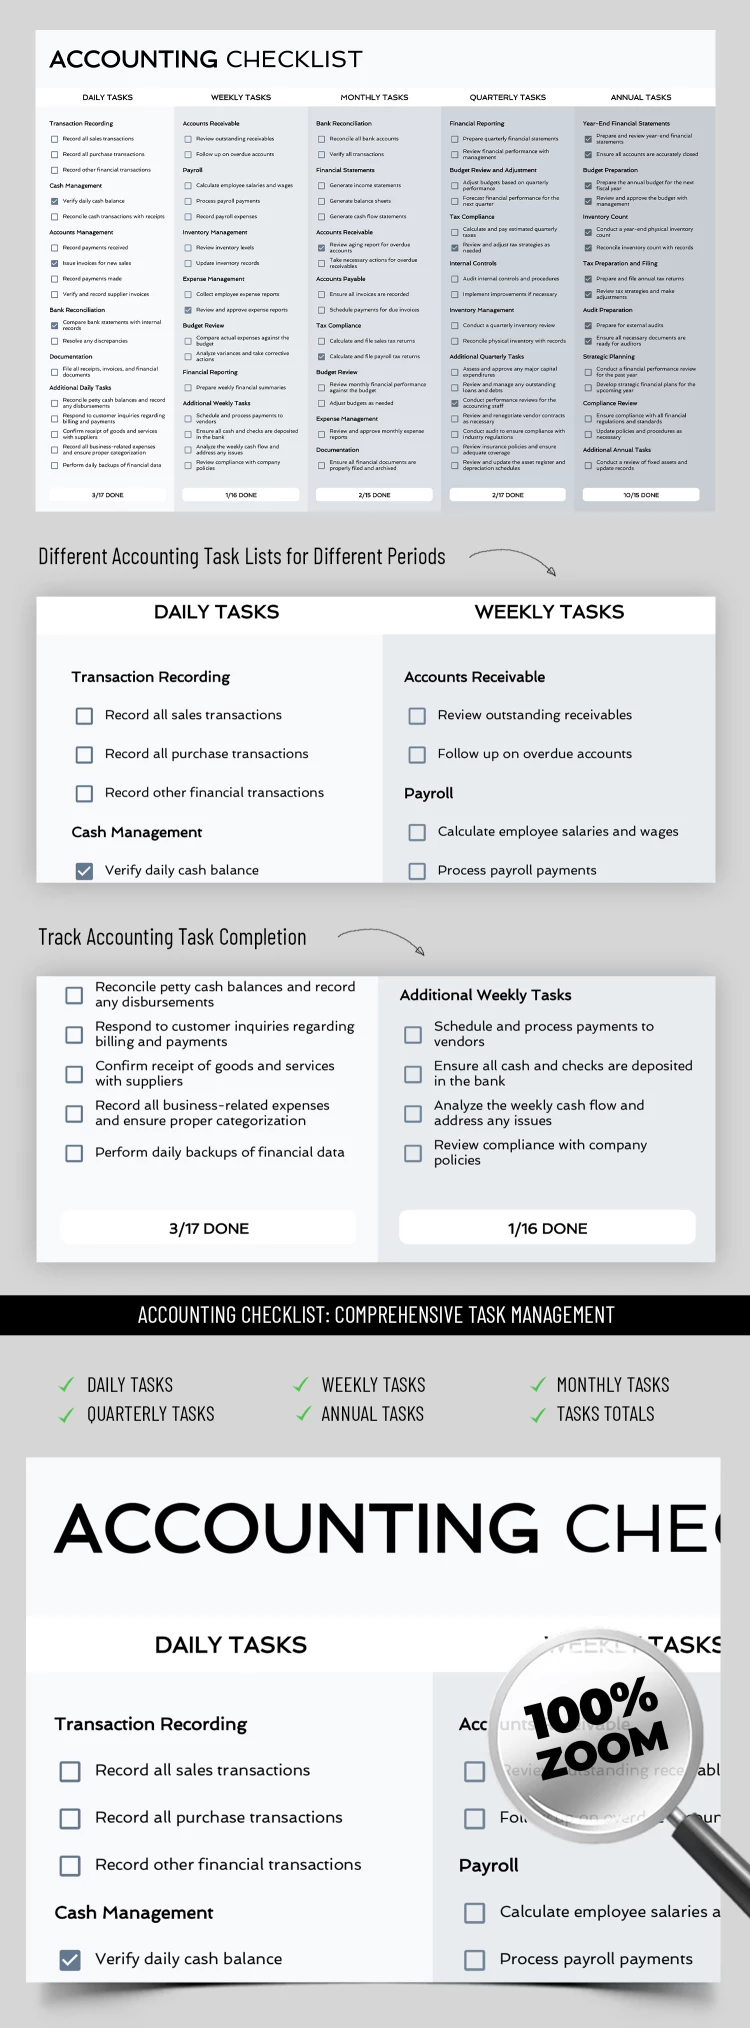
8. Document everything you did. Keep a brief log. Date, action taken, findings, any exceptions noted. This is the part everyone skips and then regrets when the IRS or a banker asks questions six months later. You do not need fancy documentation. Three sentences per entry is enough. The goal is that next month you or whoever takes over can see exactly what happened without reconstructing the entire process from memory. The whole thing should take between two and four hours for a typical small business with under five hundred transactions per month. Anything longer and you are either dealing with messy books or you have workflow inefficiencies. Six hours means something is broken in the process, not just in the numbers. One thing the checklist won't fix is bad data entry hygiene. If your team is coding expenses to the wrong accounts or missing invoices entirely, no amount of checklist discipline will make the close clean. I would rather spend time training people to enter things correctly the first time than spending extra hours each month catching mistakes. The checklist is a net, not a foundation.
Another limitation worth noting: this approach assumes you are using decent accounting software. If you are still doing this in spreadsheets, the timeline doubles and the error rate skyrockets. QuickBooks, Xero, FreshBooks, or something similar is the minimum viable setup. Anything less and you are solving problems that automated tools would not create. If you want to print this out and tape it to your monitor, go ahead. The real value is in doing it consistently for twelve months straight so you learn what your numbers look like when they are right. Then when something is wrong, you will notice immediately instead of discovering it during tax season.