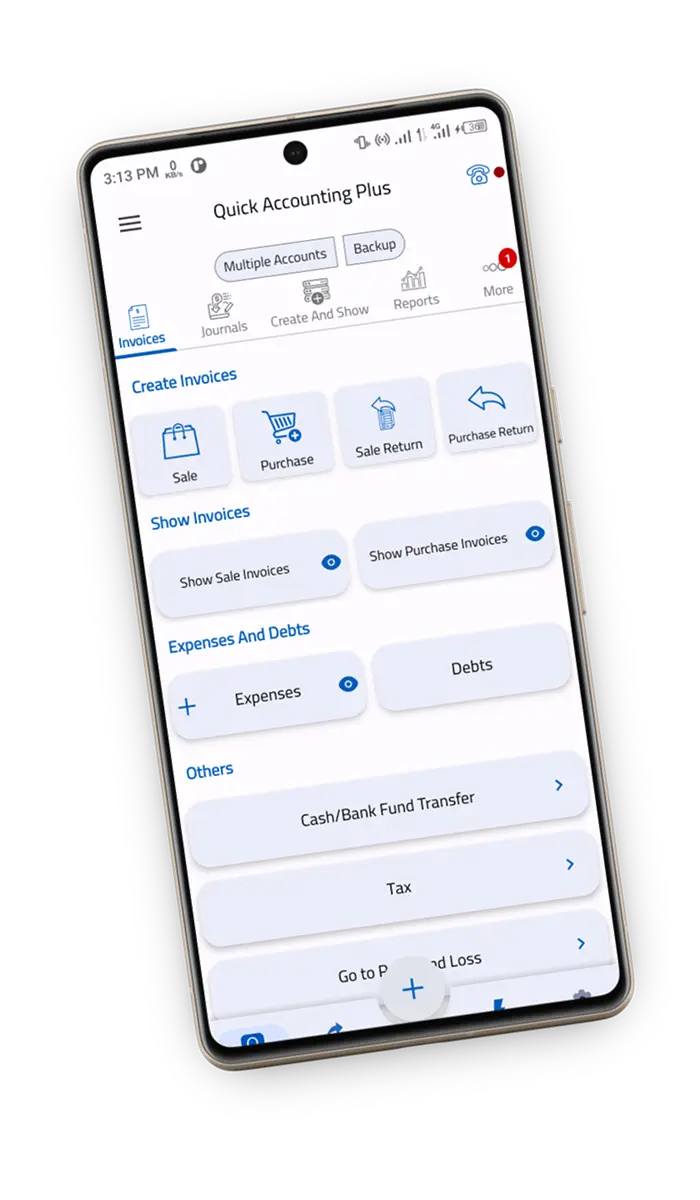
What Quick Accounting Gameplay Actually Is
Quick Accounting Gameplay is basically a streamlined approach to tracking finances using simplified, often automated workflows. The whole idea behind it is that you don't need a full enterprise ERP system to manage daily bookkeeping. You need something that gets you from transaction to report quickly, without getting bogged down in chart-of-accounts complexity or multi-step reconciliation processes. People use this for small businesses, side hustles, and even personal finance tracking. It typically involves a lightweight accounting tool or a set of practices that prioritize speed and clarity over granular detail. Most setups rely on cloud-based platforms, bank feed integrations, and pre-built templates to keep things moving.
Core Components of Quick Accounting Gameplay
At its foundation, quick accounting revolves around three things: automated bank feeds, smart categorization, and one-click reporting. The automation piece is what separates this from traditional manual bookkeeping. When your bank transactions pull in automatically and match against existing invoices or bills, you're no longer entering data by hand. That alone cuts the time spent on routine entry by roughly 80 to 90 percent depending on transaction volume. Smart categorization means the system learns from your choices. You classify a transaction once, the platform remembers it, and future similar transactions get auto-suggested. This works well until it doesn't. I ran into a case where a vendor's name changed mid-year on their invoices but their bank record stayed the same. The system kept misclassifying half the payments because it had already locked in the old vendor mapping. The workaround was to create a separate expense account for that vendor, import the corrected batch manually, and then merge the accounts in the next reporting period. It added maybe twenty minutes to the month-end close but prevented a messy reconciliation later. One-click reporting gives you a profit and loss statement, balance sheet, and cash flow forecast without building custom queries. For most small operators, that's everything they actually need. The ones who try to build detailed dashboards usually end up spending more time maintaining the reports than they save on analysis.
Setting Up Your First Quick Accounting Workflow
Start by choosing a platform that supports bank feed integration. Popular options include QuickBooks Online, Xero, FreshBooks, and Wave. Each has different strengths, but the common thread is that they all connect directly to business and personal bank accounts. Avoid tools that require manual CSV uploads unless you have fewer than fifty transactions per month. The overhead of importing and matching files eats the efficiency gains you're trying to capture. Once you've picked a platform, connect your primary checking and savings accounts. Most integrations use Plaid or a similar aggregator, so you'll log in through a secure third-party portal. This step can take anywhere from five minutes to half an hour depending on whether your bank plays nicely with the aggregator. I've seen banks like Charles Schwab and certain credit unions cause persistent sync failures that required switching to manual download mode for months until the integration updated on their end. There's no real workaround other than patience and periodic reconnection attempts. Next, set up your chart of accounts. Don't overcomplicate this. A standard small business setup needs maybe twelve to twenty accounts total: checking, savings, credit card, accounts receivable, accounts payable, revenue accounts segmented by product or service line, and a handful of expense categories. If you find yourself creating sub-accounts for everything, you're doing it wrong for this approach. The goal is speed, not granularity.
Get the Full Details

Configure auto-categorization rules. Most platforms let you set rules like "if vendor contains Staples, categorize as Office Supplies." Spend about an hour getting these right. It pays off immediately as transactions start flowing in. Then schedule a daily or weekly review routine where you go through unmatched transactions, verify categorizations, and mark anything unusual for follow-up. Twenty minutes a day is enough to keep things current without letting the queue pile up.
Common Pitfalls and How to Avoid Them
The biggest mistake I see people make is treating quick accounting like quick fixing. They set it up, forget about it for six months, then come back to a mess of uncategorized transactions, duplicate entries, and mismatched bank balances. The system isn't self-maintaining. You have to check in regularly, even if it's just a brief review. Another issue is mixing personal and business transactions. Some people run their entire financial life through one connected account to save time. This creates reconciliation nightmares faster than almost anything else. Keep personal spending separate, or at least maintain a clearly tagged category that you reconcile monthly. I once spent three hours untangling a home renovation expense from a client entertainment deduction because both came through the same account and neither had proper tags. Never again. Over-reliance on automated matches is the third trap. The system will confidently match transactions that look similar but aren't actually the same. A $47.50 payment to a vendor named ABC Corp won't necessarily match a $47.50 invoice from ABC Corp if the dates are wrong or if the invoice was already paid through a different method. Always spot-check matched transactions, especially in the first few months while your rules are still calibrating.
Quick Accounting Gameplay works well when you treat it as a habit, not a one-time setup. The returns are real, but only if you stay engaged with the process. The platforms do the heavy lifting, but they don't do the thinking. If you respect that boundary, you'll save hours every month and keep your books clean enough to survive an audit without pulling your hair out.