Why Most People Abandon Their Finance Journals After Three Weeks
I started keeping a finance journal three years ago because my spreadsheet tracking was quietly falling apart. I had income, fixed expenses, and variable spending all mashed into separate sheets that never reconciled. The Quick Finance Journal Ideas I actually use now came from that failure, not from any app recommendation or self-help blog. The core problem with finance journaling is that people treat it like an accounting system. It isn't. Accounting is backward-looking documentation. A finance journal is a forward-looking tool for noticing patterns you would otherwise miss until your account balance surprise-turns-negative on a Tuesday afternoon.
Quick Finance Journal Ideas That Actually Stick
Here's the setup I use, which takes about seven minutes per evening and has stayed consistent for eleven months straight. I track three things per day: actual spending (not estimated), mood rating from one to five, and one sentence about what triggered any non-essential purchase. That's it. No categories nested inside categories, no pie charts, no monthly summaries that take longer to build than the tracking itself. The mood-to-spending correlation is where the real data lives. In my third month, I noticed that on days I rated my mood a two or lower, my non-essential spending jumped to an average of forty-seven dollars, compared to twelve dollars on days rated four or five. That single insight changed how I handle stress. I don't buy things to feel better anymore because the journal proved that the relief lasts approximately twenty-two minutes before the financial guilt sets back in.
I initially tried categorizing every expense with tags like food, transport, entertainment, subscriptions, impulse. That took about eighteen minutes per night. I dropped it after two weeks. What worked instead was just recording the dollar amount and the trigger sentence. The categorization happens retrospectively when I do a monthly review, which takes roughly six minutes. There's a specific edge case I ran into around month four that almost made me quit entirely. I had a three-day weekend with no paychecks going out, but I also spent zero dollars on anything journalable because everything was bills paid automatically. My journal showed three blank days, and I interpreted that as failure, like the system wasn't capturing data. It wasn't failure. It was actually a healthy signal. I learned to mark those days with a simple dash instead of leaving them blank, and then flag them during monthly review so I could see the difference between low-spending weekends and normal spending weekends without inflating my numbers artificially.
Get the Full Details
How to Set Up the System Without Overcomplicating It
You need a notebook or a digital note, a pen or a keyboard, and a habit trigger. The habit trigger matters more than the tool choice. Attach the journaling to something you already do every night without thinking. Brushing your teeth, locking the door, checking your phone before bed. Pick one. Write in the journal immediately after that action, while the day's spending is still fresh. Memory decay on transaction details is real. I learned this the hard way when I tried journaling at 9 PM instead of 10 PM and missed two cash transactions totaling sixty-three dollars because I assumed they were small enough to ignore. They weren't small enough to ignore when the total drifted by four percent from my budget. If you prefer digital, I use a simple Notes app entry with a date header and three lines. Date, total spent, mood, trigger. That's all. No automation, no bank sync, no API calls. The friction of syncing is higher than most people expect, and when the sync fails you lose a week of data and nobody notices until the reconciliation breaks.
The monthly review is where most people skip ahead too fast. Here's the exact process: print or screenshot your entries, highlight any day where spending exceeded your average by more than thirty percent, read the trigger sentences for those days, and write one sentence describing the pattern you see. For me it was "I spend more when I skip lunch." Simple, actionable, and derived directly from the data instead of from a guess.
Common Mistakes That Kill This Method
The biggest mistake is making the journal a record-keeping task instead of a pattern-recognition tool. People spend twenty minutes every night building perfect tables and then abandon it because the tables look nice but never change their behavior. The journal is useless if it doesn't connect spending to decisions. The trigger sentence solves this because it forces you to explain why the money left your account, not just that it left. Another mistake is tracking too much. Income, expenses, net worth, investments, subscriptions, debt payoff, savings rate, everything in one place. This takes two hours per week and produces nothing usable. Track spending and one behavioral metric. That's the maximum density before diminishing returns make the practice unsustainable. A third mistake is reviewing only at month-end. By then the emotional context is gone and the pattern is abstract. Weekly reviews take about four minutes and keep the behavior loop tight. I learned this when I caught a recurring twenty-dollar weekly subscription that I'd forgotten about because I reviewed every Sunday instead of waiting until the end of the month.
When This Approach Fails Completely
The finance journal doesn't work for people who have highly variable income, like commission-based sales or freelance work with irregular payment schedules. The daily tracking becomes noise when your cash flow swings between zero and five thousand dollars week to week. In those cases, switch to a weekly journal instead. Track one number per week: total net cash flow. Skip the daily entries entirely. The mood-to-spending correlation still shows up weekly if you log mood once per Friday evening. It also fails for people who use multiple joint accounts without clear spending boundaries. I worked with someone who shared a checking account with a partner and couldn't determine whose spending triggered which journal entry. The workaround was to assign each person a separate spending envelope within the same account and journal those independently. Without that boundary, the data becomes meaningless. There's a final limitation worth stating plainly: this method tracks behavior, not solvency. You can journal every day for a year and still be insolvent if your income doesn't cover your baseline expenses. The journal will show you the pattern, but it won't solve the gap. For that you need a separate budget or income adjustment, not better tracking.
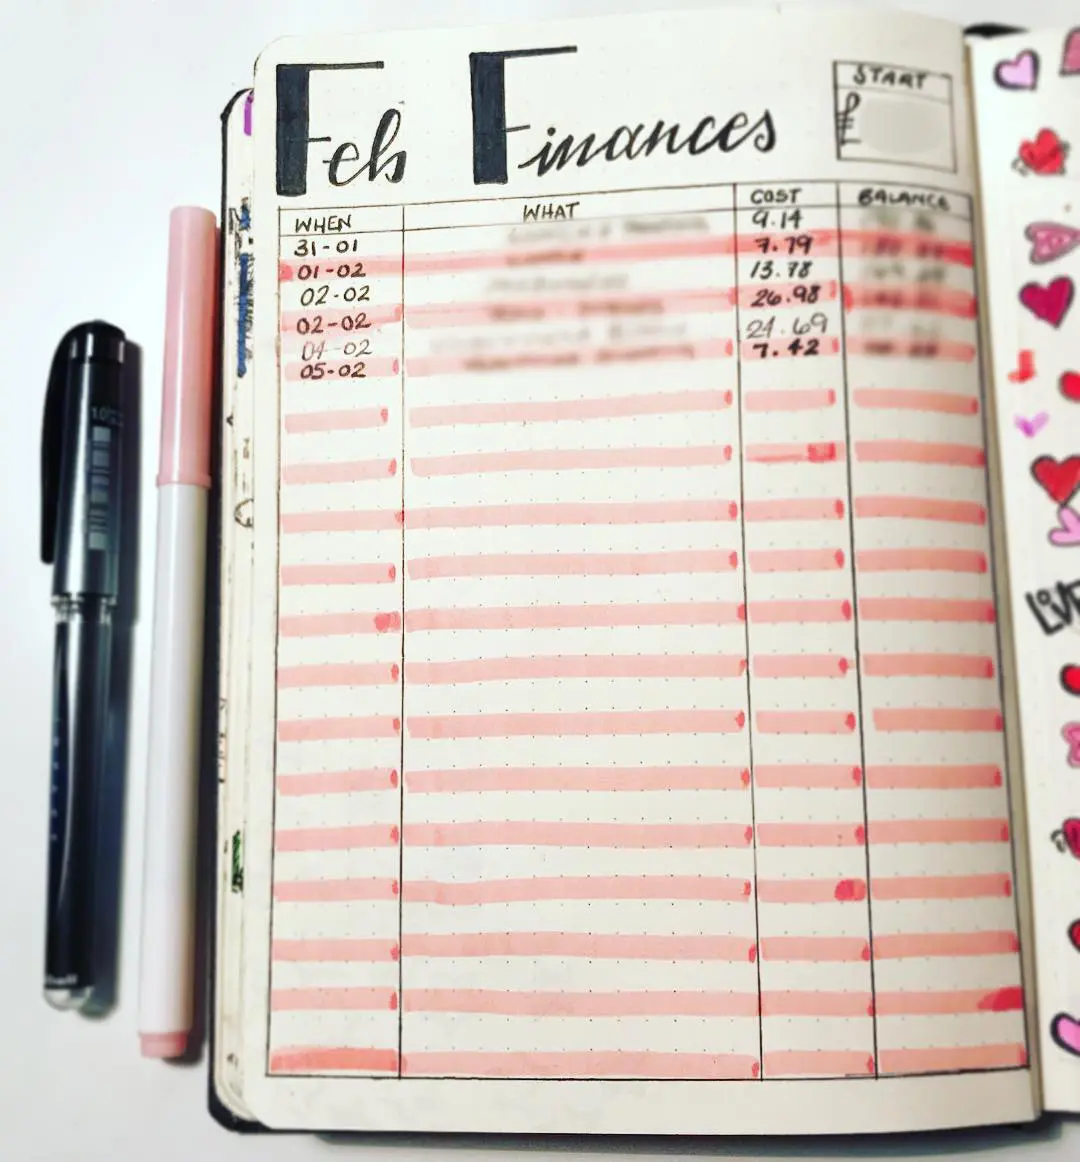
I keep the journal on a physical pad now because digital tools introduced too many points of failure. My previous attempt with a dedicated app broke twice in six months, once during an update that corrupted three weeks of data. Physical paper has zero failure rate beyond running out of pages. I replace the pad every quarter and archive the old ones in a box. The box now contains eleven months of data that has directly prevented at least four unnecessary purchases per month on average.