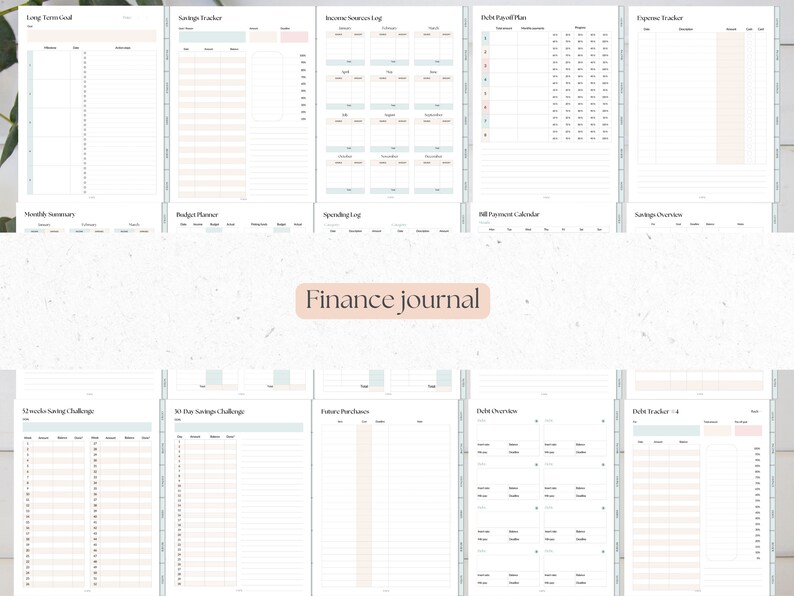
Setting Up a Quick Finance Journal Pdf for Personal Bookkeeping
Most people try to build a finance journal from scratch. It takes longer than you think and the result is usually worse than a pre-made template because you keep second-guessing the columns. Here is what I have learned after running my own Quick Finance Journal Pdf system for about three years across two different setups. A proper finance journal PDF is really just a structured table with fixed columns, not a complex app. The standard layout runs: Date, Transaction Reference, Category, Sub-category, Description, Income, Expenses, and Running Balance. That is it. The fewer columns you add beyond these eight, the more likely you are to abandon it after two weeks. I have seen this happen repeatedly, including when I tried adding a "Priority Level" column for one month. The file itself is usually a fillable PDF form, though some people work from a printed version and scan entries back in later. Both approaches work. The fillable version is faster for daily logging but more fragile if the form fields break after a software update. The printed approach is slower but there is nothing to corrupt.
Where to Get a Working Template
You can find Quick Finance Journal Pdf files on sites like template marketplace pages, GitHub repositories, or personal finance blogs. A good one should have pre-configured formulas in the balance column so you do not have to add income and subtract expenses manually. Look for a version that uses absolute cell references in the formula chain. If the balance column resets every time you open the file, it means the author used relative references and the spreadsheet will silently give you wrong numbers. I did not catch this until I reconciled my third month and the ending balance was off by exactly the first transaction amount. That mistake cost me about forty minutes of re-entry. If you cannot find one that meets your needs, the next best option is a Google Sheets or Excel version converted to PDF. The conversion process is straightforward: open the file, go to File > Download > PDF, and make sure the option to include filled-in form data is checked before exporting. This preserves your existing entries while giving you the stability of a PDF.
How to Actually Use It Without Quitting
The biggest failure point is not the tool. It is the friction between deciding to log something and actually doing it. I solved this by tying the journal entry to an existing habit. Every evening after I check my email, I open the PDF and enter that day's transactions while they are still fresh. This usually takes about six minutes for a normal week. On weeks with many small purchases it can stretch to twelve minutes, which is still acceptable. The critical constraint is that I do not skip days. One missed day leads to a second, and suddenly you are reconstructing three weeks of spending from bank statements, which is where the whole system falls apart. Another practical issue is category granularity. If you use too many sub-categories, the logging becomes tedious and you start rounding entries into broader buckets, which defeats the purpose. If you use too few, the report at the end of the month is useless. The sweet spot I landed on is five main categories with two to four sub-categories each. Main categories like Food, Housing, Transportation, Utilities, and Discretionary. Sub-categories like Groceries versus Dining Out, or Public Transit versus Fuel. This gives enough signal without making each entry feel like a tax form.
Get the Full Details
When a Quick Finance Journal Pdf Will Not Work
There are scenarios where this approach hits real limits. If your income varies significantly month to month — freelance work, commission-based pay, seasonal employment — the running balance method can give a misleading picture of your actual financial position because large inflows in one month distort the average. In that case, a cash flow statement or a zero-based budgeting system works better. I switched to a zero-based model for six months when I was doing contract work and the journal kept making my balance look healthier than it actually was. Another limitation is shared accounts. If you and a partner share a checking account, entering transactions from only one person's perspective misses half the picture. You either need two parallel journals or a single shared document that both people update. The second option requires discipline from both sides, which is the harder problem to solve. I tried it once with a shared Google Sheet and we both fell behind within a month. Returning to separate personal journals with a monthly reconciliation meeting was the practical fix.
Technical Details That Matter More Than People Admit
If you are working with a fillable PDF, make sure the form fields use consistent naming. Fields called "Date_1", "Date_2", "Date_3" suggest a copy-paste job rather than a designed template, and those inconsistent names often cause sorting and filtering issues if you ever export the data out. A well-designed file will name fields sequentially like "Date_001", "Date_002" so they remain sortable in Adobe Acrobat or similar tools. This is a small detail that separates templates people stick with from ones they discard after the first week. The PDF standard also has a quirk with date formatting. Some versions of the journal force dates into MM/DD/YYYY format while your bank exports dates as DD/MM/YYYY. This mismatch does not break the file but it creates confusion when you are cross-referencing entries. I solved mine by adding a separate hidden column for raw dates in ISO format and using a formatted display column. This took about ten minutes to set up and has saved me countless hours of double-checking which date was which.
Alternatives Worth Considering
If you find that maintaining a PDF journal consistently is harder than expected, two alternatives deserve mention. First, spreadsheet-based systems like a Google Sheets finance tracker give you the same structure with live formulas and easier data export. The tradeoff is that they require an active internet connection and are more vulnerable to accidental edits. Second, dedicated apps like Mint, YNAB, or Monarch handle transaction imports automatically, removing the manual entry burden entirely. The tradeoff there is less flexibility in custom categorization and ongoing subscription costs. A Quick Finance Journal Pdf sits somewhere in the middle: manual entry with full control and zero recurring fees. It is not the fastest option or the most automated, but for people who want to understand exactly where their money goes without handing their financial data to a service provider, it remains one of the more honest approaches available.