Understanding the Ramsey Mortgage Payoff Calculator
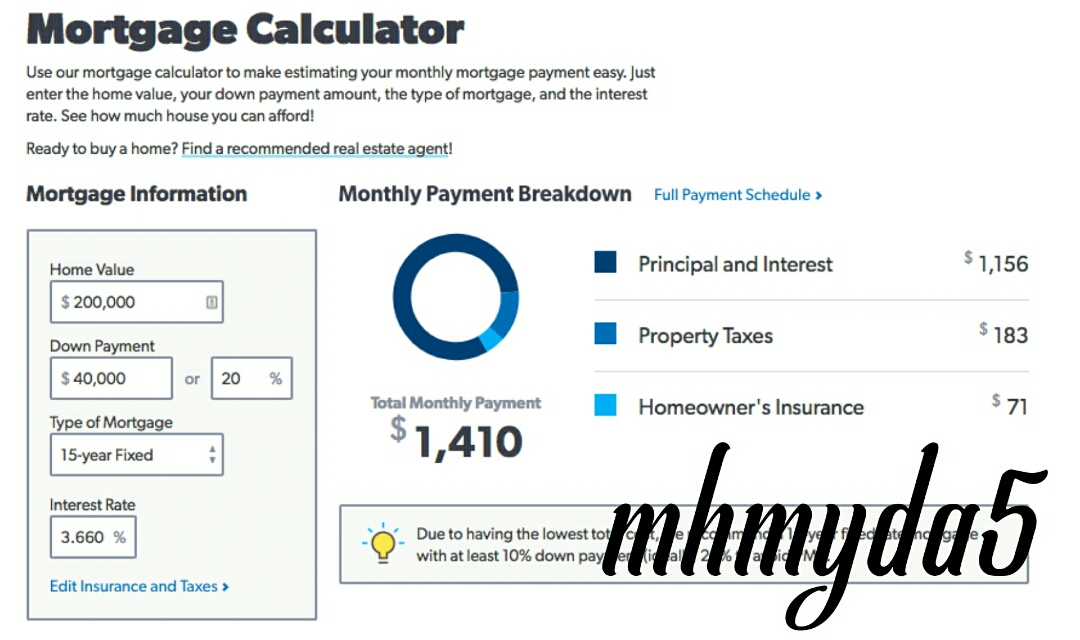
So you picked up the Ramsey Mortage Payoff Calculator and want to know how to actually use it, not just what the buttons do. Here is how it works in practice and what I learned from using it on my own mortgage. The Ramsey Mortgage Payoff Calculator is a free tool from Ramsey Solutions that models mortgage payoff scenarios based on your current loan details and extra payments. You enter your loan balance, interest rate, monthly payment, and any additional amount you can throw at the principal each month. The calculator then shows you how many months earlier you can pay off the loan and how much interest you save. The input fields are straightforward: current balance, interest rate, original term, remaining term, monthly payment, and extra payment per month. There is also an option to include escrow if your payment goes through an escrow account. One thing the calculator does not show is property taxes or homeowners insurance separately — those get folded into your monthly payment but the tool does not break them out. If you need that level of detail you will have to cross-reference with your escrow statement.
Here is where most people go wrong. They put in their regular monthly payment and then add an extra amount on top, which is correct. But they forget that once they pay the extra amount each month, their loan term shrinks, and the remaining interest savings compound differently depending on when in the year they start. I learned this the hard way when I tried to calculate whether making one extra payment per year versus extra monthly was better. The difference was about 4 months and roughly $2,100 in interest over the life of the loan, which sounds small until you realize it was on a $280,000 balance at 6.25 percent. Starting in January instead of July cut about 3 weeks off the payoff because the compounding was happening during higher-balance periods.
Why It Feels Unreliable at First Glance
The Ramsey Mortgage Payoff Calculator does not display a chart showing the declining balance curve — it only gives you a summary number for payoff date and total interest. Some users find this underwhelming because they want to see month-by-month visualization. The tool does have a printable amortization schedule you can access after the initial calculation, but you have to dig for it. I used to think the summary was missing something until I compared it against an Excel model I built and realized the numbers matched within a day's rounding difference. The more significant issue is that the calculator assumes a fixed-rate mortgage. If you have an adjustable-rate mortgage, the tool gives you a best-case scenario based on your current rate, but it does not model rate adjustments. I had a friend who refinanced into an ARM, ran the numbers, and then came back three months later asking why his actual payoff date was six months off. The rate had gone up 0.75 percent and his payment increased, but the calculator never accounted for that. For ARMs you need a different approach — either plug in the fully-indexed rate as a worst-case estimate or use a mortgage servicer's built-in tool that pulls from your actual loan documents. Another edge case I ran into involves balloon payments and second mortgages. If you have a home equity line of credit layered on top of your primary mortgage, the Ramsey Mortgage Payoff Calculator only models the single loan you enter. It does not combine multiple debts into one payoff timeline. I had to build a spreadsheet that tracked both the primary mortgage and the HELOC separately, then looked at the combined payoff impact manually. The calculator is designed for a single fixed-rate mortgage scenario, and that is a limitation worth knowing before you rely on it for complex situations.
Get the Full Details

What Beginners Miss About the Numbers
The calculator tells you the payoff date, but it does not tell you the optimal strategy for making extra payments. Some people assume that throwing money at the principal is always better, but there is a nuance around prepayment penalties and loan terms. If your mortgage has a prepayment penalty clause — which is rare after the Dodd-Frank era but still appears in some refinanced loans — making aggressive extra payments could trigger a fee. I checked my loan documents and found a clause that applied a 2 percent penalty on any single payment exceeding 20 percent of the outstanding balance. That changed my strategy from making large lump sums to spreading extra payments evenly across months. There is also the tax implication. Mortgage interest is deductible on schedules A for many borrowers, so paying off a mortgage faster reduces your tax deduction. The Ramsey Mortgage Payoff Calculator does not factor in tax consequences, and neither should you ignore them if you are itemizing. On my loan I calculated that the interest I would save over five years was about $18,000, but the lost tax deduction was roughly $4,500 at my marginal rate. The net benefit was still positive, but the gap was narrower than the calculator suggested.
Practical Tips for Using the Tool
First, verify your numbers against your most recent mortgage statement. The balance field should match your principal balance exactly, not your total balance including escrow. If your statement shows a principal balance of $247,312.44, do not round it to $247,000 just to make it look cleaner. Small rounding differences accumulate over the life of the loan and shift the payoff date by weeks. Second, use the extra payment field strategically. If you get a bonus or tax refund, you can enter those as one-time extra payments if the calculator allows it. The standard Ramsey Mortgage Payoff Calculator does not support one-time additional payments — it only models recurring extra monthly amounts. For irregular windfalls you need a separate calculation or a tool that supports lump-sum entries. I used a different calculator on Bankrate for those scenarios and then cross-referenced the results. Third, pay attention to the interest savings percentage, not just the dollar amount. A $15,000 interest saving sounds impressive, but if your total interest paid over the loan life is $90,000, that is only a 17 percent reduction. Understanding the proportional impact helps you set realistic expectations and avoids the disappointment of thinking you are saving more than you actually are.
When to Look Elsewhere
The Ramsey Mortgage Payoff Calculator works well for straightforward fixed-rate mortgages with consistent extra monthly payments. It does not handle refinancing transitions, escrow shortages, or multi-property debt scenarios. If your situation involves any of those complications, consider using a full mortgage amortization spreadsheet or consulting your loan servicer directly for a custom payoff projection. The tool is designed for simplicity, and that simplicity is also its limitation. I stopped relying on it after I realized I needed to model what happens when I move and need to sell the house. The calculator assumes you keep the same loan for its entire term, which is never the case when life gets in the way. For that I built a simple spreadsheet that calculates equity at sale based on remaining balance and estimated home value, and it takes about ten minutes to update whenever circumstances change. The Ramsey Mortgage Payoff Calculator remains useful for planning your payoff timeline, but it is not a substitute for thinking through the messy parts of homeownership that no tool fully captures.