Reading A Credit Card Statement Worksheet
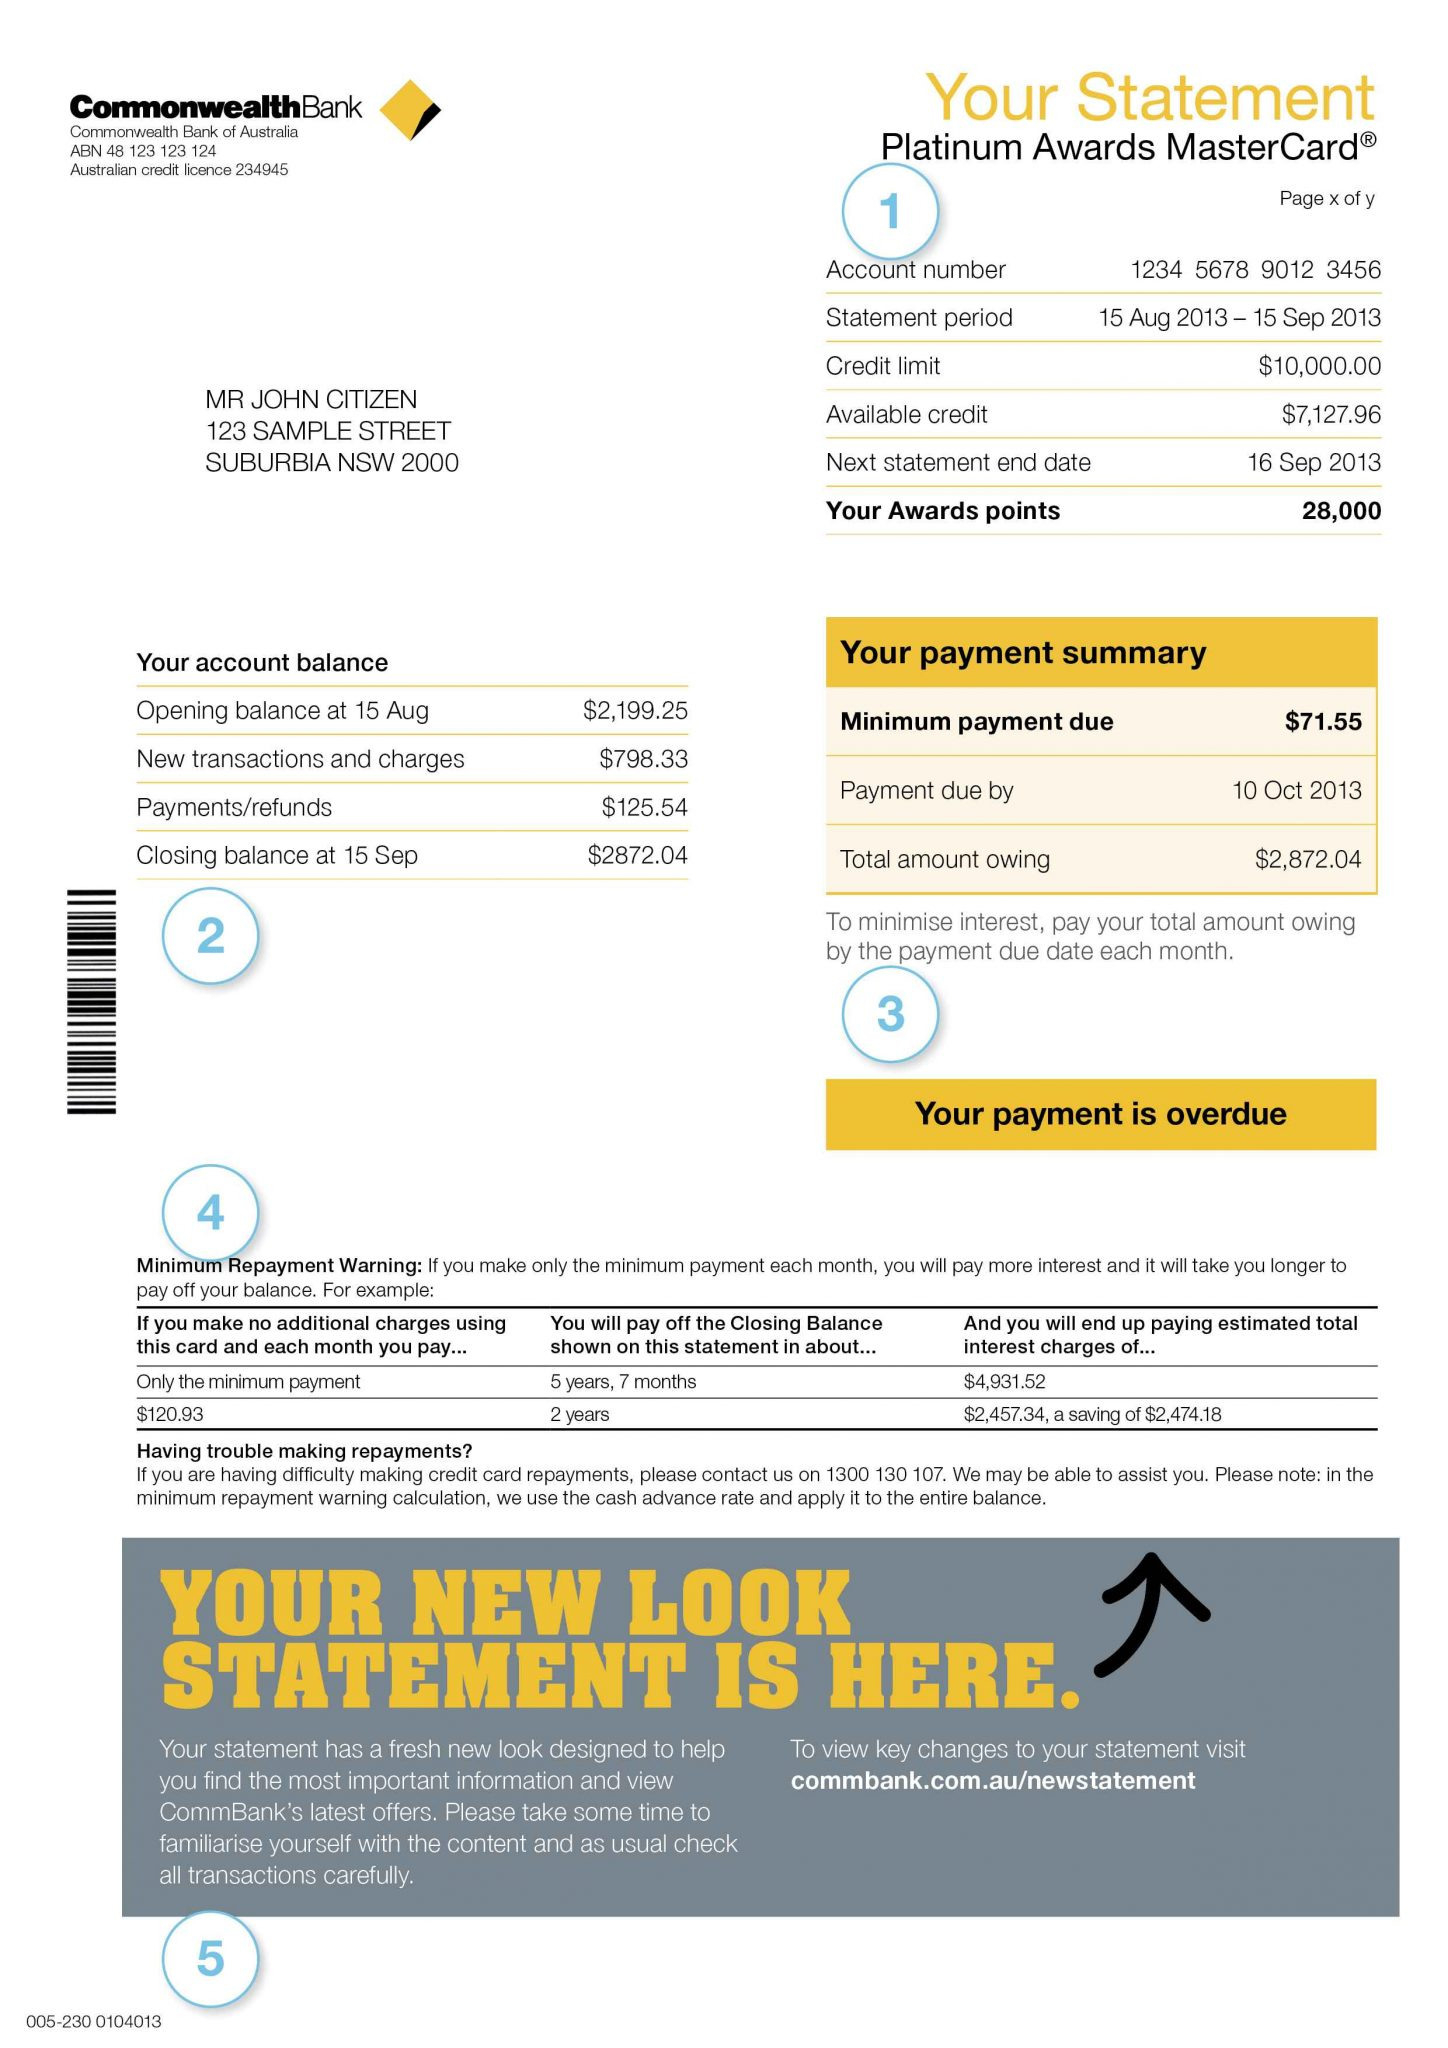
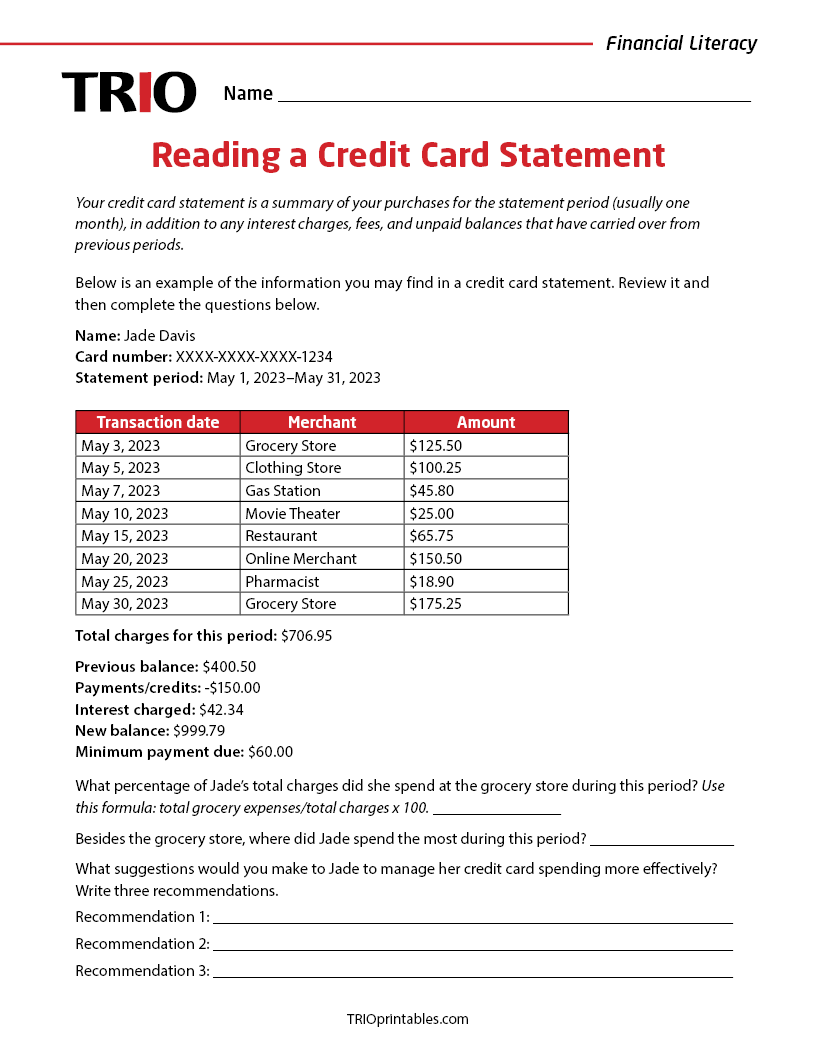
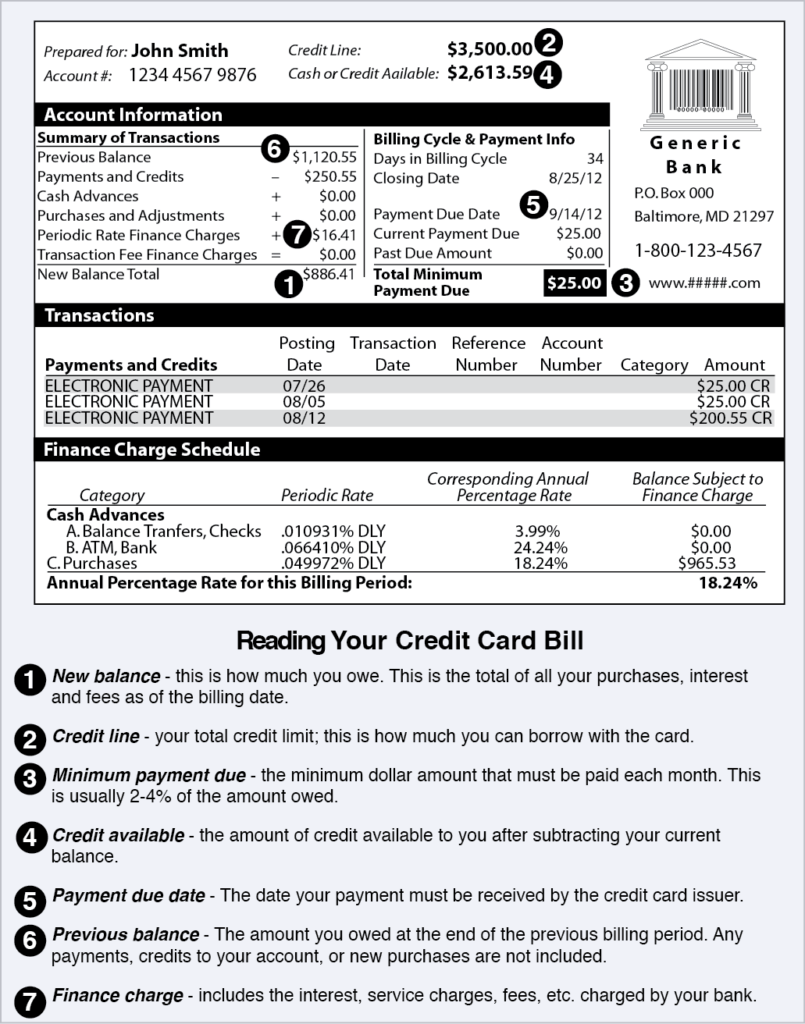
The way most people approach a credit card statement is completely wrong. They look at the bottom line and think they understand their spending. That bottom line is usually a mess of pending charges, fees, rewards credits, and payment adjustments that haven't resolved yet. I spent years reconciling these for small business clients before realizing the standard statement format was designed to hide more than it reveals. What you actually need is a structured approach that forces every single line item into a category where it belongs. A Reading A Credit Card Statement Worksheet does exactly this. It takes the raw data from your monthly statement and pushes it through a filtering system so you can see what was real spending versus what was just accounting noise. Here is how the process actually works in practice. First, pull your statement in PDF or CSV format. CSV is significantly better because you can manipulate the data directly. If your bank only offers a PDF, use a basic text extraction tool or type the entries into a spreadsheet manually. The manual entry takes longer but actually forces you to look at each transaction, which catches things automated tools routinely miss.
The core structure of the worksheet needs these columns: Transaction Date, Posted Date, Description, Amount, Category, Receipt Status, and Notes. The Posted Date column is the one everyone skips and should not skip. The Transaction Date is when you made the purchase. The Posted Date is when the bank actually settled it. These dates diverge constantly, and if you are doing monthly budgeting based on transaction dates alone, your balances will be off by hundreds of dollars most months. I ran into a specific problem with a client who kept thinking she was overspending every quarter. Her statement looked fine, but her actual cash position was tighter than expected. The issue was recurring subscription charges that posted on different dates each cycle. One month her Netflix charge posted on the 28th, the next on the 3rd of the following month. She was categorizing everything by transaction date and seeing phantom spikes. The workaround was simple: I had her switch to grouping by posted date and adding a running twelve-month rolling total instead of looking at any single month in isolation. The apparent spending variance dropped to under three percent. The category column deserves its own explanation. Most people use overly broad categories like "food" or "transportation." This creates noise. You need subcategories. Food at home and food at restaurants behave completely differently in terms of budget control. Transportation fuel and ride-sharing services have different flexibility thresholds. When you break categories down to about eight to twelve subcategories, patterns emerge that broad categories completely obscure. I typically recommend starting with fifteen subcategories and merging downward if you find yourself creating new ones constantly.
The Receipt Status column is where most people fail. Mark every transaction as either "receipt on file," "receipt needed," or "no receipt possible." Physical stores and online purchases require receipts for tax purposes if you are tracking business expenses. Digital services often provide automatic receipts through email. Gas stations notoriously fail to provide itemized receipts unless you ask explicitly. Flagging these items on the worksheet prevents end-of-quarter scrambling. There is a counter-intuitive insight about statement worksheets that most beginners miss. The statement itself is not your primary spending record. It is a reconciliation document. Your primary spending record should be whatever system you used at the point of purchase, whether that is a budgeting app, a simple expense log, or just the confirmation emails from online orders. The worksheet exists to cross-reference these two sources and identify gaps. When you treat the statement as the source of truth rather than the verification layer, you are working backwards. Another nuance people overlook involves purchase price adjustments. A merchant might authorize a transaction for a certain amount, you might return part of the purchase a week later, and the original charge and the refund appear as separate line items on your statement. Without the worksheet structure, these two entries cancel each other out visually and you lose the category information permanently. The workaround is to add a "match ID" column where you link related transactions together. This single column eliminates an entire class of categorization errors.
Get the Full Details
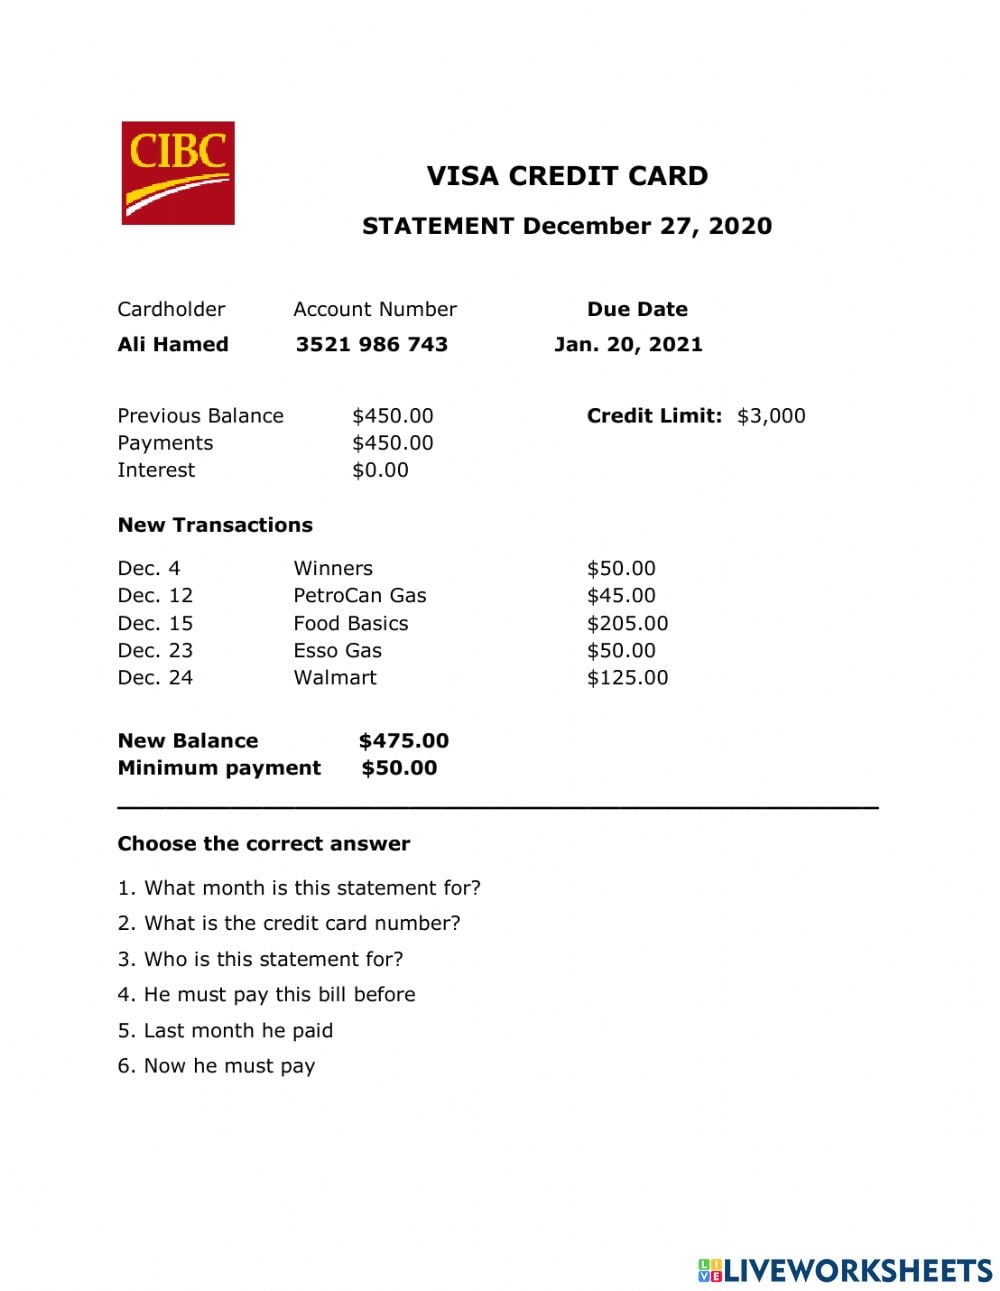
The notes column serves a different purpose. Use it for anything that requires follow-up, disputes to file, or anomalies to investigate. If a charge shows up that does not match any of your recent purchases, write it in the notes column with the date and amount. Do not just delete it or ignore it. Fraudulent charges often hide inside statements disguised as legitimate merchant names. The notes column creates an audit trail that makes dispute resolution significantly faster. You can build this worksheet in any spreadsheet application. Google Sheets, Excel, and LibreOffice Calc all handle the basic requirements. I prefer Google Sheets for this work because multiple devices can access it, and the automatic date formatting reduces data entry errors. Set up conditional formatting to highlight any transaction over a certain dollar threshold that you have not yet categorized. Anything over fifty dollars that sits uncategorized for more than a week is probably something you need to investigate. The reconciliation process itself should take place within three days of the statement closing date. Waiting longer introduces memory decay. You will not remember why you bought something three weeks later. Set a calendar reminder for the day after your statement generates. This timing is not arbitrary. Bank statements often include provisional credits and pending transactions that resolve within a 48-hour window. Working within that window means you are reconciling finalized numbers, not estimates.
One limitation of this approach is that it does not help with debt management strategy. A Reading A Credit Card Statement Worksheet tells you where your money went. It does not tell you which balance to prioritize paying down. If your goal is specifically debt reduction, you need a separate amortization tracker alongside the worksheet. The two systems serve different purposes and combining them usually degrades both. Another honest limitation is that the worksheet requires consistent discipline. If you skip a month, catching up becomes genuinely difficult because you lose the temporal context. I have seen people accumulate three or four months of back-reconciliation and then abandon the entire system because the backlog felt insurmountable. The solution is to keep the current month's work under forty-five minutes and never let more than one month pile up. If your spending is relatively simple, with fewer than twenty transactions per month across two or three cards, you might not need a formal worksheet at all. A basic spreadsheet with date, description, amount, and category columns will suffice. The structured approach described above becomes necessary when you have multiple accounts, business expenses mixed with personal spending, or a subscription density that makes pattern recognition difficult without structure.
Getting Started With Your Worksheet
Download a blank template and populate it with your most recent statement. Do not try to go back further than one month initially. Complete the full reconciliation for that single month, including the match ID column and receipt status flags. Once you have done it once manually, you will understand the friction points and can adjust the structure accordingly. The second month should take roughly half the time of the first. By the fourth month, the process typically settles into a routine that consumes about fifteen to twenty minutes per statement cycle for most users. The real value of this system does not appear in the month you implement it. It appears three to six months later when you are reviewing quarterly trends or preparing documentation for a loan application or tax filing. Having a clean, categorized record of every dollar that passed through your credit accounts removes an entire category of administrative stress that most people do not anticipate until they actually need it.