Understanding Paycheck Stubs: What They Actually Show You
Paycheck stubs are one of those documents people glance at and then immediately forget about. You see your gross pay, maybe some deductions, and a net figure. The rest is a blur of abbreviations you don't bother learning. That habit costs you money if you ever need to verify what your employer actually paid versus what they claimed they withheld. I've been doing payroll for fifteen years. I've seen people overpay taxes because they couldn't read their own W-2 reconciliation, miss reimbursement eligibility, and get caught in wage garnishment disputes where they had no paper trail. The stub is your first line of defense. Learning to read it takes about twenty minutes if someone shows you the right parts.
Reading A Paycheck Stub Worksheet Answers: Where Most People Get Stuck
When you grab a paycheck worksheet template, the hardest section isn't the math. It's the codes. Your employer uses internal shortcodes for benefits that aren't standardized. State-specific tax tables change year to year. What looked like a simple subtraction problem becomes a matching exercise where you're trying to decode why your 401(k) contribution shows up three different times across the stub. Here's a problem I ran into last fall that took me an hour to resolve. My state had just changed its withholding calculation method from the percentage approach to the flat credit method. The new format showed my taxable wages in a separate box, and my worksheet template still had the old line structure. Every time I filled it out, the final numbers didn't match my bank deposit. The discrepancy was exactly forty-seven dollars. I finally realized the template hadn't been updated for the new credit line, and the old form was subtracting the credit twice. Once in the federal section, once in the state section. The workaround was to manually add a footnote line and recalculate using the new worksheet format from the state revenue department's website. This isn't unusual. Worksheet templates lag behind policy changes by a quarter at minimum. Sometimes longer. If you're using a downloaded template that hasn't been revised in two years, assume it's wrong until you verify against a current stub.
How to Read Your Paycheck Stub Properly
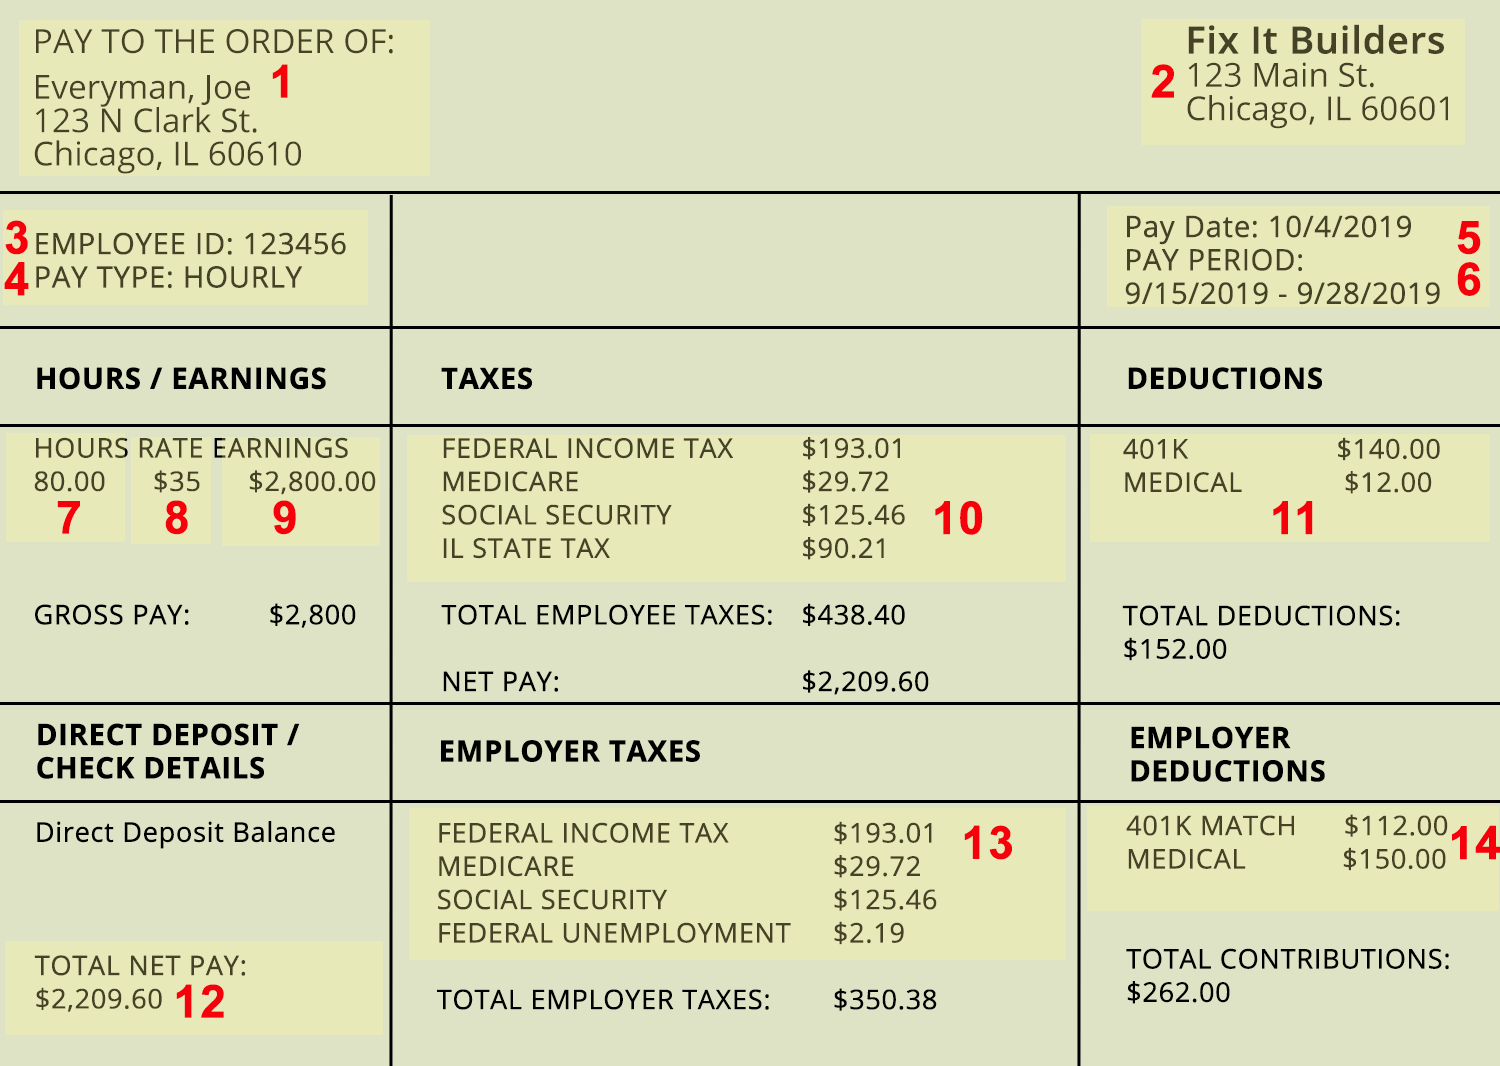
Start with the earnings section. This shows your gross pay before any deductions. Look for hourly rate, regular hours, overtime hours, and any bonus or commission entries. Each line should have a year-to-date total in a separate column. If the YTD doesn't match the previous stub plus the current period, flag it immediately. Move to the deductions section next. This is where most confusion happens. Pre-tax deductions reduce your taxable income. Post-tax deductions do not. The difference matters for your tax filing. Common pre-tax items include 401(k) contributions, health insurance premiums, and flexible spending accounts. Common post-tax items include wage garnishments and Roth 401(k) contributions. Check your tax withholdings carefully. Federal income tax, Social Security, and Medicare should each have their own line. Some stubs combine Social Security and Medicare into a single FICA line. That's normal. State and local tax lines vary by jurisdiction. If you work in multiple states, you may see withholding for each one separately.
Get the Full Details

Calculate your net pay yourself using a simple formula. Gross pay minus pre-tax deductions gives you taxable income. Subtract tax withholdings from that amount. Add back any post-tax deductions if they were already subtracted. The result should match your net pay exactly. If it doesn't, you found an error worth correcting before payday.
Common Paycheck Stub Errors and How to Fix Them
Double withholding is the most frequent mistake. This happens when your employer processes a deduction twice, usually after a system migration or benefit enrollment change. The fix is straightforward. Document the error with screenshots of both charges. Submit a written request to payroll with your employee ID and the specific dates. Most employers correct this within two pay periods. If they don't, escalate to your state labor department. Miscalculated overtime is the second most common issue. This occurs when your regular hours are entered incorrectly or your overtime multiplier is wrong. The standard rate is one and a half times your regular hourly wage for hours worked over forty in a workweek. Some employers make mistakes with salaried employees, calculating overtime based on an incorrect regular rate. If your overtime pay seems low, request a written explanation of how your regular rate was determined. Incorrect year-to-date totals happen more often than you'd think. A single data entry error can throw off your entire annual withholding picture. This affects your tax refund or balance due. Always compare YTD figures against your previous stub. If a discrepancy exists, report it immediately so your employer can adjust before tax filing season.
When Paycheck Worksheets Aren't Enough
Some situations require more than a standard worksheet. Independent contractors don't receive stubs at all. They rely on Form 1099s, which look completely different. If you're a contractor trying to understand your income documentation, a paycheck worksheet won't help you. You need to track business expenses separately and calculate estimated quarterly taxes on your own. Employees with multiple jobs face a similar problem. Each employer withholds taxes based on single-job assumptions. This often results in under-withholding. A standard worksheet shows each paycheck correctly in isolation but doesn't reveal the combined tax impact. You may owe taxes at filing time even though every stub looked fine individually. Workers in states without income tax should still review their stubs carefully. No state withholding doesn't mean no documentation. Your stub should show federal and FICA deductions at minimum. Some employers also deduct for local taxes or mandatory benefit programs that exist even in no-income-tax states.

Using Worksheets for Tax Preparation
Paycheck stubs are essential for accurate tax filing. Keep all stubs from January through December. You'll need them to reconcile your W-2 at tax time. If your W-2 shows different totals than your stubs, investigate before filing. The IRS matches your return against employer reports, and discrepancies trigger audits. Worksheet answers should match your actual stubs, not theoretical calculations. Use real numbers from your pay documentation. If you're working from memory or estimates, your worksheet will be wrong. This creates problems during tax filing and potential issues if you're audited. Save stubs digitally if possible. Many employers offer online portals where you can download PDF versions. This makes record keeping easier and ensures you have copies even if you lose paper stubs. Some states require employers to retain stub records for three to seven years. Having your own digital copies protects you if your employer's system fails.
Don't ignore small discrepancies. A twenty-dollar difference on one stub might seem minor. But if it repeats monthly, you're losing two hundred forty dollars annually. Track patterns, not just individual paychecks. Regular monitoring catches systematic errors before they become significant financial problems.