The Difference Between Real And Nominal Gdp Is Where Most People Mess Up
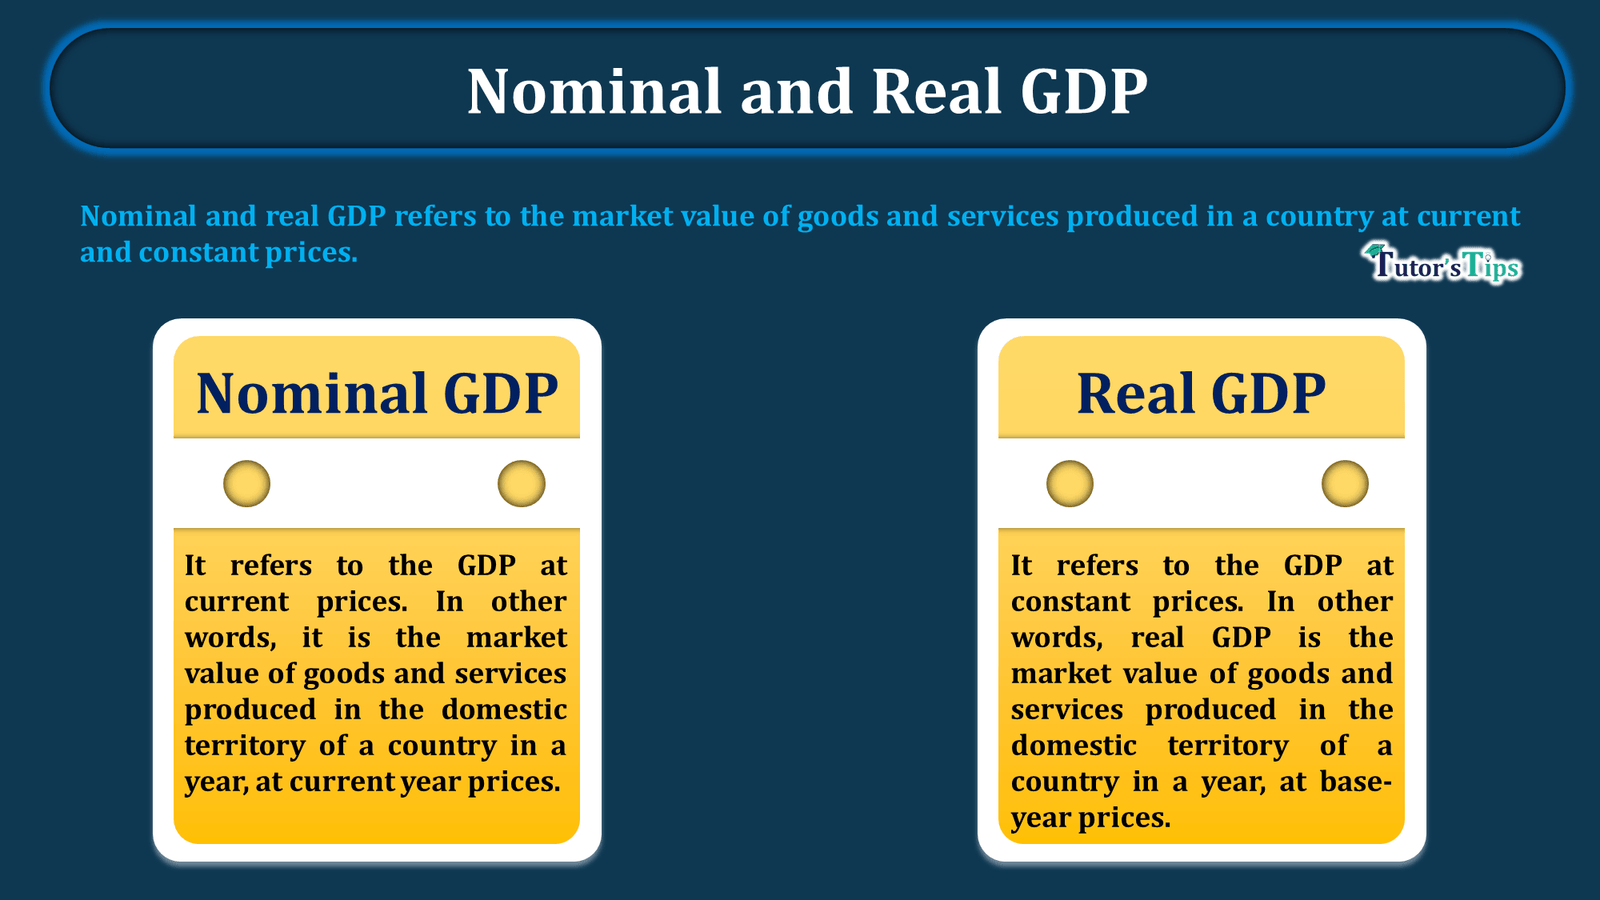
I spent four years working in macroeconomic data normalization for a regional policy institute. The job basically involved taking raw GDP prints from state-level agencies and figuring out whether an economy actually grew or just got more expensive. That distinction matters when you're trying to advise on budget allocations, and getting it wrong makes you look foolish very quickly. Nominal GDP is the raw, unadjusted dollar figure. It tells you what the total market value of all finished goods and services produced in a given period, measured in current prices. That's it. If prices doubled and output stayed flat, nominal GDP would double. It doesn't care about inflation. It's a head-count measure of economic activity in whatever money is circulating at the time. Real GDP strips out price changes. It measures output using constant prices from a base year, so you're looking at actual volume changes rather than price changes masquerading as growth. When the Bureau of Economic Analysis releases a quarterly GDP figure, the headline number is nominal. The real figure is what economists and policymakers actually care about. Not that they always agree on which deflator to use, but that's a separate headache.
Understanding Real And Nominal Gdp Through Calculation
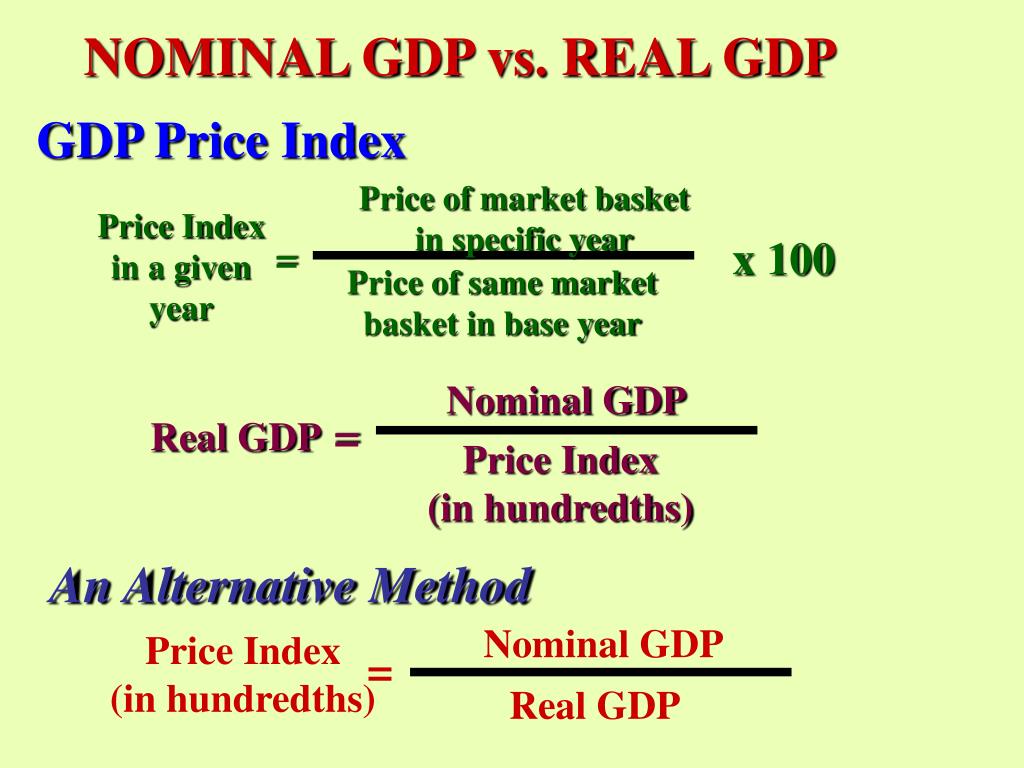
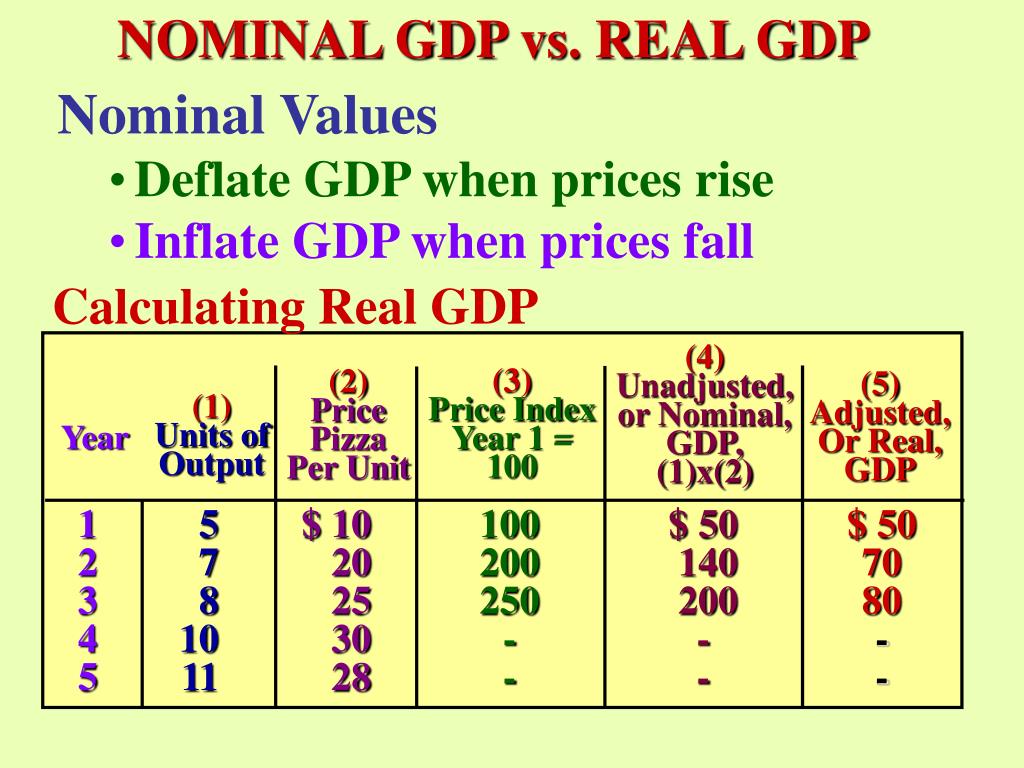
The calculation itself is straightforward. You take nominal GDP and divide it by the GDP deflator, then multiply by 100. The GDP deflator is an implicit price index that covers all domestically produced goods and services, not just a consumer basket like CPI. That's an important distinction because it includes capital goods, government purchases, and exports, which CPI misses entirely. Let me walk through a practical example. Say State X produced $50 billion in widget output last year at current prices, and the GDP deflator for that year reads 125 (with a base year of 100). You divide 50 billion by 1.25 and get 40 billion in real terms. The economy didn't grow at all in real terms last year despite what the nominal figure suggests. This happens more often than you'd think during high-inflation periods. The BEA updates the base year for real GDP calculations every few years through a technique called chain-weighting. Before 1996 they used fixed-base-year calculations, which introduced substitution bias. When relative prices change, people buy different things, and a fixed basket doesn't capture that. Chain-weighted GDP accounts for this by allowing the weights to shift each period. It's more accurate but also more computationally intensive, which was a real bottleneck when we were processing state-level data in the late 2000s.
Here's where beginners consistently trip up. They confuse the GDP deflator with the CPI and try to convert between them as if they're interchangeable. They're not. The CPI tracks a fixed basket of consumer goods. The GDP deflator covers everything produced domestically, including industrial equipment and military hardware. During the 2022 inflation spike, CPI jumped to around 9% while the GDP deflator hovered closer to 6%. If you used CPI to deflate nominal GDP, you'd get a different real GDP number than if you used the proper deflator, and the difference was meaningful when we were modeling fiscal impacts.
Get the Full Details
A Specific Problem I Encountered
One particular edge case comes to mind from my time at the institute. We were working on a cross-state comparison of manufacturing sector output, and the nominal GDP figures for two neighboring states looked nearly identical. The problem was that one state had been using a chain-weighted deflator while the other was still on a fixed-base calculation due to an outdated methodology. The nominal figures were comparable, but the real figures diverged by nearly eight percentage points because the deflators weren't aligned. The workaround was to manually reconstruct both series using the same BEA reference year deflator. It took about three weeks of data cleaning because the state-level agencies didn't publish their underlying deflator values in easily machine-readable formats. Some of it was embedded in PDF reports that required manual transcription. I ended up writing a small Python script to parse the tables and auto-align the years, which cut future processing time from roughly two days per state to maybe twenty minutes. The script wasn't elegant but it got the job done. Another practical issue that comes up frequently: seasonal adjustment. Nominal GDP is reported in current-dollar terms but isn't always seasonally adjusted. Real GDP usually is, because BEA applies seasonal adjustment to the real series after deflating. If you're comparing monthly or quarterly figures across different countries or agencies, you need to check whether seasonality has been removed. It's an easy thing to overlook and it will distort your analysis if you miss it.
When These Measures Break Down
Real GDP has well-known limitations that nobody talks about enough. It doesn't capture non-market production like household labor or underground economic activity. A stay-at-home parent raising children contributes zero to GDP, while the same care provided through a paid service adds to the total. This means GDP comparisons across countries with different social structures are imperfect. Germany and the United States might have similar GDP figures but vastly different levels of unpaid care work, and that gap won't show up in the data. It also doesn't account for quality improvements well. If a smartphone in 2024 costs the same as one in 2014 but has ten times the processing power, real GDP might understates the actual improvement in living standards. The BEA tries to address this through hedonic adjustments in some sectors, but the coverage is inconsistent. You'll notice the biggest gaps in technology and healthcare, where quality change is rapid and hard to measure. There's also the matter of intermediate goods. GDP only counts final goods and services to avoid double-counting. But when supply chains get long and fragmented, tracking what counts as "final" becomes murky. A car manufacturer buying steel, rubber, and microchips from different suppliers — only the final vehicle sale counts toward GDP. The intermediate transactions are implicit in the final price. This matters when you're trying to trace the geographic origin of value added, which is why trade data sometimes shows discrepancies that don't reconcile neatly.
If you're doing policy analysis, I'd recommend supplementing real GDP with the Personal Income and Spending data the BEA publishes alongside it. Real GDP tells you about production. Personal income tells you what people actually received, which is closer to the lived experience of economic growth. The divergence between the two has widened in recent years, and ignoring that gap leads to overly optimistic assessments of household welfare. The key takeaway is that nominal GDP gives you a snapshot of market activity in current dollars, while real GDP adjusts for price changes to show actual output growth. Both numbers are useful. The nominal figure matters for debt sustainability analysis and tax revenue projections. The real figure matters for understanding whether the economy is actually expanding. Using the wrong one for the wrong purpose produces misleading conclusions, and I've seen it happen repeatedly in policy discussions where people cite nominal growth rates when discussing purchasing power or living standards.