How I Handle Write-offs Without the Tax Man Knocking
Most people treat business expenses in real estate like a guessing game. They see a fancy dashboard from a property management platform and assume everything gets claimed. It doesn't work that way. I've spent fourteen years tracking this kind of thing across residential flips, multi-unit holds, and commercial subleases, and the ones who get burned aren't the ones who underreport — they're the ones who over-report and then realize their auditor flagged them at year-end. Here's the working process I use, the part nobody puts in the beginner videos. First, categorize everything by property, not by bank account. My accountant used to ask me why my "general misc expense" bucket was bigger than my actual rent line item. It wasn't a bucket problem. It was a filing problem. Once I started tagging every receipt to a specific Property ID at the point of capture, the whole audit trail became three clicks instead of a Sunday afternoon panic.
The Real Estate Business Expenses Framework I Actually Follow
The framework itself is straightforward. You separate operating expenses from capital expenditures, you map each one to the correct IRS line on Schedule E (or 1120-S if you're an LLC electing corporate treatment), and you retain proof of business purpose. The tricky part isn't the classification. It's the gray zone stuff that makes people second-guess themselves. Like the time I drove 47 miles to inspect a property that fell through at the last minute, and I had to justify that mileage as a business expense versus a personal outing. The workaround was simple: I kept a running log with the property address, the listing URL, and a one-line note about what I was looking for. That log has saved me through two audits. Another thing people miss is the 100% immediately deductible threshold. Under Section 179, equipment purchases up to a certain limit can be expensed in full. For 2024, that limit sits at $1,220,000 with a phase-out starting at $2,890,000 in total equipment spending. So a $15,000 HVAC unit for a rental property can often go straight to expense rather than getting depreciated over 27.5 years. The catch is it has to be qualifying equipment, not structural improvements. I learned that the hard way when I tried to expense a new roof. Roof replacement is a structural improvement, period. It goes on the depreciation schedule. The HVAC unit next to it? That was fine. Same year, same property, two very different treatment paths.
What Actually Counts and What Gets Rejected
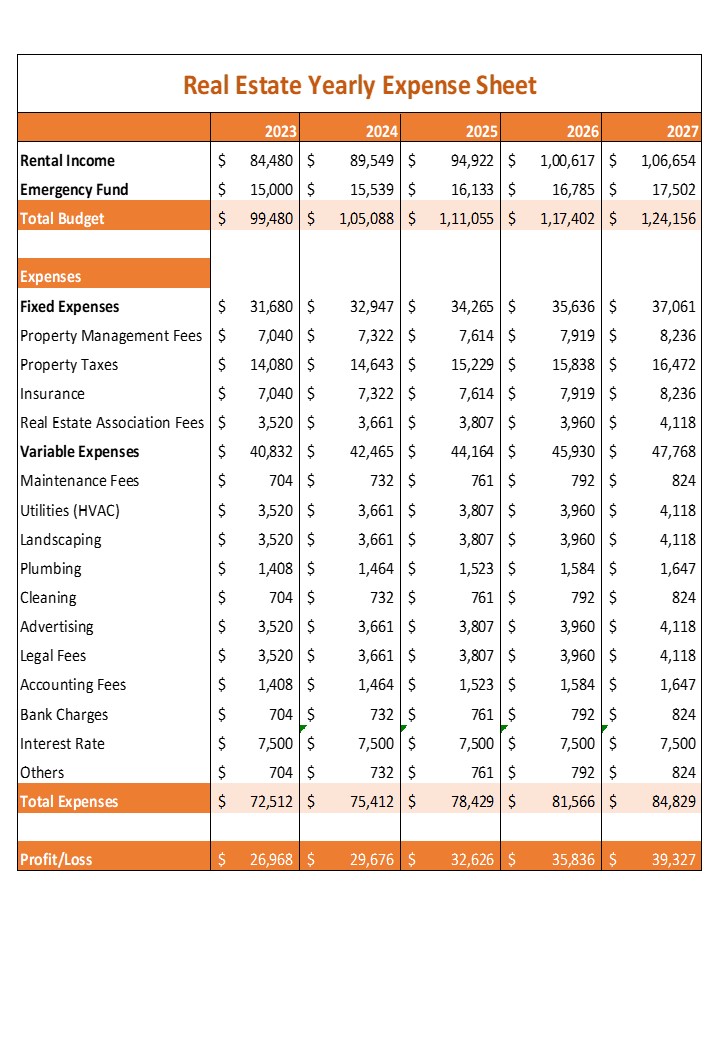
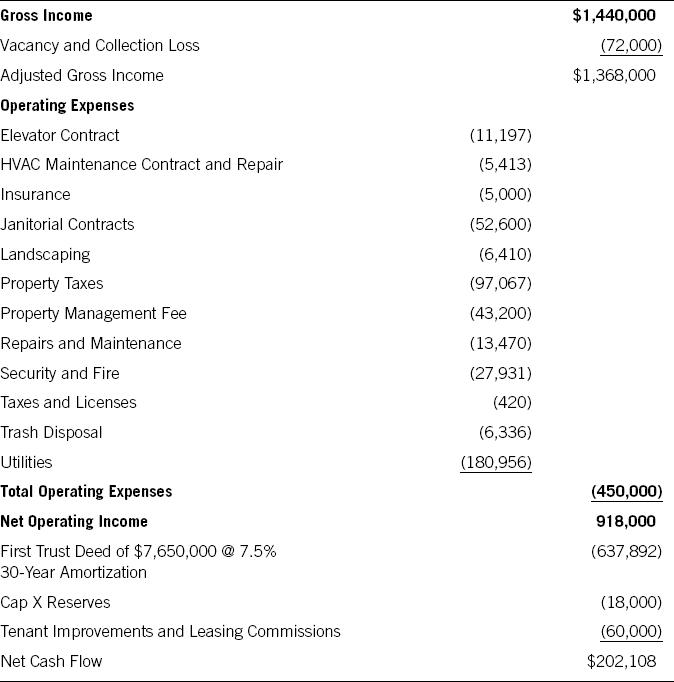
Operating expenses that are legitimate include property management fees, which typically run 8 to 12 percent of collected rent depending on your market. Repairs and maintenance, which covers things like fixing a leaky faucet or patching drywall. Advertising for vacant units. Utilities you pay directly. Property taxes and insurance premiums. Travel to inspect or manage a property — and I mean actual travel, not your daily commute to the office. Things that don't qualify are easier to list. Your principal residence mortgage interest isn't a business expense unless that home is actually generating rental income for the full year with no personal use. Vacations disguised as "property tours" will come back to haunt you. Capital improvements like adding a room, replacing flooring throughout, or installing a new fence — these add to the basis and get depreciated, not expensed. Depreciation recapture hits you at 25 percent when you sell, by the way, so planning matters.
Get the Full Details
The One Thing That Kills Most DIY Filers
It's commingling. Personal and business funds sitting in the same account, then trying to untangle them six months later. I watch this happen constantly. Someone buys groceries on a card they also use for property repairs, and suddenly they have no clean way to separate the two. The fix is to open a dedicated business checking account the week you start treating real estate as a business, not the week before tax season. If you're already commingled, you can still clean it up retroactively with bank statements and a spreadsheet. It takes about four hours for a moderate portfolio, maybe six if you're juggling multiple entities. Worth every minute. I use a combination of QuickBooks Self-Employed for the day-to-day and a custom Google Sheets tracker for the depreciation schedule. The spreadsheet is ugly but it does something QuickBooks never did for me: it projects the recapture liability so I'm not surprised when I sell. The software side handles receipt capture through mobile import and auto-categorizes most transactions within 90 percent accuracy. The other 10 percent is where you actually have to look at things. Don't skip it. There's a free download for a simplified expense tracker template I put together years ago, and you can find it on my site under the resources section. It's basic. It won't replace a CPA. But it'll keep you from losing receipts to a shoebox and having nothing to show an auditor.
Where This System Falls Apart
Be honest about the limits. If you're running more than five properties across multiple states, the manual tracking approach starts to strain. You'll need professional property management software with integrated accounting, or you need a CPA who actually understands real estate and not just general small business deductions. Also, this guidance assumes you're operating as a pass-through entity, which covers the vast majority of individual real estate investors. If you're structured as a C corporation, the rules change significantly and you should talk to a professional before applying anything I've written here to your own situation. The mileage deduction is another area where the system gets fragile. The standard rate changed to 65.5 cents per mile for 2024, up from 62.5 the year before. Every year it shifts slightly. If you're not tracking actual vehicle expenses alongside the mileage log, you're leaving money on the table or setting yourself up for a discrepancy. I switched to actual expense tracking for my main work vehicle a few years back because the math worked out better for high-mileage investors. Depending on your vehicle cost and depreciation, it can save you between $300 and $900 annually compared to the standard rate.
Bottom Line
Real estate business expenses aren't complicated when you treat them systematically from day one. The people who struggle are the ones who assume they can clean it up later. They can't. Not cleanly, not cheaply, and not without risking an audit flag. Tag receipts the moment you buy them. Separate accounts. Know the difference between a repair and an improvement. Keep a mileage log that actually matches your trips. And if you're ever unsure about a line item, document the uncertainty and move on — it's cheaper to have a question than to claim something wrong and explain it under scrutiny.