How a Real Estate Business Partner Actually Works in Practice
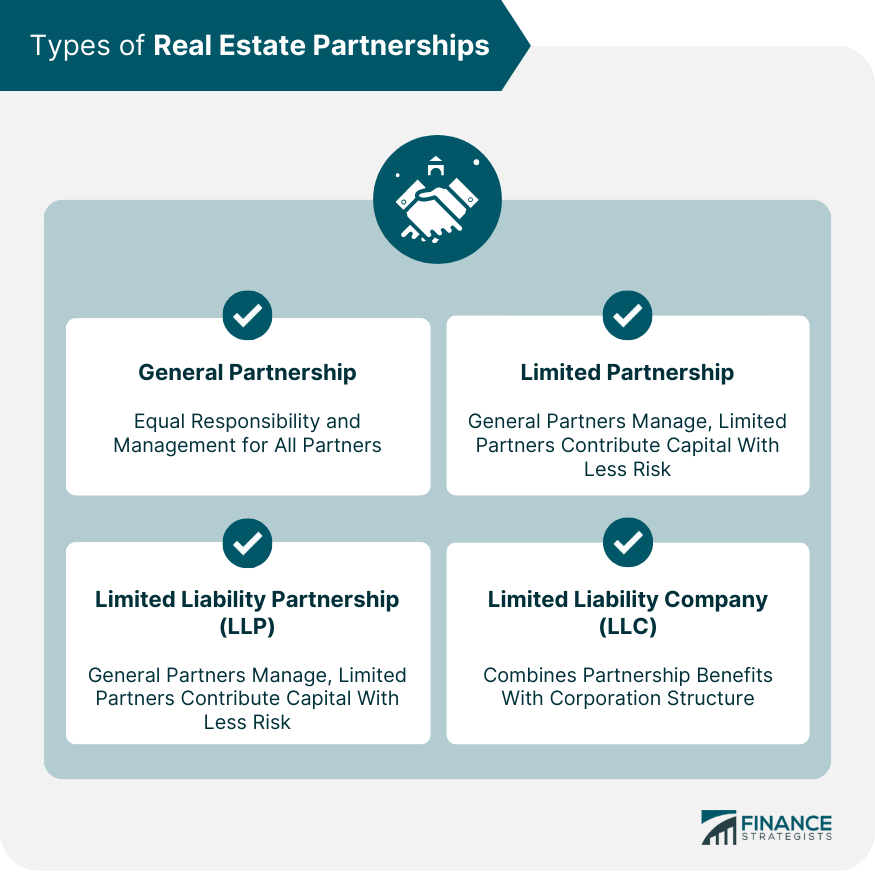
I've spent over a decade structuring deals and watching people blow them apart because they didn't understand who was doing what. The Real Estate Business Partner concept sounds straightforward—two or more people pooling resources to buy, manage, or develop property—but the devil is in the operating mechanics. Most beginners treat it like a handshake deal and that's exactly when things fall apart. A Real Estate Business Partner is any party you bring into a real estate transaction with defined roles and financial stakes. This can be a silent investor providing capital, a co-broking partner handling client acquisition, a joint venture collaborator on development, or even a strategic alliance with another agent to split commissions on larger deals. The term covers a wide range of arrangements, which is why so many people confuse the model and structure things poorly. The most common structure I see is the joint venture between an active operator and a passive capital partner. You handle acquisition, renovation, tenant placement, and day-to-day management. They bring the money. You split the profits according to whatever agreement you negotiate upfront. It sounds simple. It isn't always simple.
Structuring the Deal Before You Sign Anything
Here's where most people screw up. They meet someone at a networking event, shake hands, and start talking about buying property together without putting anything in writing. I had a partner come to me in 2019 after a joint venture dissolved after 14 months because his capital partner claimed he was owed 60% of the profits due to "being the money guy." There was no operating agreement. We spent six months in mediation trying to reconstruct intent from text messages and coffee shop conversations. That cost me roughly $18,000 in legal fees and the entire profit from the deal. Never skip the paperwork. Every joint venture should have a formal operating agreement covering capital contributions, profit distribution, decision-making authority, exit strategies, and dispute resolution. Specificity matters. Vague language like "fair share" or "equitable distribution" will be your undoing when emotions run high. Use percentages tied to actual dollar contributions. Define exactly what decisions require unanimous consent versus majority vote. Include a buyout clause with a predetermined valuation method so either party can exit cleanly. One thing nobody tells you: the partner who brings the money usually wants control. The partner doing the work usually wants autonomy. These are not inherently conflicting positions, but they require explicit negotiation. I've seen deals fall apart because the active partner felt micromanaged and the capital partner felt ignored. The fix is straightforward—write down each party's decision domains in the operating agreement before the deal closes. Active partner handles property selection, contractor management, and tenant decisions. Capital partner has veto rights on sale price and major refinancing only. Everyone knows their lane.
Commissions and Co-Broking Arrangements
If you're coming at this from the agent side, a Real Estate Business Partner arrangement often means co-brokering. You find a buyer who is already working with another agent in a different market. Instead of turning them away, you partner with that agent and split the commission. This is standard practice and it's how most agents scale beyond their immediate geographic area. The mechanics vary by market. In some MLS systems, you simply submit a cooperation offer and the selling agent handles the rest. In others, you need a formal referral agreement filed with both brokerages. I always recommend having a written co-brokerage agreement even when the MLS system makes it look optional. One of my agents once co-brokered a $2.3 million commercial deal through the MLS system without a written agreement. The other brokerage later claimed the commission wasn't properly registered and tried to claim half of it. We recovered it, but it took three weeks and a lot of phone calls that could have been avoided with a PDF attached to the listing. Commission splits are typically 50/50 between the cooperating brokers, but this is negotiable. If you're bringing a ready, willing, and able buyer who's already under contract with another agent, you might negotiate for 60/40 in your favor since you're closing the deal. Conversely, if the other agent already has the buyer pre-approved and ready to move, they may push for the same terms. The market dictates the split, not some rigid rule.
Get the Full Details

Common Pitfalls That Kill Joint Ventures
First pitfall: mixing personal and business finances. I've seen partners commingle personal funds with venture capital because "it's just us, we trust each other." Six months later when a distribution check needs to be cut, there's no clear paper trail and the IRS has questions. Open a separate business bank account for every joint venture. Every contribution goes in, every distribution comes out. Simple. Clean. Defensible. Second pitfall: undefined roles. When both partners think they're making all the decisions, nothing gets done. When neither partner thinks they're responsible for anything, the property deteriorates. I once managed a multifamily property where both partners had equal signing authority on vendor contracts. The result was two competing proposals for the same roof repair, two invoices sent to the same vendor, and a $47,000 overpayment that took eight months to recover. One clear decision-maker per functional area solves this. Property management under one partner. Financial decisions under the other. Legal matters require both signatures. Write it down. Third pitfall: ignoring the exit strategy. Everyone enters a joint venture thinking it will last forever. The market doesn't care about your optimism. If one partner wants out after two years and the other wants to hold for ten, you need a predetermined mechanism. Right of first refusal is the standard approach. The staying partner gets the option to buy out the departing partner's interest at a formula-driven price before offering it to external parties. The formula should be based on a percentage of gross revenue, appraised value, or a combination—not just "what we agreed to back when."
Tax Implications You Need to Consider
Joint ventures in real estate are typically taxed as partnerships unless you structure them as LLCs electing S-corp status or separate entities. This means passing through income to each partner's personal tax return. You'll receive a Schedule K-1 at year end, not a W-2. This has significant implications for self-employment tax and estimated payments. One of my clients discovered this the hard way when he treated his joint venture income like regular salary and underpaid his quarterly estimates by roughly $12,000. The penalty was modest but the lesson stuck. If you're a Real Estate Business Partner bringing capital into a deal, your share of profits may be subject to self-employment tax depending on your level of participation. Passive investors generally avoid this. Active participants do not. This distinction matters more than most agents explain to their investor partners. I always recommend a quick consultation with a CPA who specializes in real estate before structuring any venture. The $500 investment saves thousands in potential penalties.
When the Partnership Model Doesn't Work
Let me be clear about where this approach fails. Joint ventures require trust, clear communication, and compatible timelines. If you're looking for a hands-off investment with guaranteed returns, a REIT or private fund is the right vehicle. If you need complete control over every decision, operate alone. The partnership model sits in the middle—it offers scale and leverage but demands ongoing relationship management. I've watched perfectly good deals fail because two competent professionals couldn't agree on paint colors for a rental unit. That's not a partnership problem. That's a selection problem. Another scenario where partnerships break down is in volatile markets. When property values swing sharply, partners with different risk tolerances will have different opinions on whether to sell, refinance, or hold. A partner who entered expecting steady appreciation may panic during a correction and demand a fire sale. The other partner who planned to hold for cash flow may see the dip as an opportunity. Without a pre-agreed framework for handling market events, this becomes a personal conflict rather than a business decision.
A Practical Framework That Has Worked for Me
Here's the approach I use with every new partner. First, I draft a one-page term sheet before any money changes hands. It covers contribution amounts, ownership percentages, decision-making authority, profit distribution schedule, and exit provisions. We review it together, negotiate line by line, and sign it. Only then do we begin due diligence on any specific property. Second, I require an operating agreement within 30 days of the term sheet execution. This is the detailed document that expands every point from the term sheet into enforceable contract language. I use a real estate attorney for this. The cost ranges from $2,000 to $4,000 depending on complexity. It is not an expense to minimize. It is an investment that prevents six-figure disputes. Third, I schedule quarterly business reviews with every partner, even if we only have one active deal. These are brief meetings—30 minutes, agenda-driven, focused on financial performance and upcoming decisions. One of my partners almost missed a critical property tax appeal deadline because we hadn't reviewed the calendar in nine months. That appeal would have saved approximately $34,000 in annual taxes. Quarterly check-ins prevent that kind of oversight.
The Real Estate Business Partner model is one of the most effective ways to scale a real estate operation, but it only works when treated as a formal business arrangement rather than a casual collaboration. Get the structure right from day one. Everything else follows from that foundation.