What Actually Goes Into a Real Estate Business Plan
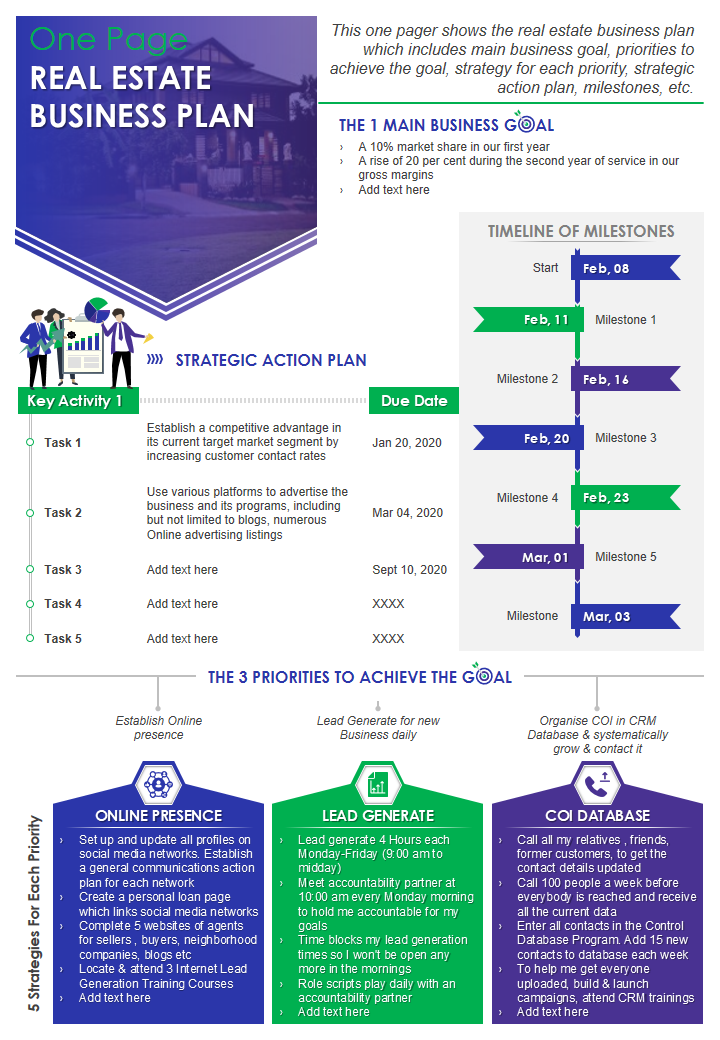
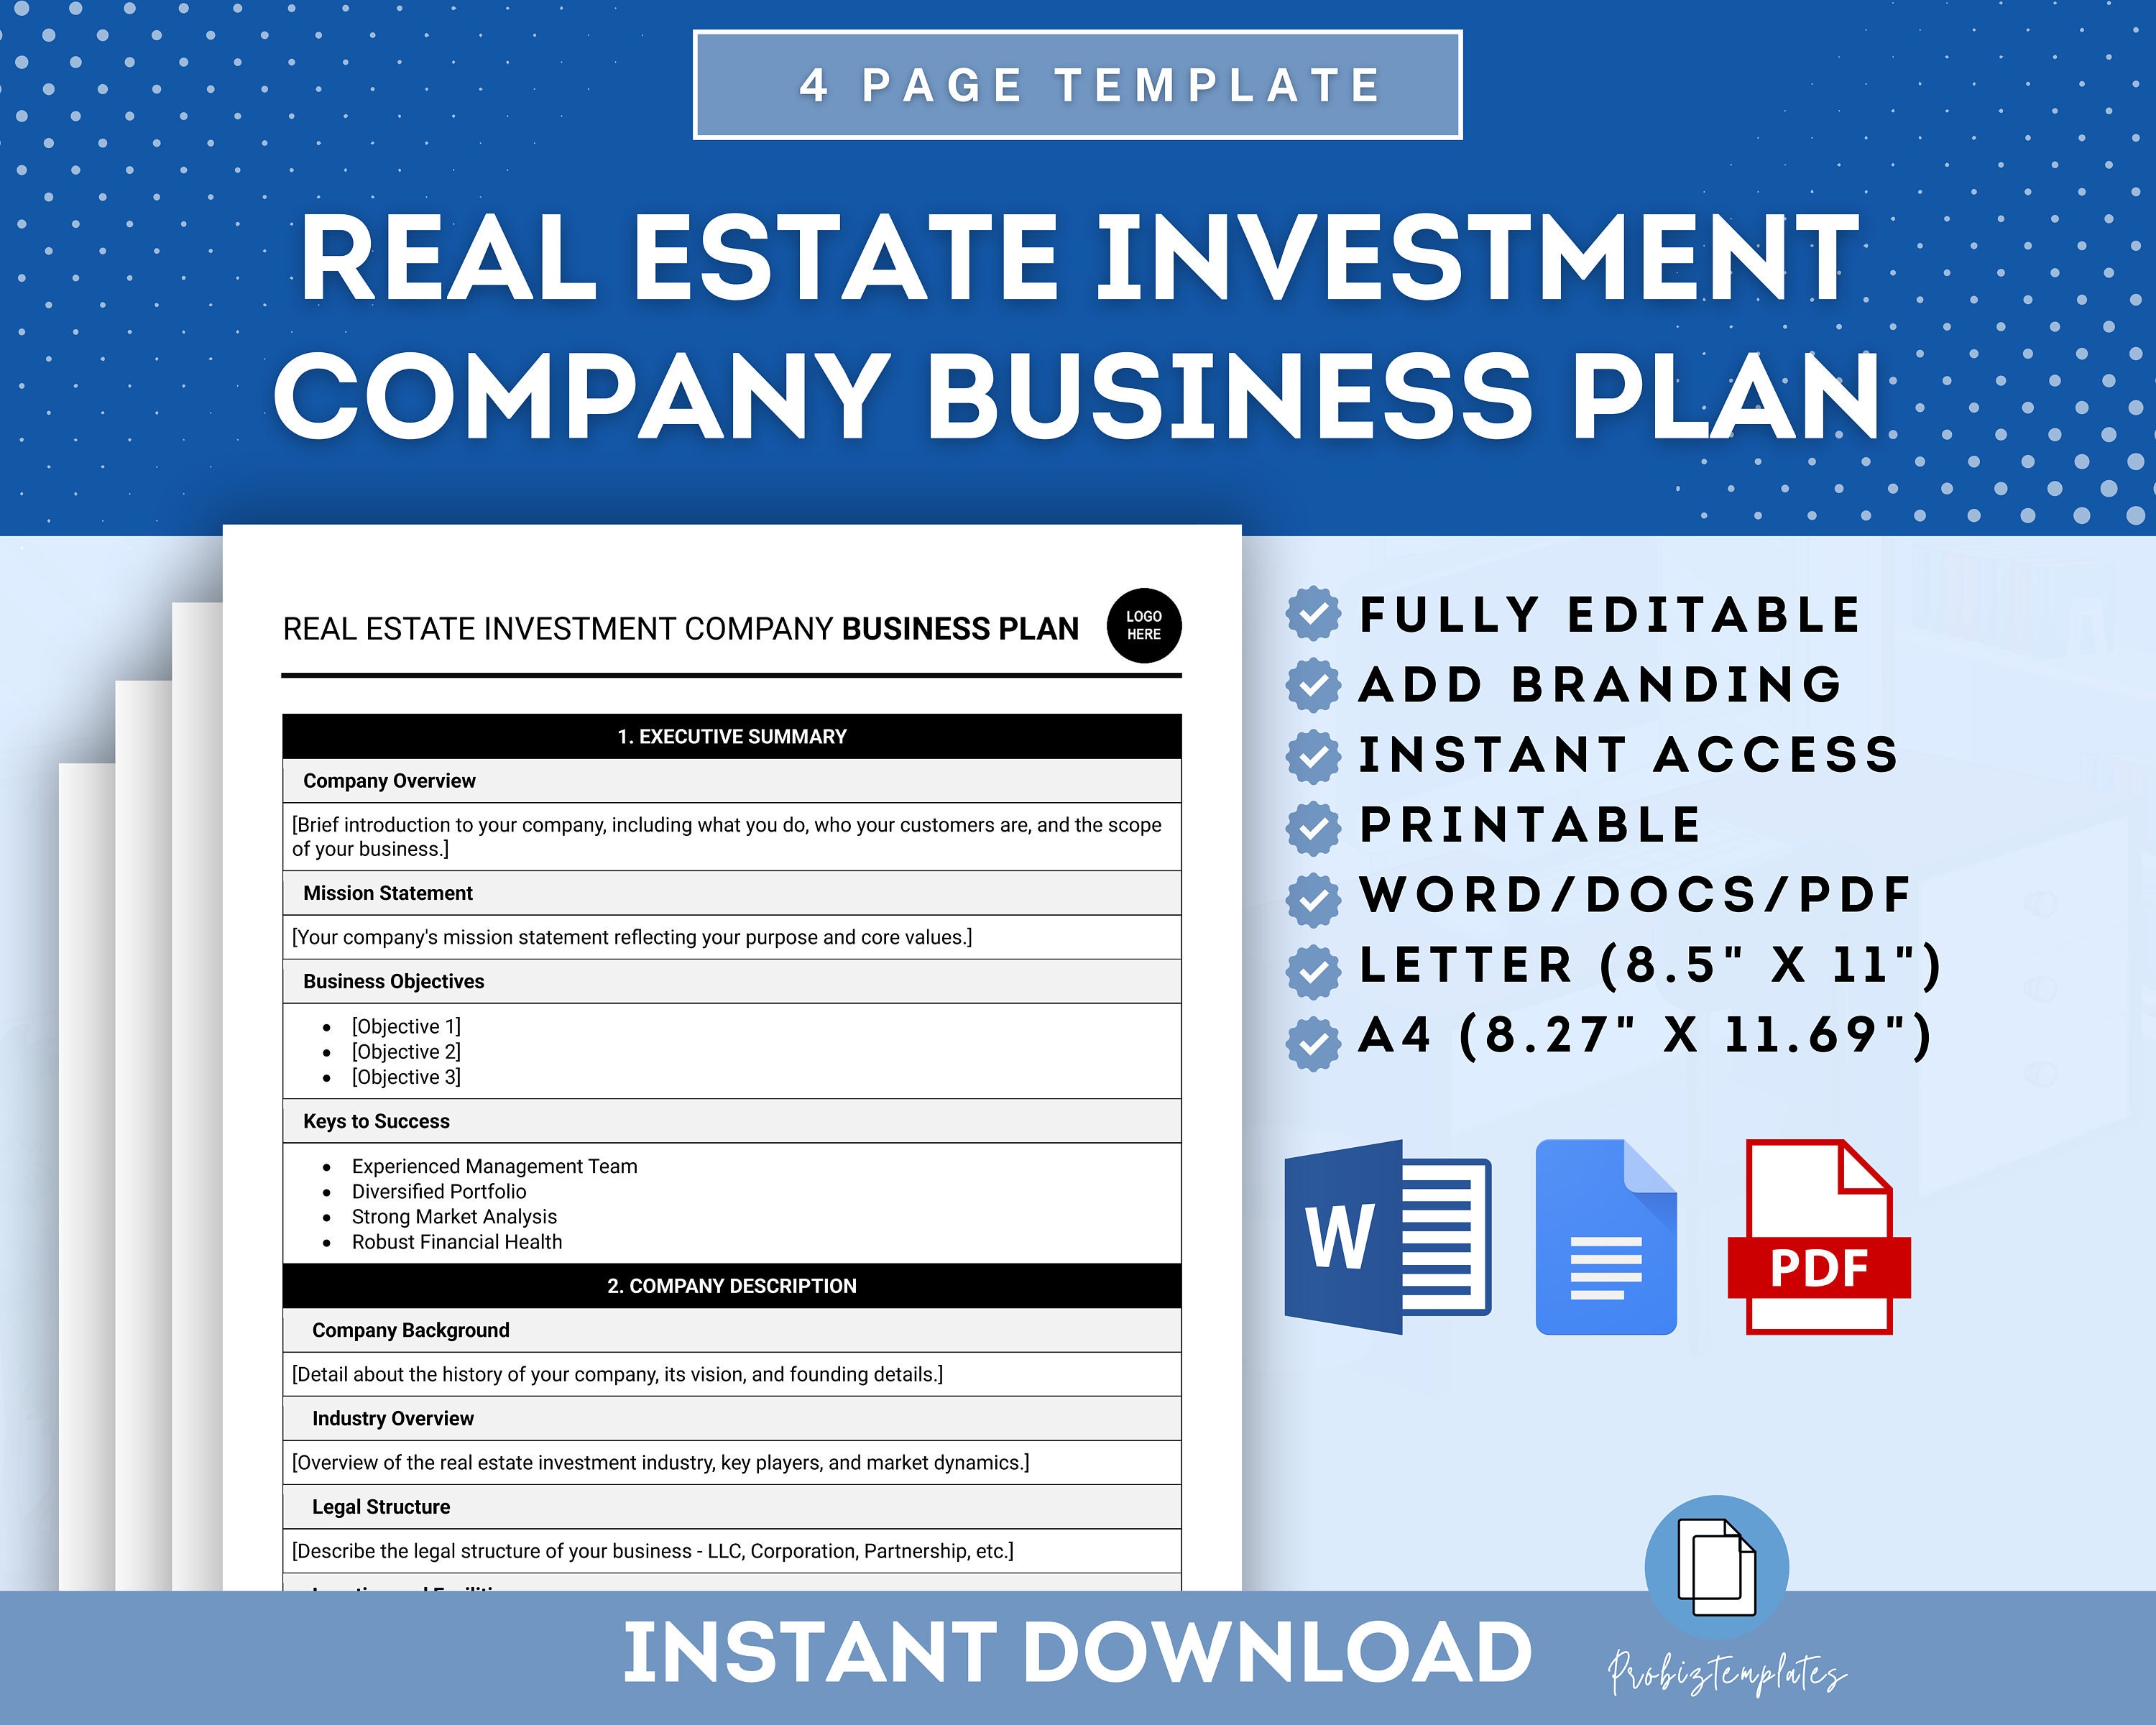
A real estate business plan isn't some polished deck you send to investors and hope for the best. It's the document that forces you to confront whether your deal structure is viable before you put any money on the line. I've seen people skip this step more often than not, and the ones who do tend to discover their financing gaps at closing instead of on paper where it costs them nothing. The core sections are straightforward enough: executive summary, market analysis, property overview, operations plan, marketing strategy, financial projections, and funding requirements. But the order matters less than actually filling in the numbers with some realism. Most template-driven plans fail because the revenue assumptions are based on optimistic market comparables that don't apply to the actual asset being evaluated.
Where to Find Real Estate Business Plan Examples
SBA.gov has a solid template section for small business plans that translate directly to real estate if you adjust the language. SCORE.org offers free downloadable examples across various real estate niches. BiggerPockets publishes case-study plans from active investors that are worth studying for their approach to pro forma presentation. The U.S. Small Business Administration also maintains a library of sample plans that cover residential, commercial, and property management models. There are also industry-specific templates from NAIOP and ICSC if you're working in commercial real estate and need the right terminology. Here's what most people miss when they start pulling these together. They copy a sample plan structure word for word and then try to plug their own numbers into someone else's assumptions. That doesn't work because the market dynamics, financing terms, and operational costs for a multifamily in Austin look completely different from a retail space in Columbus. The example is useful for understanding format and section depth, not as a blueprint for your actual projections. I once spent three weeks building a detailed pro forma for a small multifamily acquisition based on a Commercial Mortgage Bankers Association template I found online. The cap rate assumptions were pulled from a 2019 report when the market was fundamentally different. By the time my lender ran the underwriting independently, they had cut my loan amount by eighteen percent because their comparable data showed the subject property was positioned incorrectly in the submarket. The example had looked legitimate. It just wasn't current.
How to Build One That Actually Holds Up
Start with your source data before you open any template. Pull the latest market rent rolls from CoStar or even local listings scraped from Zillow and Apartments.com. Get your operating expense ratios from actual properties in the same trade area, not from textbooks. You need vacancy rates that reflect the current quarter, not the five-year average. A property in a transitioning neighborhood might show a historical vacancy of eight percent but be running at fourteen percent right now. Plugging in eight will make your plan look fine and then fall apart when you're collecting checks. The financial section is where plans get constructed to please, not to inform. I see it constantly. Revenue grows at five percent year over year while expenses only increase at three percent. That smooth curve assumes nothing breaks, nothing vacant, and no major capital expenditure hits unexpectedly. In reality, a water heater fails in year two, the roof needs patching in year three, and one of your tenants breaks their lease six months in. Your plan should account for these, or at minimum note them as risk factors that could erode your returns. Build your pro forma in a spreadsheet with three scenarios: base, optimistic, and stress. Base should reflect what you expect to happen with reasonable diligence. Optimistic can show what happens if everything goes well, which is useful when you're presenting to partners. Stress needs to show what happens when vacancy hits twenty percent and capex comes in twenty percent above budget. If your deal still works in stress mode, you have something worth pursuing. If it only works in base mode, you're probably taking on more risk than you realize.
Get the Full Details

Common Structural Mistakes
One recurring error is mixing commercial and residential approaches in the same document. A commercial property plan emphasizes tenant creditworthiness, lease structures, and long-term commitments. A residential plan focuses on occupancy cycles, turnover costs, and shorter renewal windows. Combining them without clear separation confuses lenders and makes your financials look amateurish. Another is the executive summary problem. People write it last but it's the only section some readers actually see. A weak executive summary that reads like a table of contents doesn't help anyone. It should state clearly what the asset is, where it is, what the strategy is, and what the expected return is, all in under four paragraphs. If you can't summarize that concisely, you probably don't understand your own deal well enough yet. Market analysis sections often become generic. Copy-pasting demographic data from the Census Bureau without tying it back to your specific submarket or property type adds bulk but no value. Lenders and partners want to know why this location, why this asset class, and why now. Ground your analysis in micro-market conditions rather than city-wide statistics.
What to Include and What to Leave Out
Your exit strategy deserves more than a single sentence. If you're buying a value-add property, explain whether you're holding for cash flow, refinancing within three to five years, or flipping after renovations. Each path has different financing implications and affects how aggressive your acquisition price can be. A flip strategy requires a different budget timeline and cost structure than a hold-and-refinance approach. Don't include irrelevant details about your personal background unless you're seeking partnership equity. The plan should focus on the property and the numbers. Personal investment history belongs in a separate investor questionnaire, not in the business plan itself. This keeps the document tight and forces you to prove the deal on its own merits. Operations sections are frequently underdeveloped. If you're self-managing, list your day-to-day responsibilities. If you're using a property management company, include their fee structure and service scope. Maintenance response times, vendor relationships, and tenant placement processes are all operational details that affect your actual income and expenses. Skipping them makes your plan feel theoretical rather than grounded in how the property will actually run.
When a Business Plan Won't Save You
A detailed plan won't compensate for a bad deal. I've reviewed business plans that were meticulously prepared, professionally formatted, and filled with careful analysis, only to have the underlying acquisition lose money from day one because the seller was overpricing the property relative to its income potential. No amount of plan polish changes that outcome. The document is a tool for thinking through your strategy, not a shield against poor underwriting. Plans also become stale quickly. Market conditions shift, interest rates move, and new supply enters submarkets. A plan built in January may not be relevant by September if the Fed shifts policy or a new apartment complex breaks ground two blocks away. Use your plan as a living document and update key assumptions every quarter, especially if you're actively managing the asset toward your projected returns.

Practical Steps to Get Started
Pick one property you're currently evaluating. Don't build a plan for a hypothetical opportunity. Write the plan for the deal you're actually considering so the exercise has immediate relevance. Gather your purchase contract, any property condition reports, preliminary rent comparisons, and local tax data. Open a spreadsheet and lay out income and expenses line by line before adding any formulas. Understanding each cost category manually first prevents you from building a plan that does the math correctly while resting on flawed inputs. Run your numbers against at least two comparable properties that have actually sold recently. Not listed, sold. Asking prices tell you what sellers hope. Closed prices tell you what buyers agreed to pay. Use the sold data to validate your acquisition price assumption. If your plan shows a thirty percent return but comparable sales suggest the price is fifteen percent above market, your return assumption is inflated, not your expenses. Get the plan reviewed by someone who has actually underwritten deals in your market. Not a mentor who talks about real estate but one who has gone through lending and closing processes in the last two years. Their feedback will likely catch gaps in your logic that you won't see because you've been looking at the same numbers too long. This review step alone usually catches the kind of oversights that become expensive later.