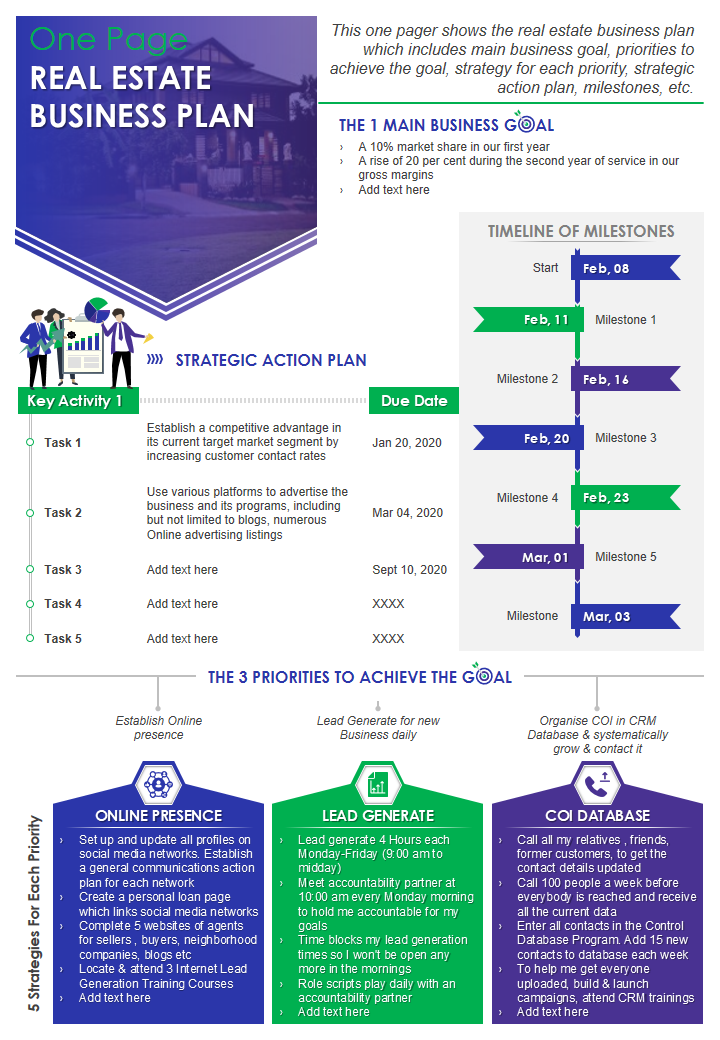
Writing a real estate business plan doesn't require five hundred pages.
The version I actually use is maybe twenty-five pages long, and it lives in Google Sheets rather than Word. Most people mess this up by writing a generic plan that would work for a lemonade stand if you swap out the cup for a key fob. I built mine when I was buying my second rental property and needed to convince a lender that I wasn't just going to flip houses on a dare. The hard part isn't the document itself. It's figuring out which parts lenders and partners will actually read before they make a decision on your money. Everything else is paperwork theater.
Real Estate Business Plan Outline
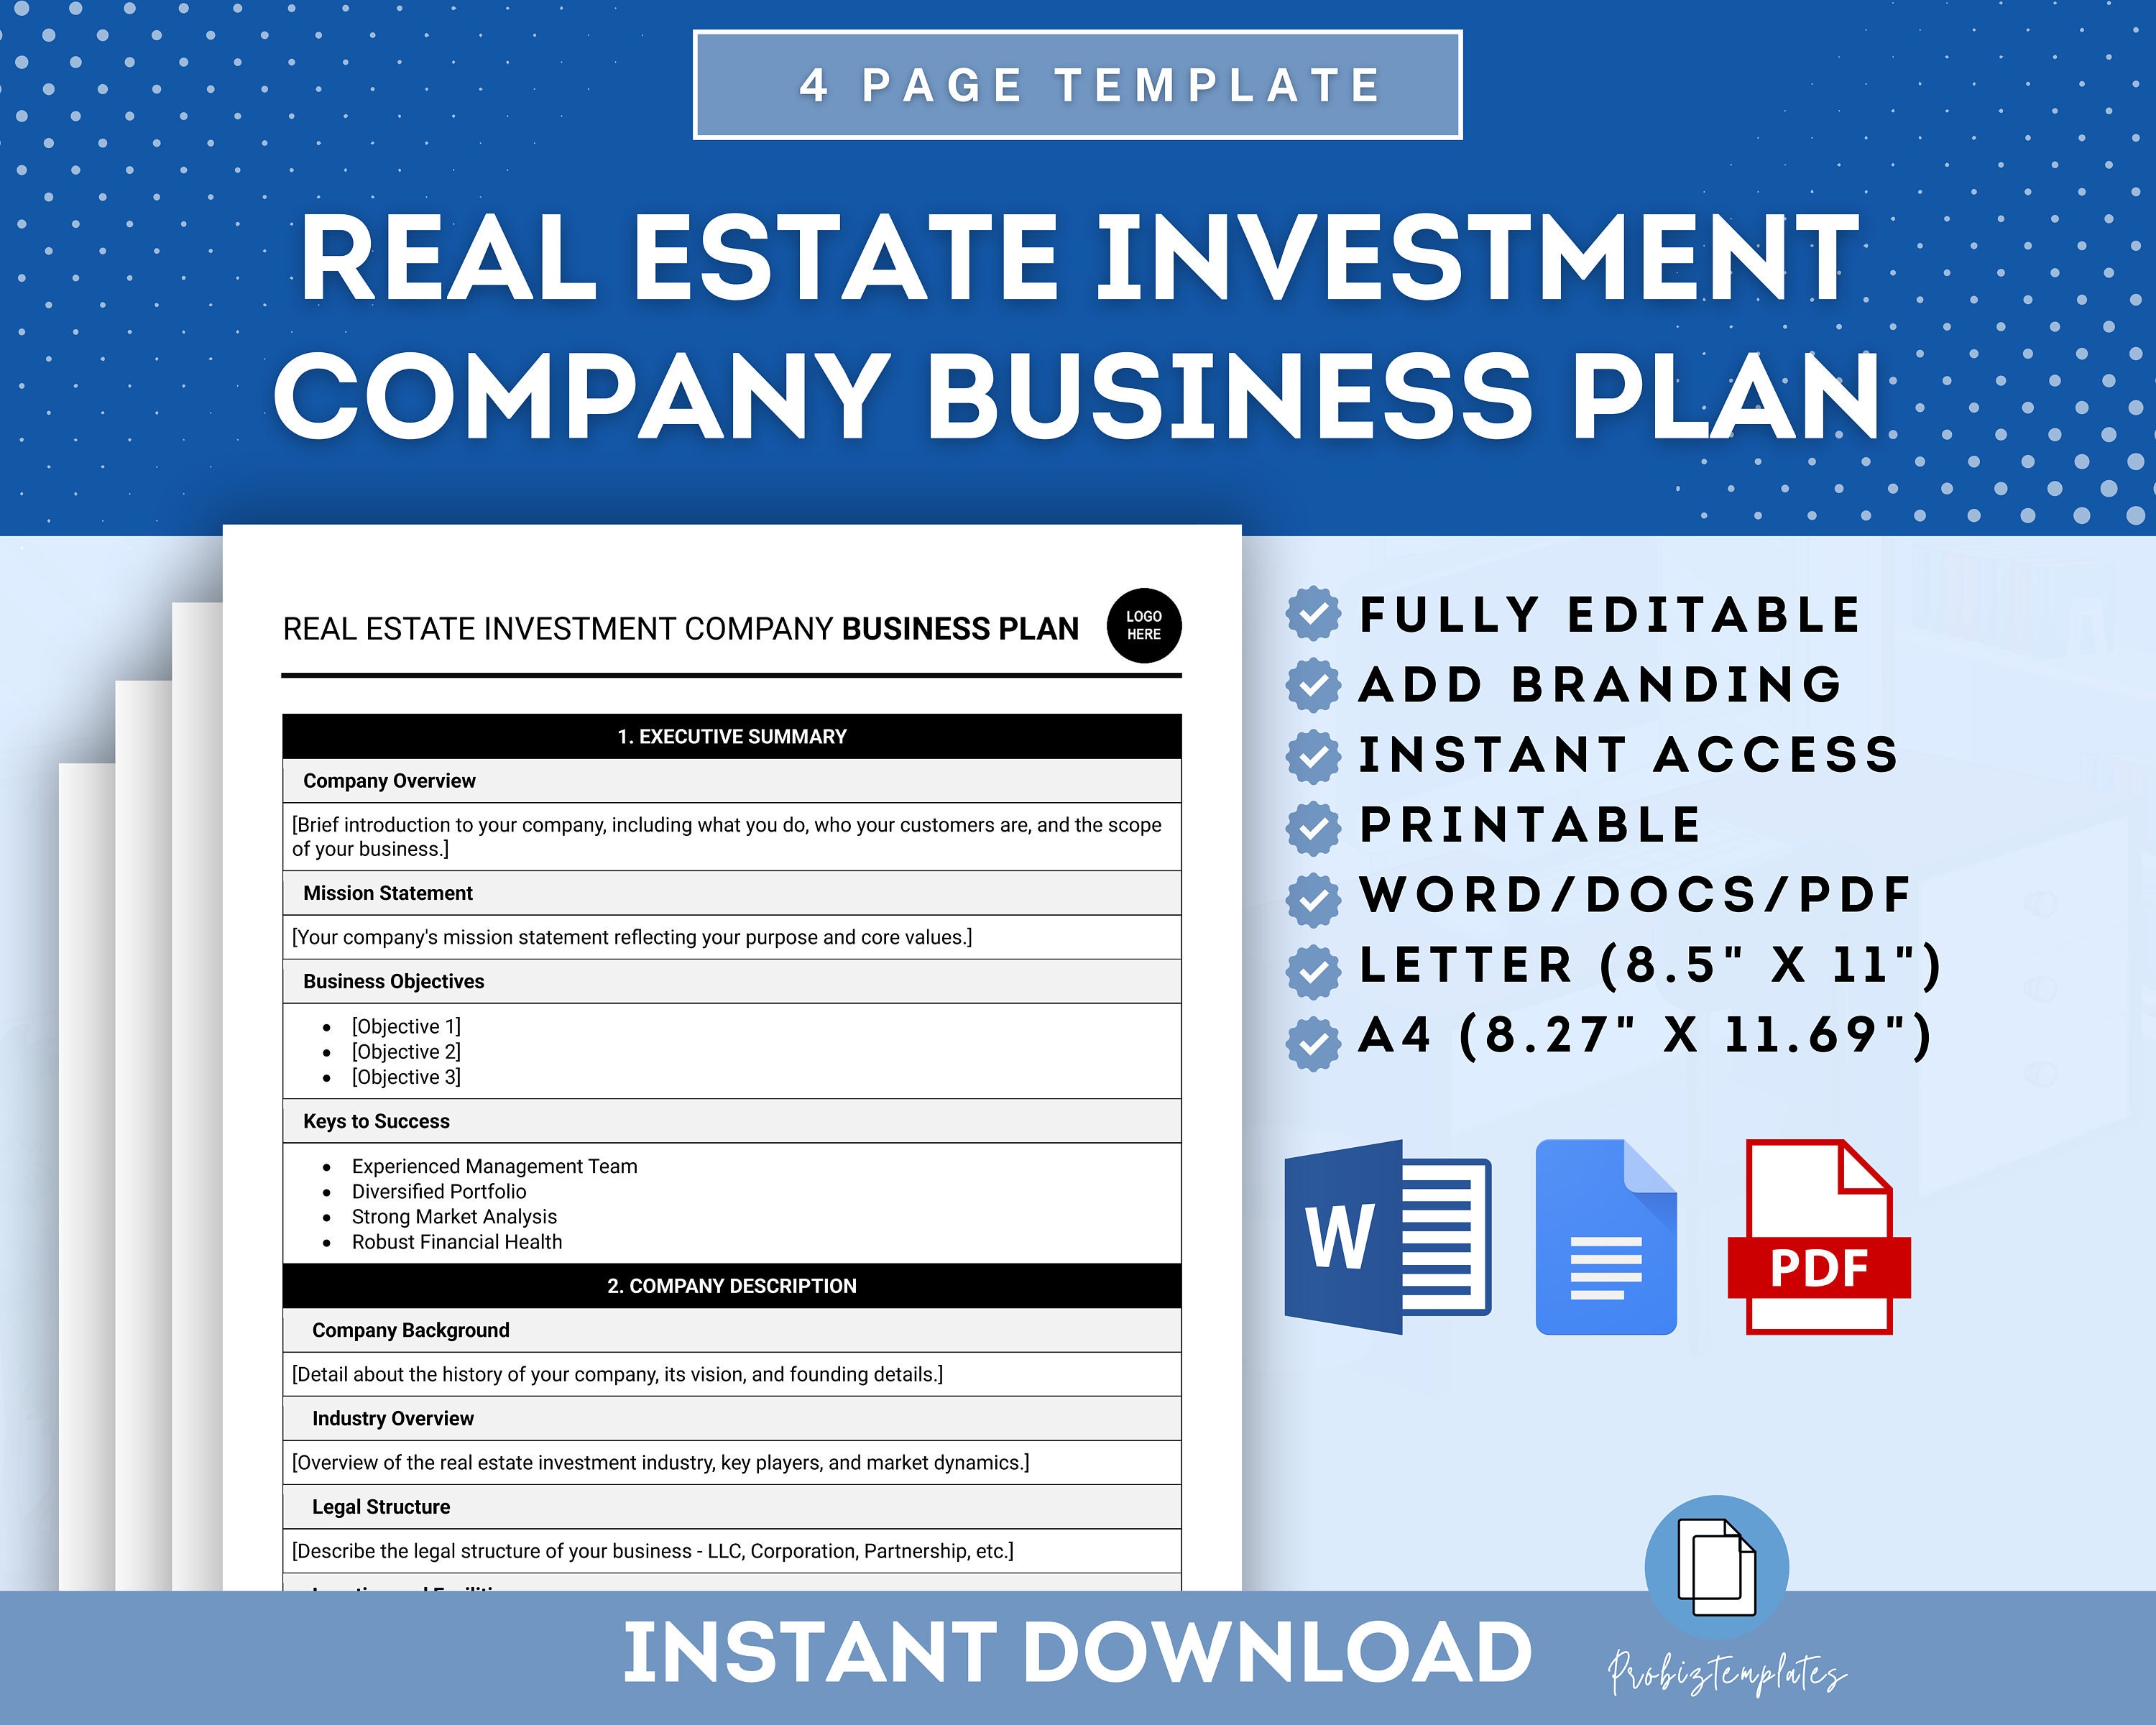
Here's the structure I use and recommend. It covers what investors and lenders need without padding every section to hit an arbitrary page count. Executive Summary: One page. Market, strategy, financial ask. If they don't get the point by page one, they won't read the next ten. Company Overview: Legal structure, ownership split, years in operation. Keep it dry. Lenders know what an LLC is.
Market Analysis: This is where most plans fall apart. Don't paste national statistics. Cite submarket data. Talk about your specific zip code, vacancy rates over the last three years, recent sales comps, and what's actually happening with local employment drivers. If you're in a secondary market, show why you picked it. I spent six months looking at Denver suburbs because the primary markets were mathematically impossible, and the plan had to reflect that honestly or I would have gotten blindsided later. Property Description or Portfolio: Address, unit mix, square footage, condition, current rent rolls. If you're pre-acquisition, describe the target property type and criteria instead. Operational Plan: How you'll acquire, manage, and dispose of properties. Self-manage or third-party management? Vendors, maintenance reserves, screening process. The operational details separate people who talk about real estate from people who actually run it.
Get the Full Details
Marketing and Leasing Strategy: Where your tenants or buyers come from. Online listings, direct mail, wholesaler networks, off-market sourcing. If you're doing flips, explain your disposition channels. Management Team: Who's doing what. If you're a solo operator with no track record, say so and explain how you're compensating for it through advisors or partners. Hiding that gap makes things worse. Financial Projections: Three to five years. Revenue, expenses, NOI, cash flow, cap rate assumptions, exit strategy. I use conservative underwriting — meaning I push vacancy rates up 100 basis points and CapEx reserves higher than the market standard. It's easier to look like a hero later than it is to explain why you blew through your reserves in year one.
Funding Request and Use of Proceeds: How much you need, what form it takes, where it goes. Be specific. "Working capital" means nothing to a lender. "10% contingency reserve for immediate roof and HVAC replacements on two targets" means something. Risk Analysis: What could go wrong and what you'll do about it. Interest rate increases, tenant defaults, extended vacancy, unexpected environmental remediation. I once had a lender call me out for omitting mold remediation costs in a 1970s-era multifamily purchase. We'd found black mold behind drywall during inspections on three separate deals that year. Adding a line item for $15,000 per unit in remediation reserves changed the conversation entirely. That was a real edge case, and the workaround was just admitting what the market already told me through repeated experience. Appendix: Resumes, credit reports, rent rolls, comps, survey data, letters of intent. Keep it organized. A disorganized appendix looks like disorganized operations.
The order above isn't sacred. I've flipped sections depending on whether I'm presenting to a hard money lender or a private equity group. BRRRR-focused lenders want to see the refinance exit clearly in the financials. Syndicators want the marketing and sourcing strategy upfront because that's their primary risk. One counter-intuitive thing I learned the hard way: your biggest numbers should look smaller than they are, not bigger. Inflated rent comps and understated operating expenses are the easiest ways to get a deal killed. Underwrite to the worst month of the worst year, not the peak. I had a partner who inflated rents by 8% across the board on a fourplex in Columbus. The lender pulled the loan within forty-eight hours after running their own comps. He lost his deposit because he couldn't prove he was serious. We reunderwrote at 3% above market and closed three weeks later. The spread between those two approaches was the difference between a funded deal and a lawsuit. Another nuance that beginners miss: the sensitivity table. Add a simple grid showing how your cash flow changes if vacancy goes up 5%, if interest rates rise 200 basis points, or if a major expense hits in year two. It takes ten minutes to build in Excel and it answers the question every investor is actually thinking about. Most plans skip it entirely because people assume it signals weakness. It doesn't. It signals that you've already thought about the downside.
There are real limitations to this approach. A lean business plan won't replace a formal feasibility study for institutional lenders. If you're seeking $10 million in debt, you're getting audited regardless of how clean your document is. The outline above works well for small to mid-scale acquisitions — up to roughly $5 million in total project cost. Beyond that, the financial section needs independent appraisal data, Phase I environmental assessments, and legal opinions that no template can provide. If you're operating in a niche market like self-storage or manufactured housing, the standard outline needs adjustment. Those asset classes have different underwriting metrics. Occupancy isn't the same as effective occupancy. Trailer park lots carry different risk profiles than apartment units. A generic plan loses credibility fast in specialized verticals. The document is a living thing. I update mine every quarter and whenever a major market shift happens. Interest rates, insurance costs, and local zoning changes render old projections useless within eighteen months in most markets. Keeping it static makes it worthless rather than useful.
If you want a working template, the structure above can be copied directly into a spreadsheet. The financial section in particular benefits from being formula-driven rather than text-driven. Every number should trace back to an assumption you can defend. If you can't explain where a number came from, you shouldn't include it.