Getting a Comparative Market Analysis Right Without Losing Your Mind
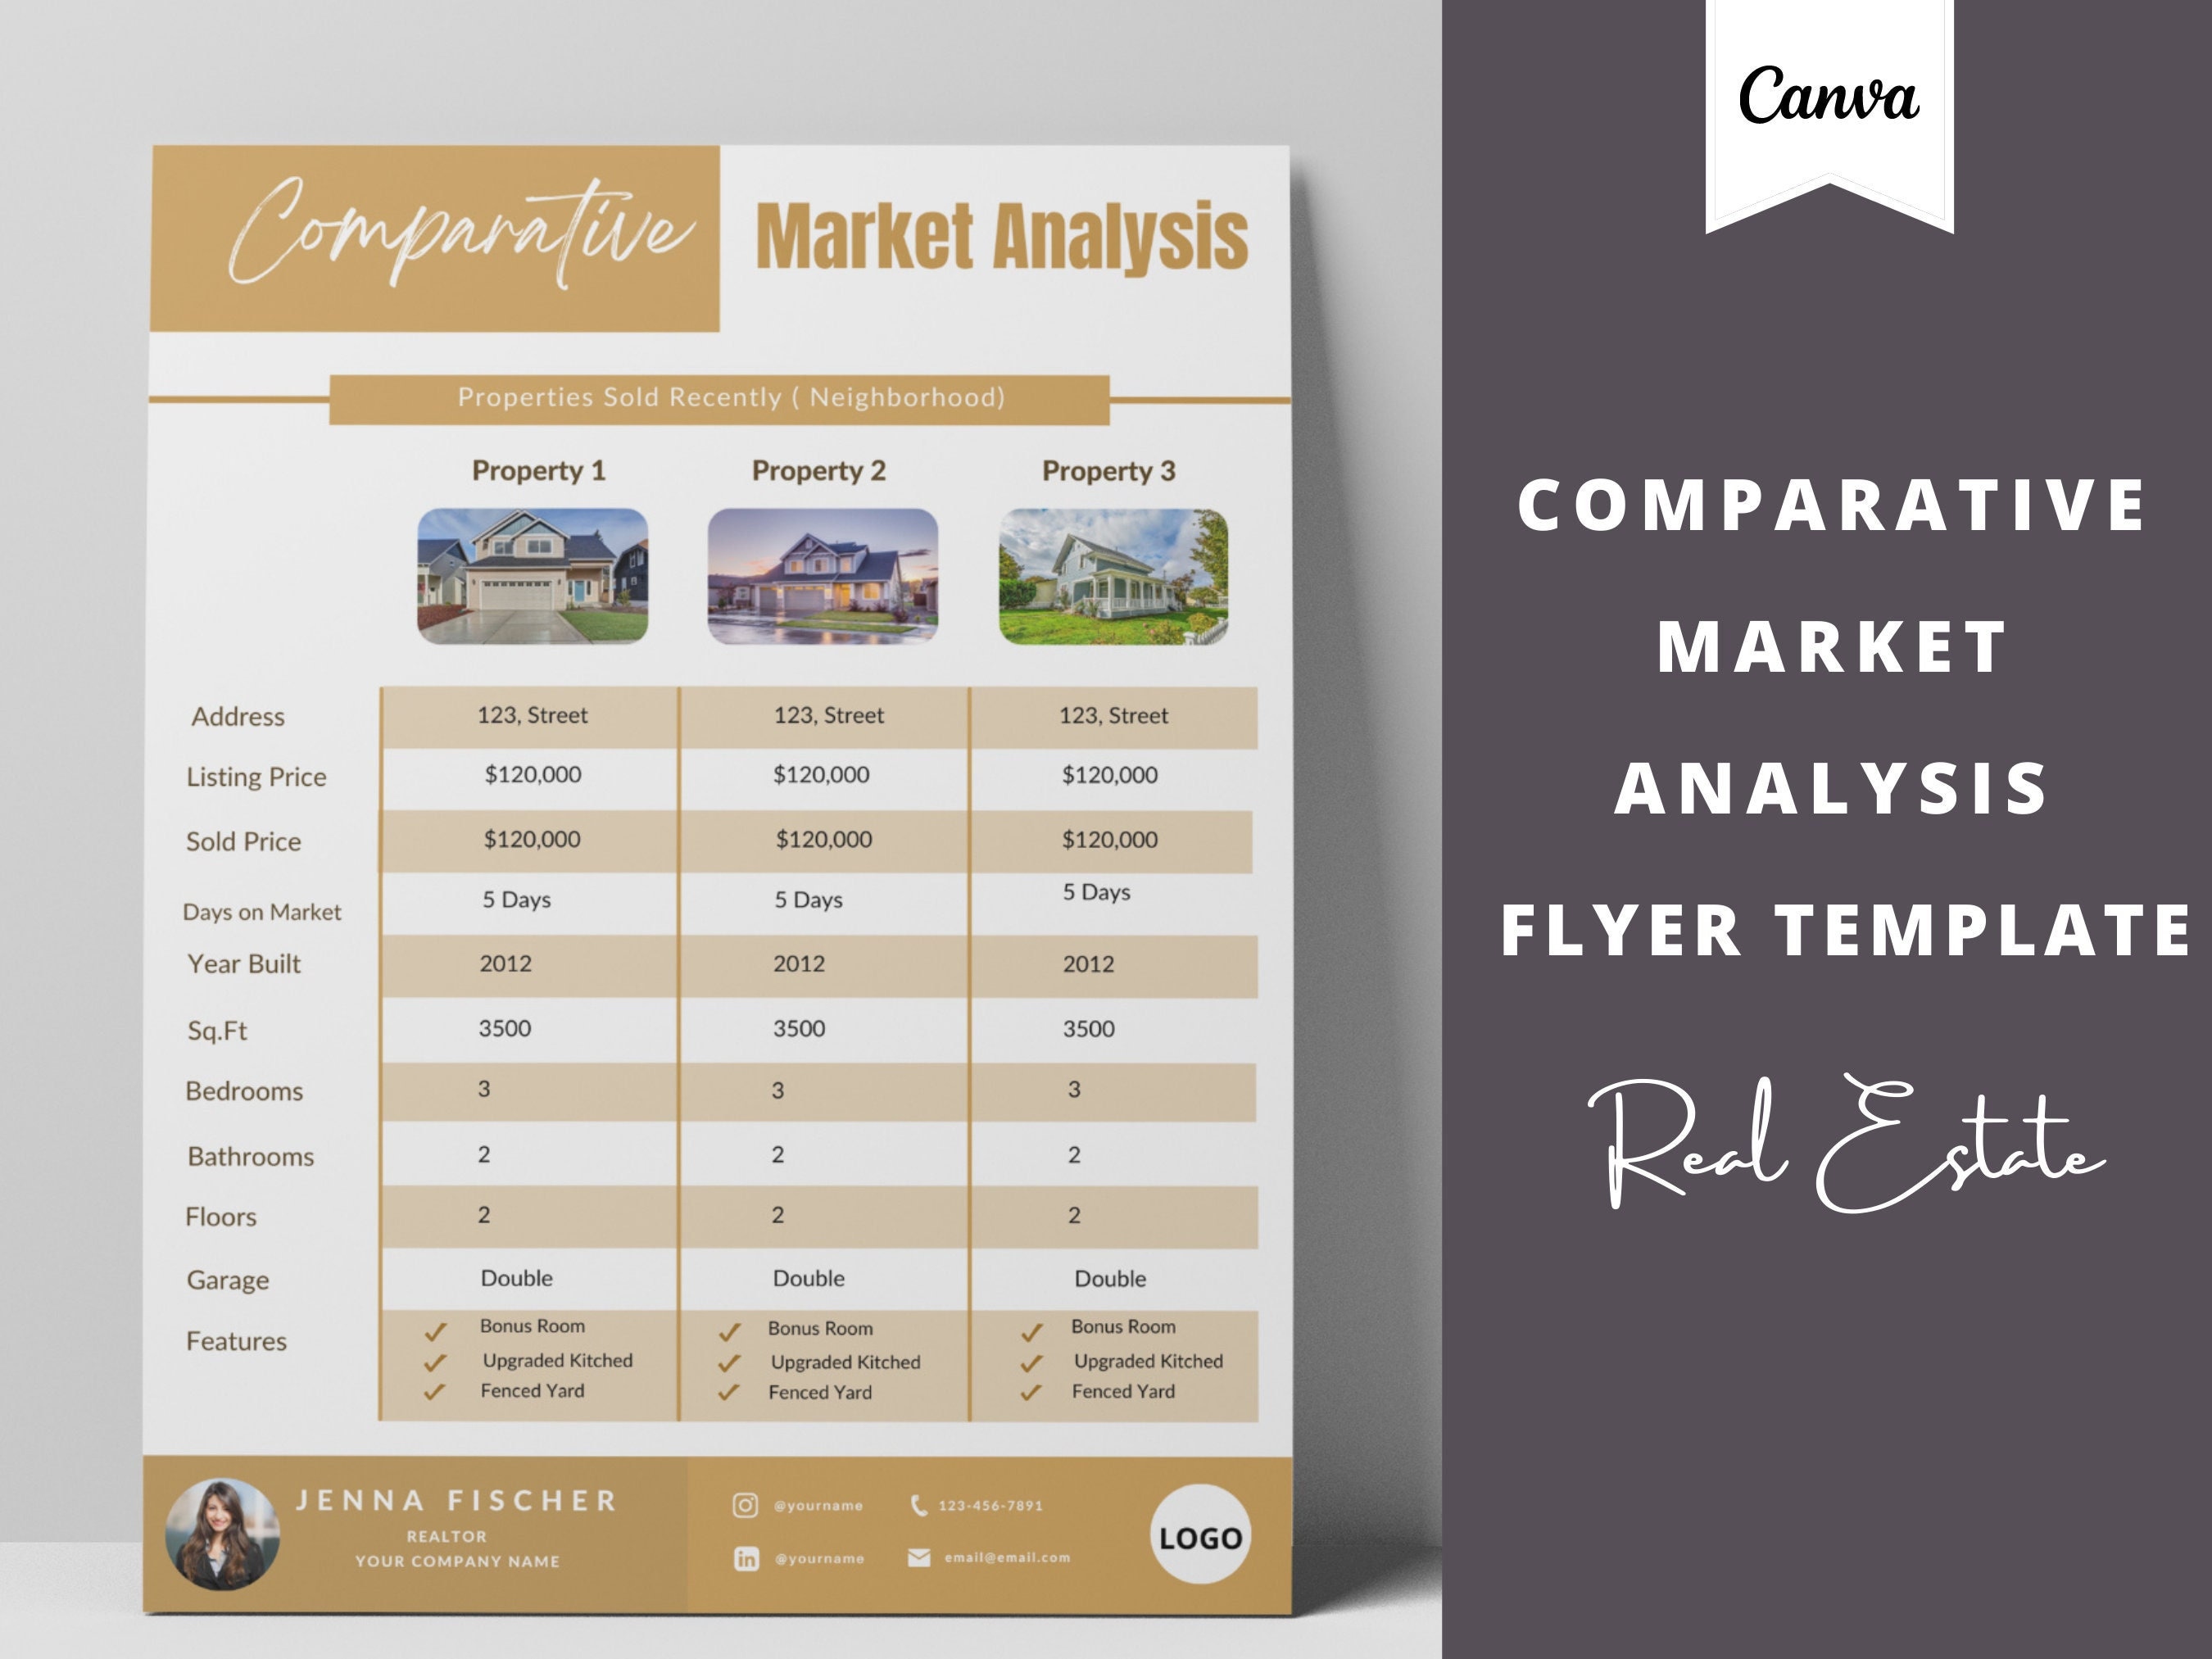
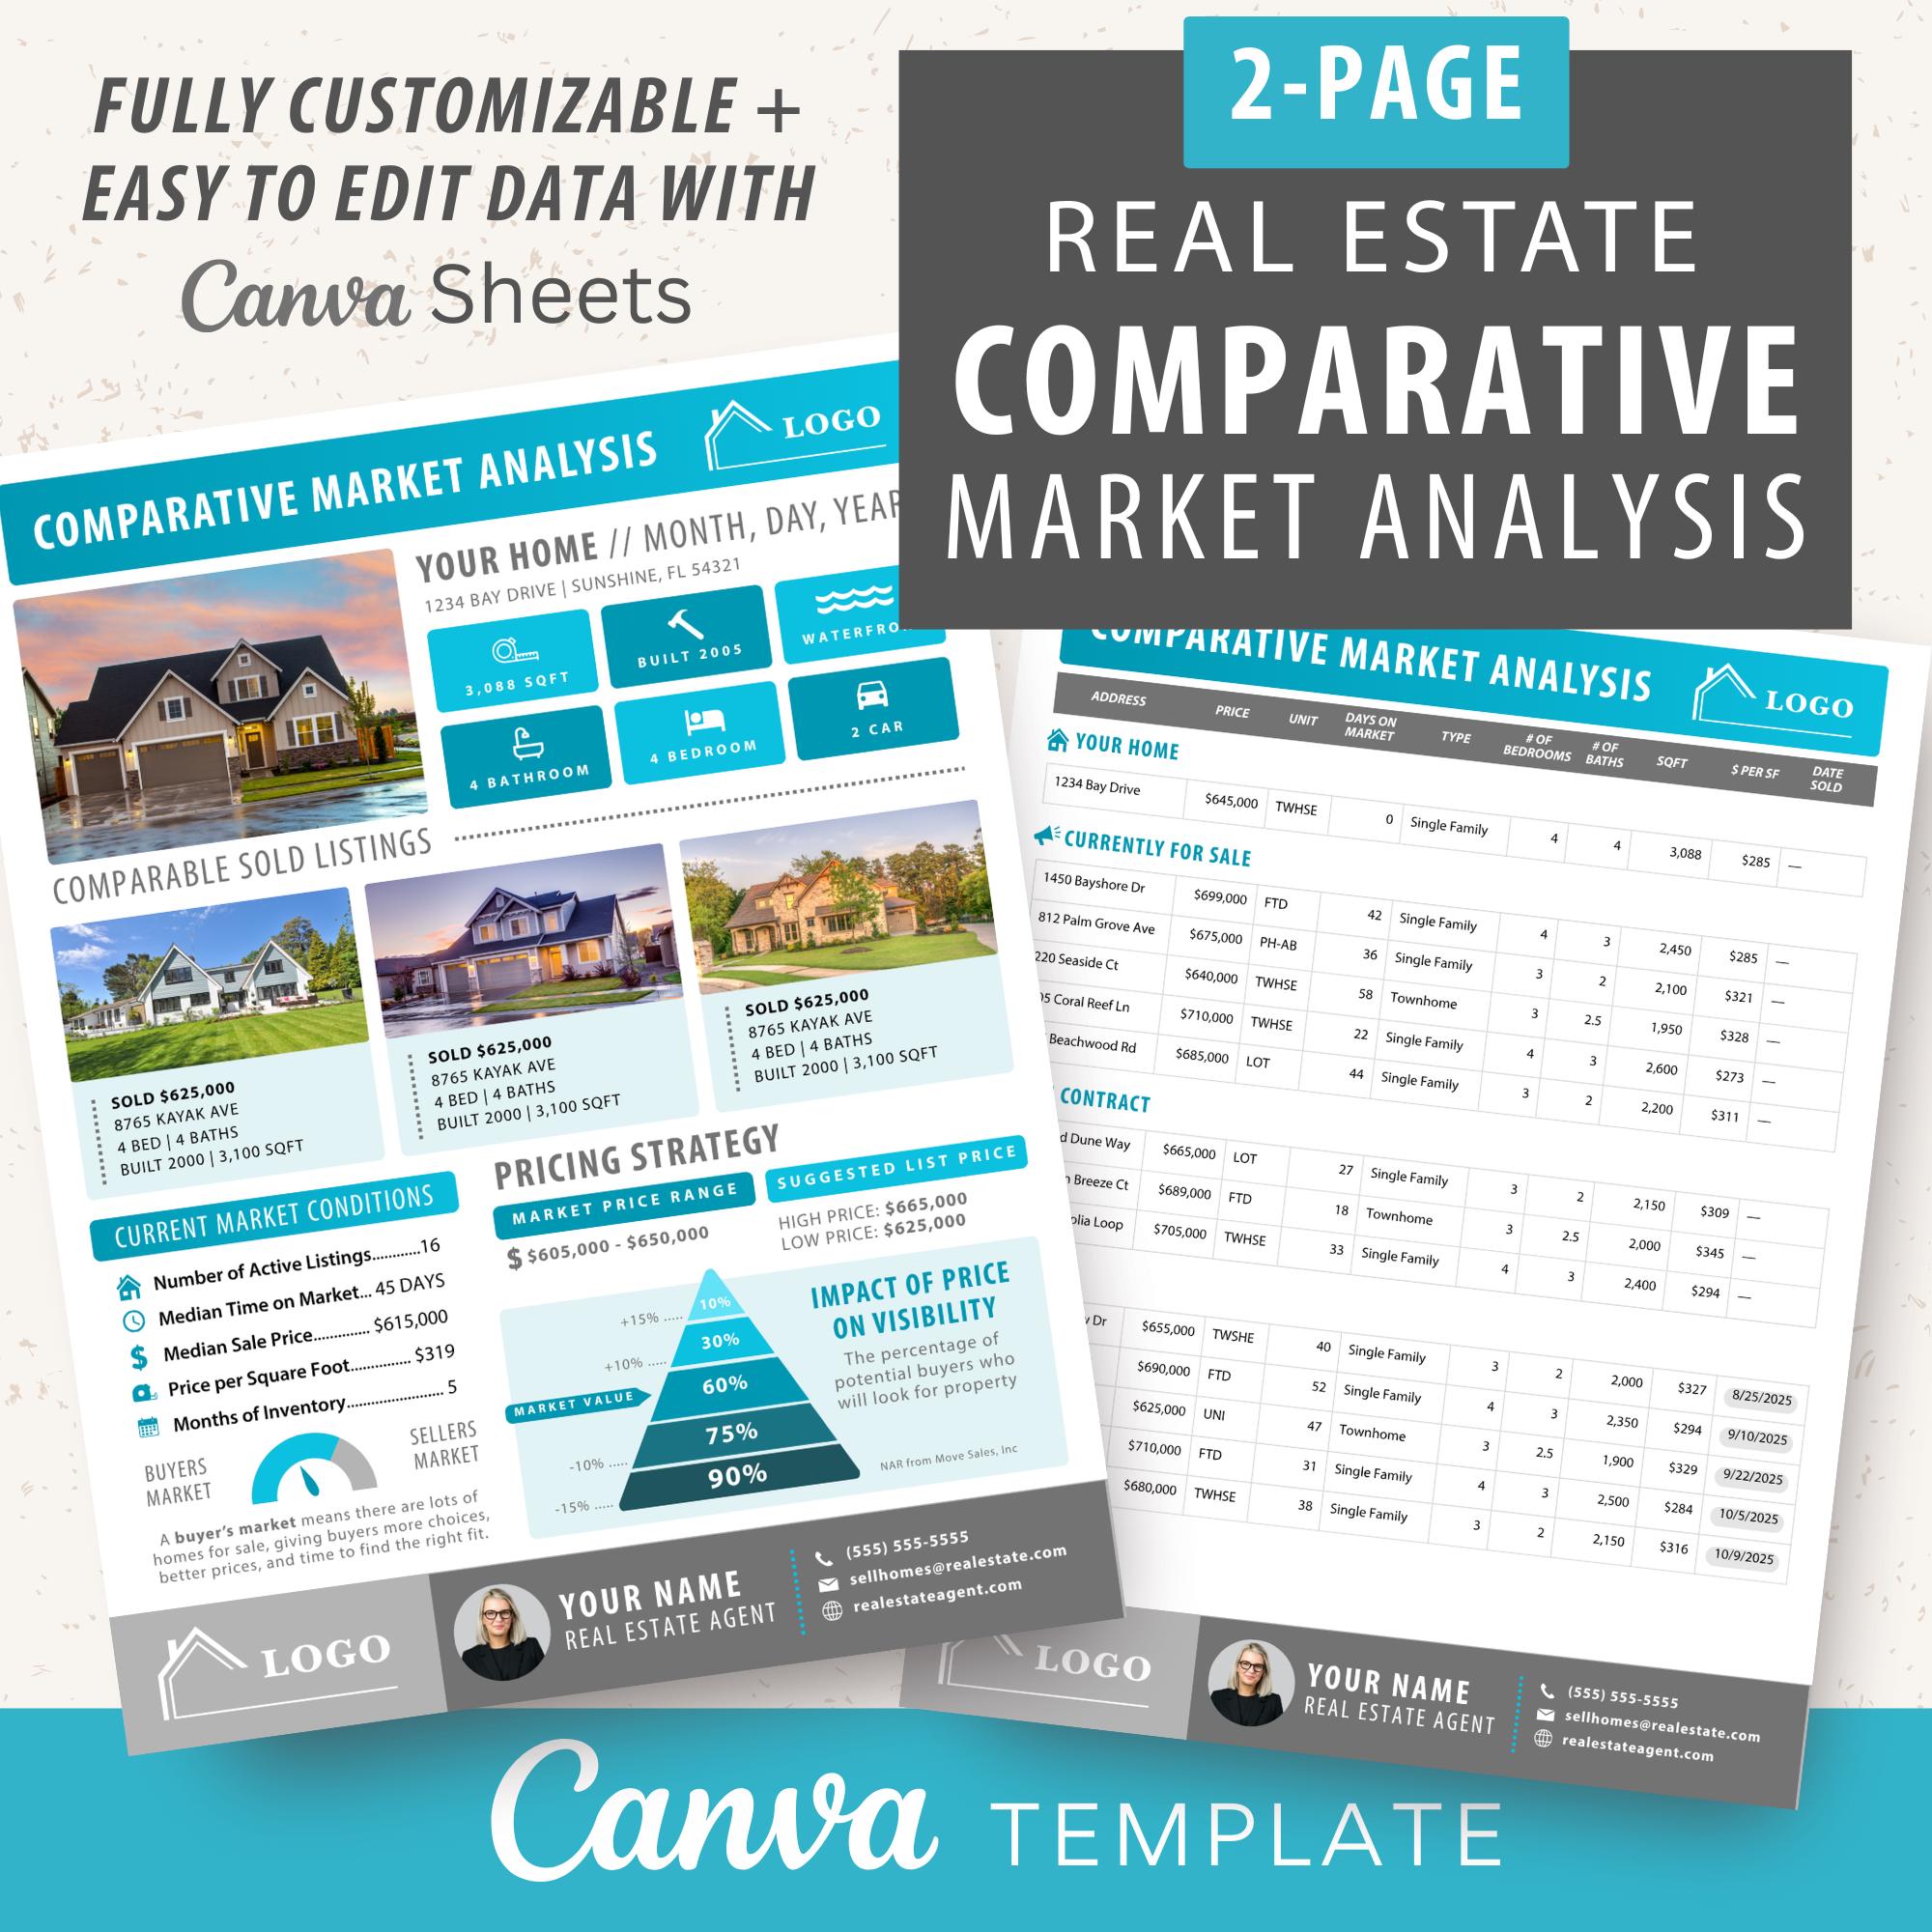
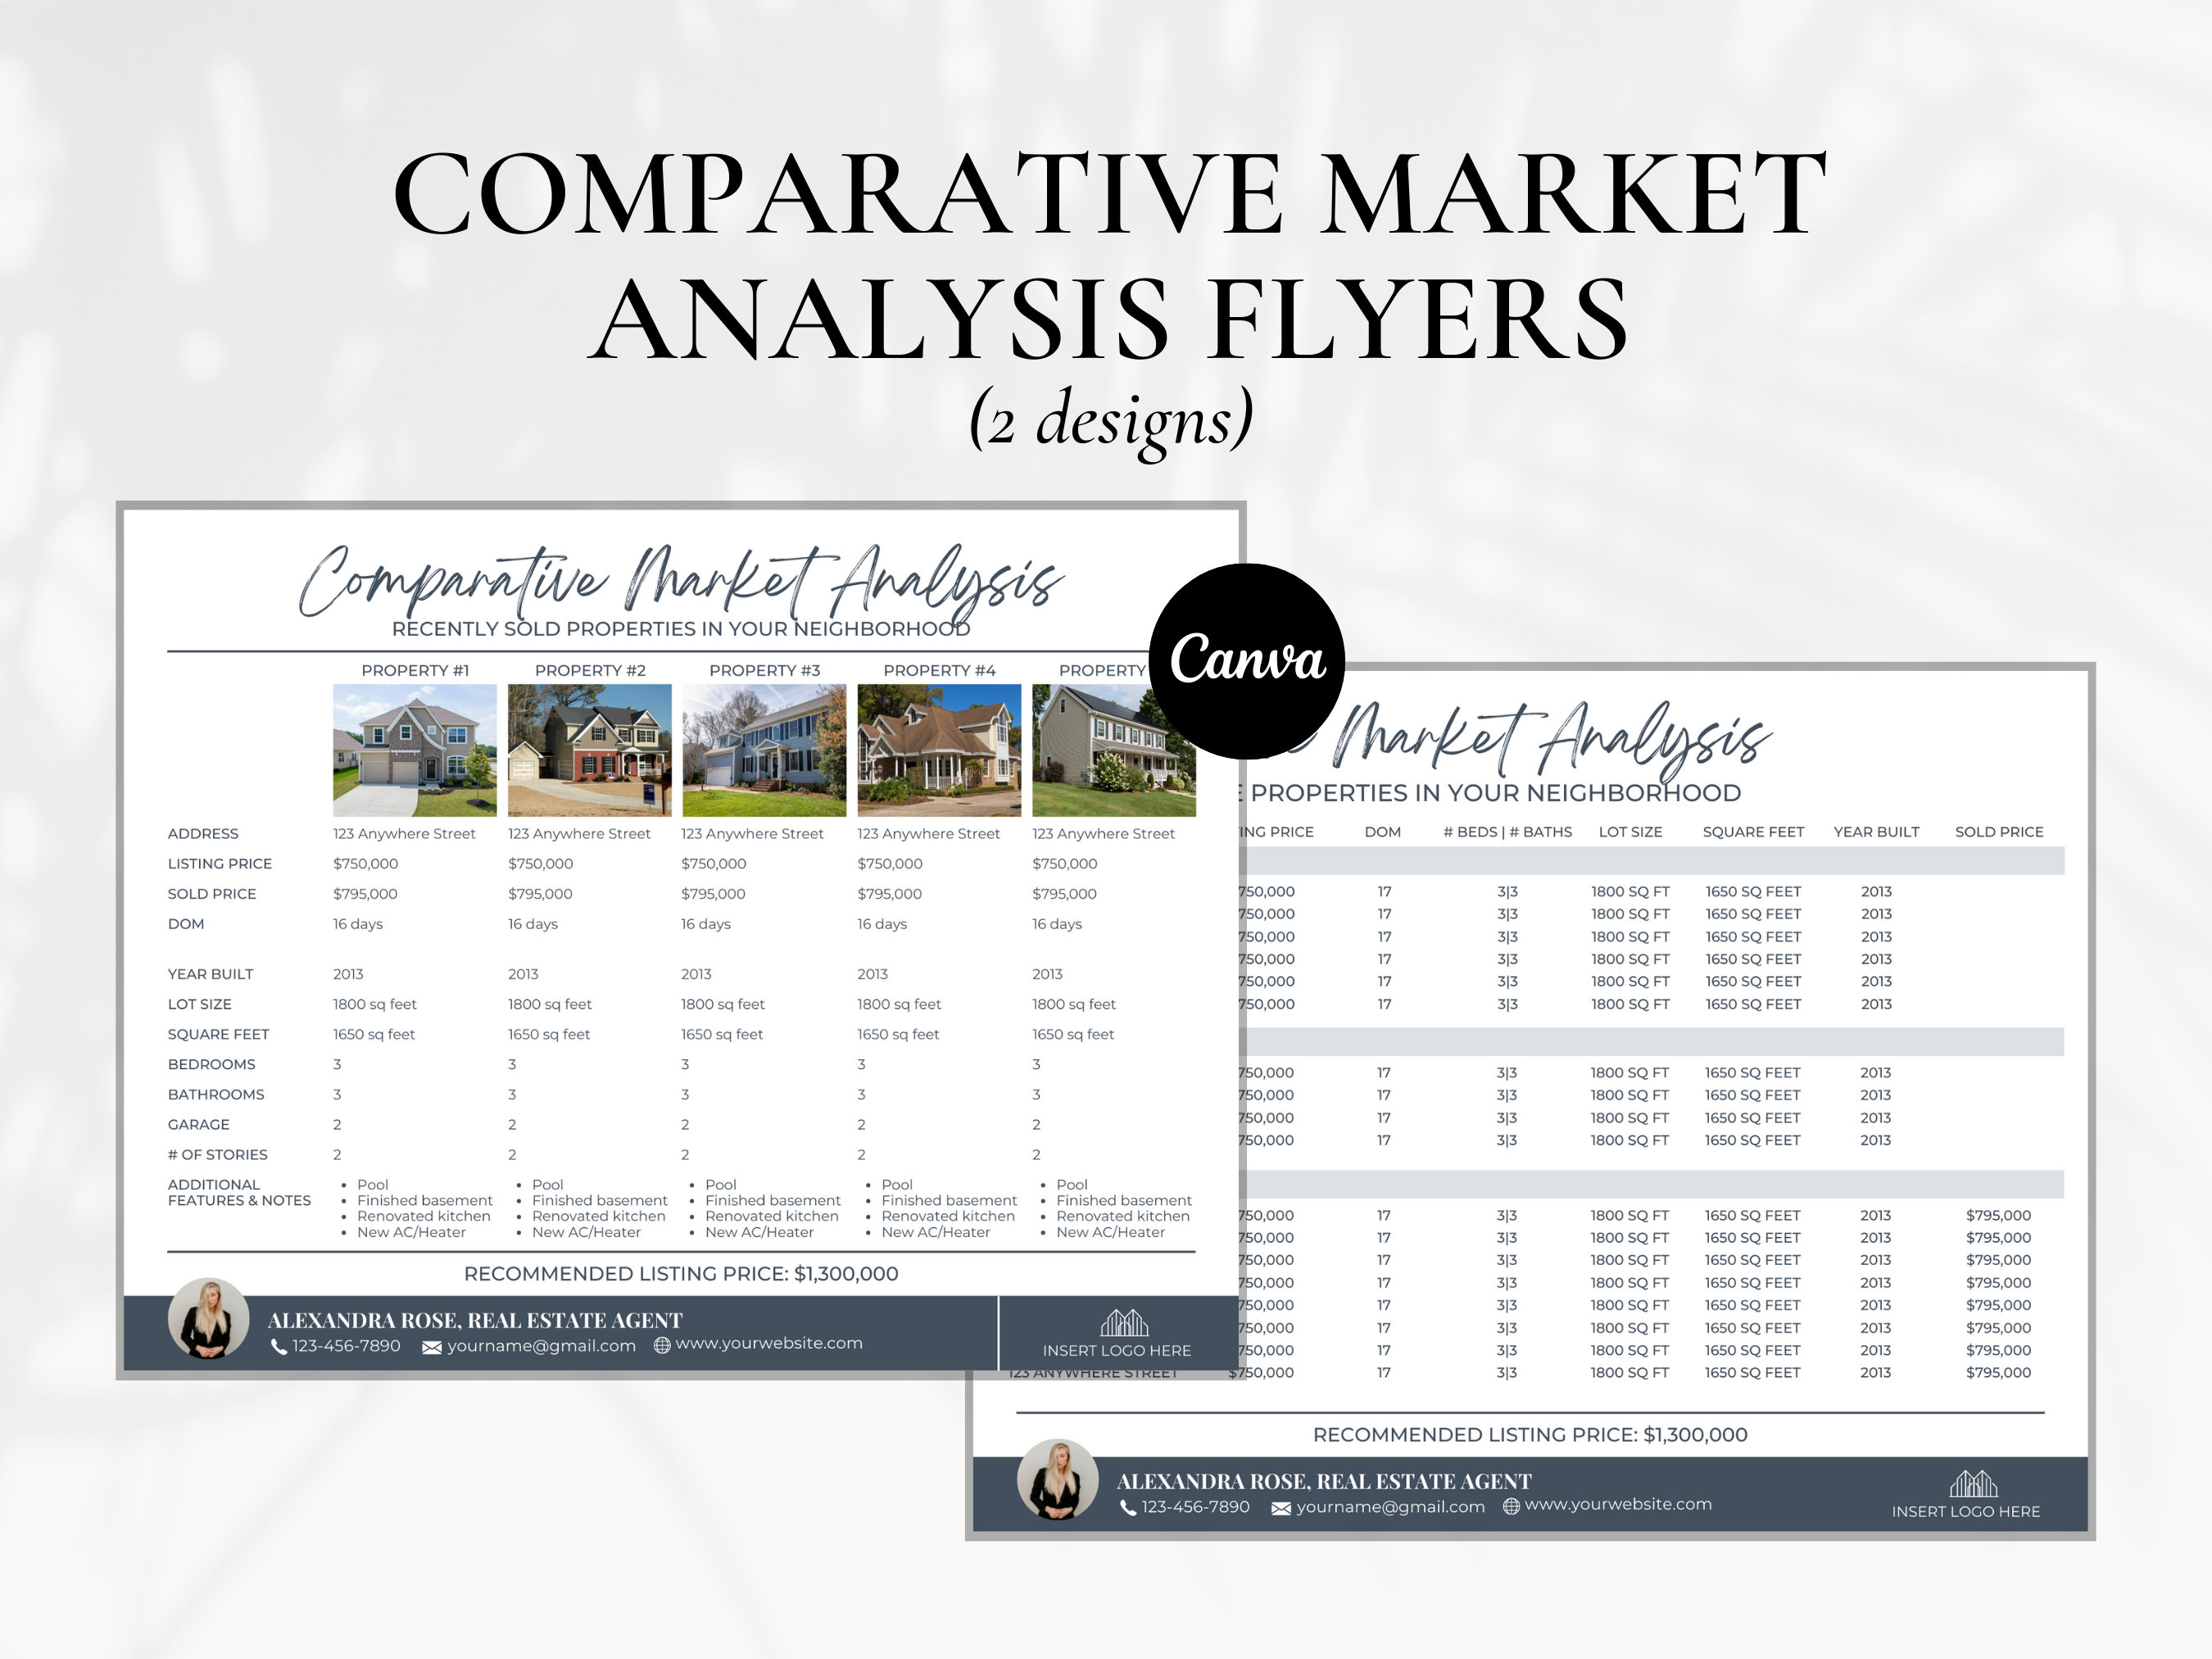
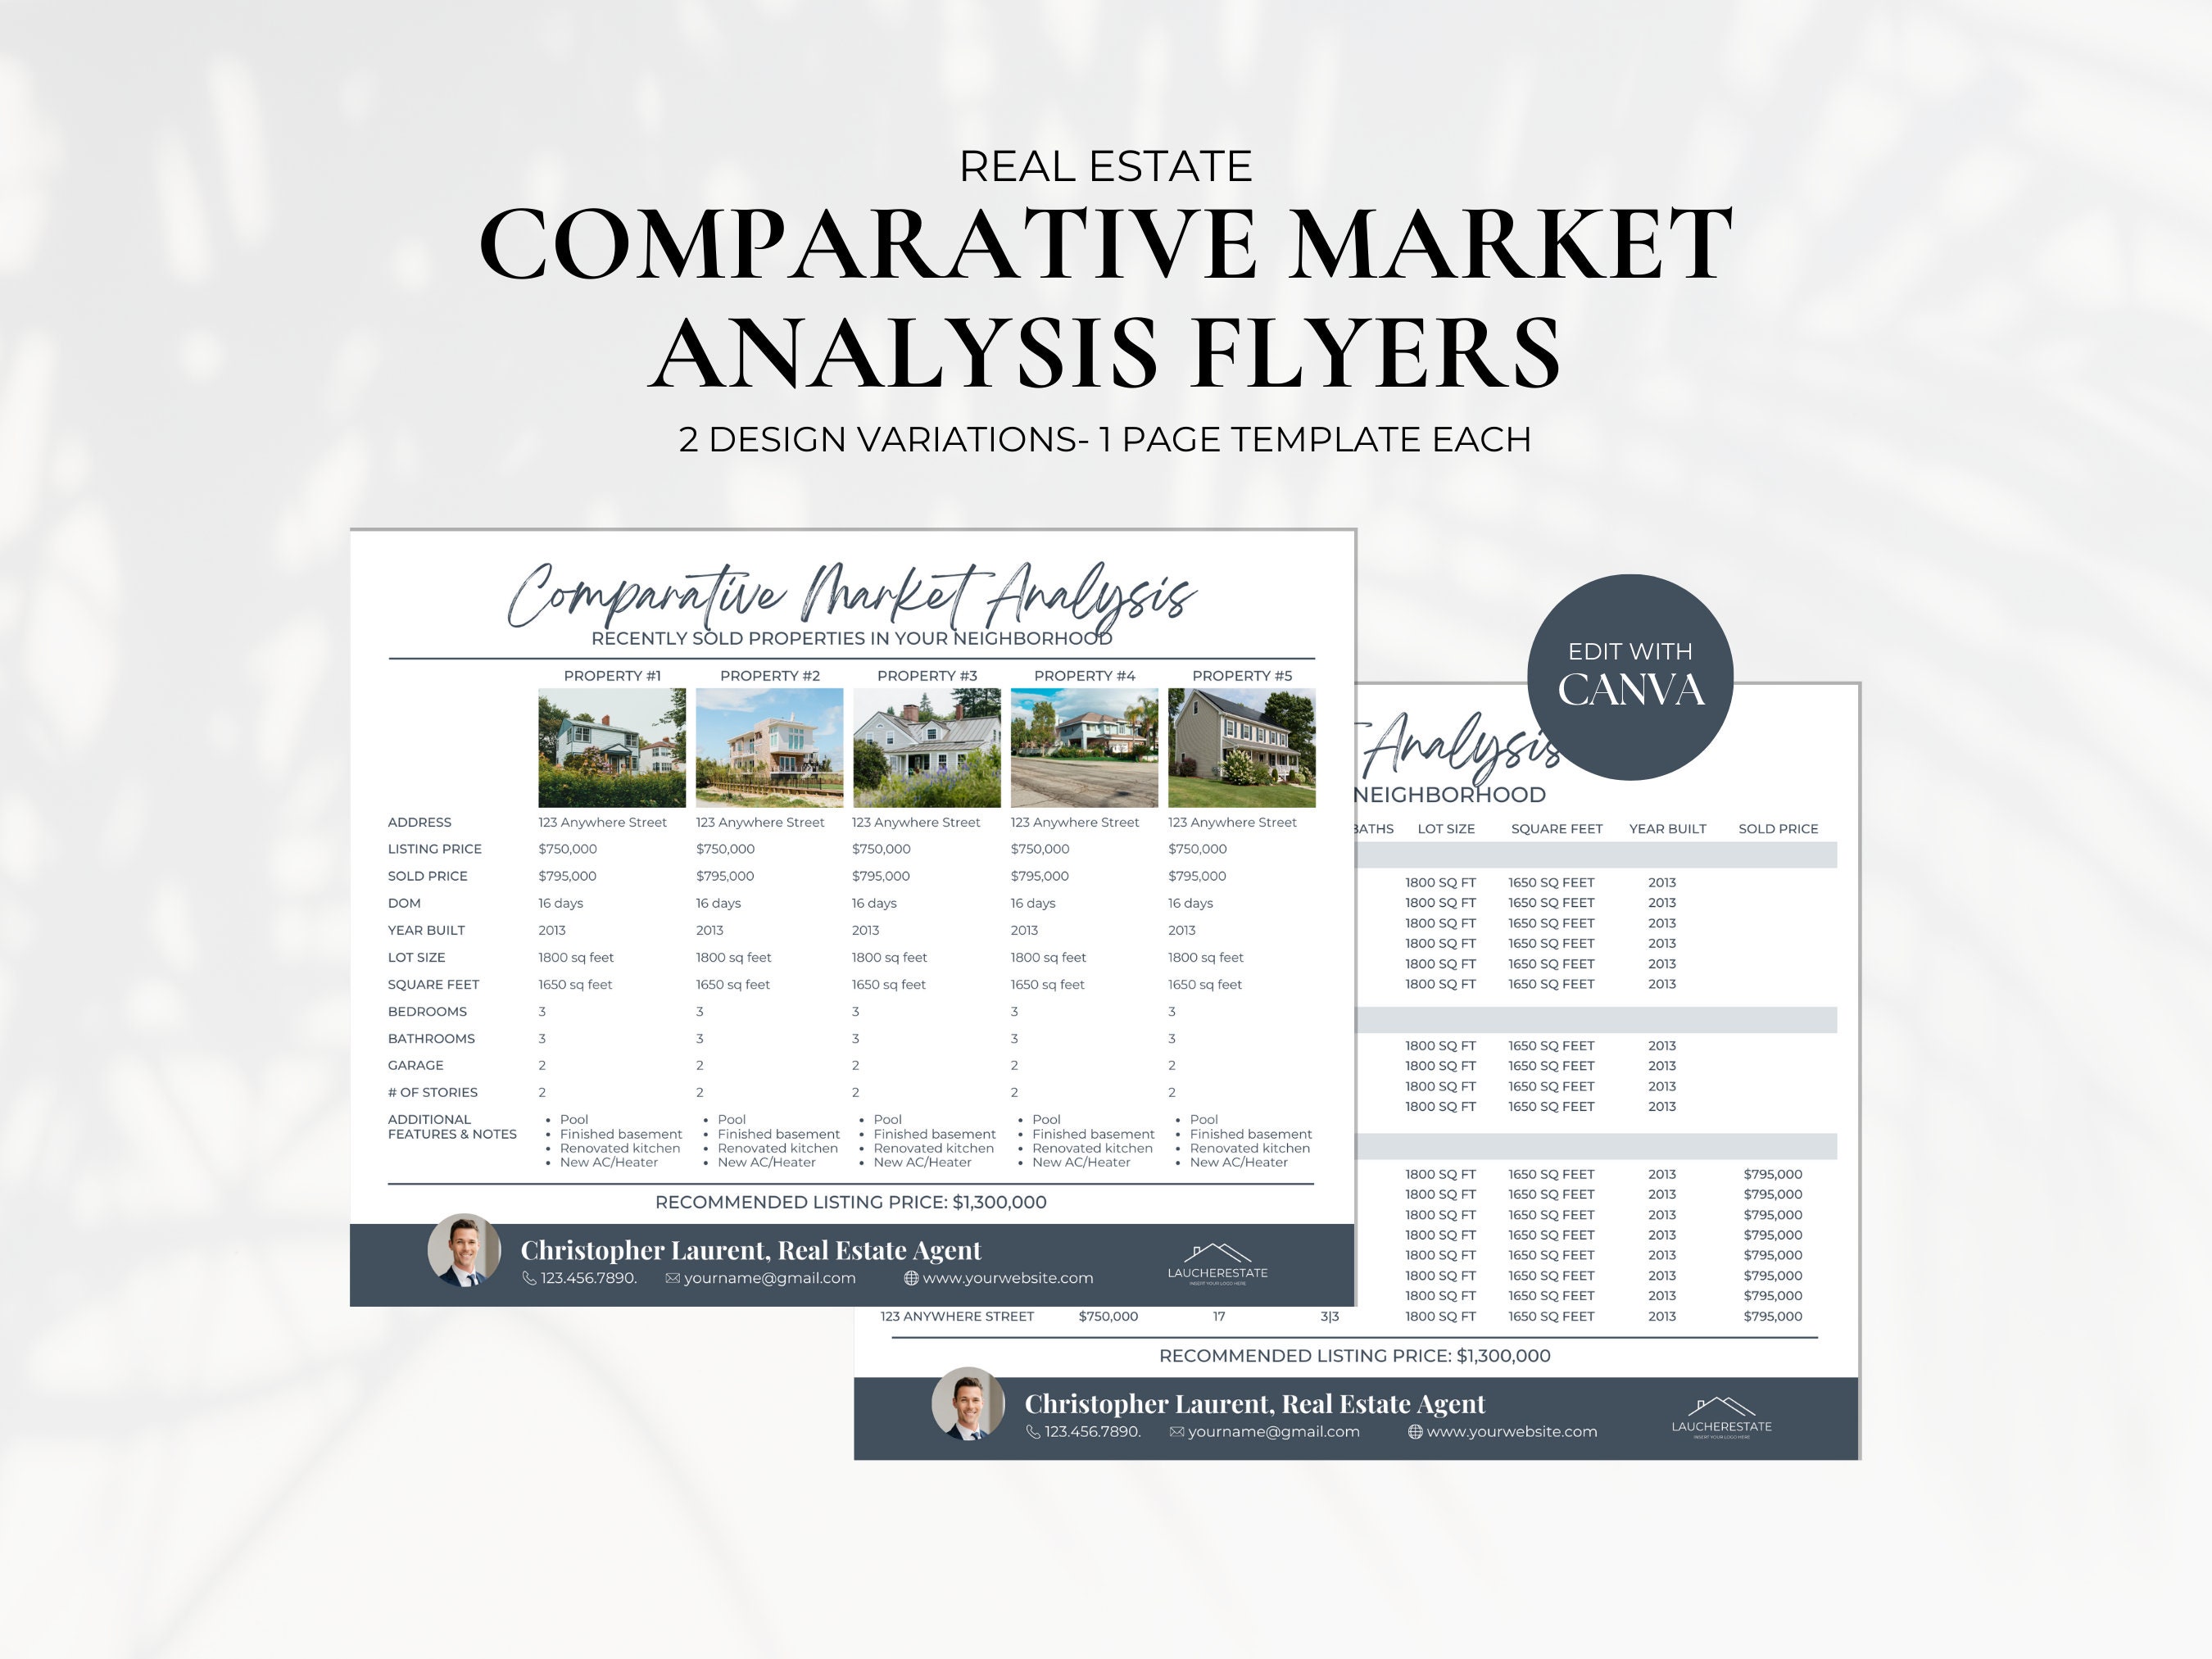
I spent years building CMA spreadsheets for clients, and the honest truth is most of them are overcomplicated nonsense. You don't need twelve columns tracking square footage variations to the decimal point. What you actually need is a clean template that forces you to look at the right comparable sales and adjust them intelligently. That's what I'm laying out here. A Real Estate Comparative Market Analysis Template is basically a structured worksheet that helps you find recently sold properties similar to the one you're evaluating, then adjusts their prices based on differences. It's not appraisal work, but it's close enough for pricing a listing or making a buy-side offer in most markets. The key word is most.
Real Estate Comparative Market Analysis Template — What I Actually Use
My current template has six main sections. Property details for the subject, comparable sale identification, adjustment columns for key variances, final adjusted values, a summary range, and a notes column for context that numbers miss. I keep it in Google Sheets because my team can access it live during negotiations. Here's how I build one from scratch when a new listing comes in. First, I pull the subject property's basic facts: address, bedrooms, bathrooms, square footage, lot size, year built, and condition. Then I open my local MLS or the county records and search for sold properties within the last ninety days, ideally within a half-mile radius and within twenty percent of the subject's size. That filter gets me to three to five comps usually. If the market is moving fast, like it was in 2021 through 2023 in most of the country, I shrink the window to sixty days and widen the size variance to thirty percent. Prices change too quickly for the old ninety-day rule. In slow markets, I flip it back.
Once I have the comps selected, I start adjusting. The common adjustments I make are for square footage, bedroom and bathroom count, lot size, condition or updates, and age. I don't adjust for everything. I've seen agents waste hours trying to account for landscaping differences or whether a garage is attached versus detached, and it adds noise instead of signal. Each adjustment is a dollar figure. If a comp sold for less than the subject and has smaller living area, I add the difference. The size adjustment is usually calculated per square foot using local data. In my market right now, that lands around eighty to one hundred twenty dollars per square foot for mid-tier homes. High-end properties move differently. You have to look at your own neighborhood data, not someone else's. Bed and bath adjustments vary wildly by market. In some areas a third bathroom adds twenty thousand. In others it adds nothing because every house has three. Check what buyers are actually paying for those features. Look at paired sales if your MLS provides that data, or just observe the price spread between two-bedroom and three-bedroom homes in your area over the last year.
Get the Full Details
Condition is the hardest adjustment and the one I see people mess up most. I use a simple scale: poor, fair, good, excellent. If a comp is in excellent condition and sold for three hundred thousand while the subject is in good condition, I might subtract ten to fifteen thousand depending on what repairs or updates are needed. Don't just guess. Actually walk through the subject property and note the roof age, HVAC, flooring, kitchen condition, and any visible deferred maintenance. Those items compound fast.
The Problem I Ran Into and How I Fixed It
Last fall I was pricing a 1920s bungalow on a quiet street in a neighborhood where most homes had been gut-renovated. Every comparable sale in the area was a fully updated property. The street itself had three sold listings, but all three were modernized. The subject was untouched. My template forced me to make a condition adjustment, but the market had no data point for how much buyers would discount a non-renovated home in that specific micro-market. I ended up finding a off-market sale where the seller had listed at four hundred fifty thousand and the house needed significant work. It never hit the MLS. I tracked it down through a local agent contact and used it as a reference adjustment. The lesson was simple. Standard comp searches miss critical data. I now always do a broad search and then verify with at least one person who works in that specific neighborhood. A real estate agent who lists and sells there regularly will know if a particular street commands a premium or a discount for condition differences. That human input beats any formula.
What Most People Get Wrong
The biggest mistake I see is using too few comps. Two sales is not enough unless they're nearly identical to the subject. Three is the minimum, five is comfortable. If you only have two comps, you should say so and note the limited data in your presentation. Hiding that fact makes you look careless. Another common error is adjusting for things that don't matter. I once saw a CMA that adjusted for the fact that one comp had a detached garage and the subject had an attached one. In that market, attached versus detached made zero difference to price. The adjustment added noise and made the final number look precise when it wasn't. Only adjust for factors that actually move price in your area. A third issue is ignoring the direction of the market. If prices are rising sharply, using older comps pulls your analysis down. If prices are falling, recent comps pull it up. Always note the market trend on your template. One line saying prices rose eight percent in the last quarter changes how you interpret every adjustment you make.
When This Method Breaks Down Completely
Comparative market analysis doesn't work well for unique properties. A historic landmark, a property with unusual zoning, a home on a commercial-residential border, or a land parcel with mixed-use potential. There simply aren't enough comparable sales. In those cases, the income approach or cost approach makes more sense, or you just rely heavily on agent experience and negotiation rather than a spreadsheet. It also struggles in very small markets with low transaction volume. If only four or five homes sell in a neighborhood per year, finding three usable comps becomes a guessing game. I've had to tell clients in rural counties that I couldn't give them a reliable CMA range and instead suggested they look at price-per-acre comparisons across a wider region. It was less precise but more honest than forcing numbers together. Timing matters too. In a sudden market shift, like when interest rates jumped three points in a single month, your template becomes outdated almost immediately. I learned this the hard way in early 2022 when I built a CMA on a Tuesday and by Friday the comps were irrelevant. My workaround was to add a date stamp and a recalculation reminder for every template I created, so I knew exactly when to refresh the data.
Building the Template in Practice
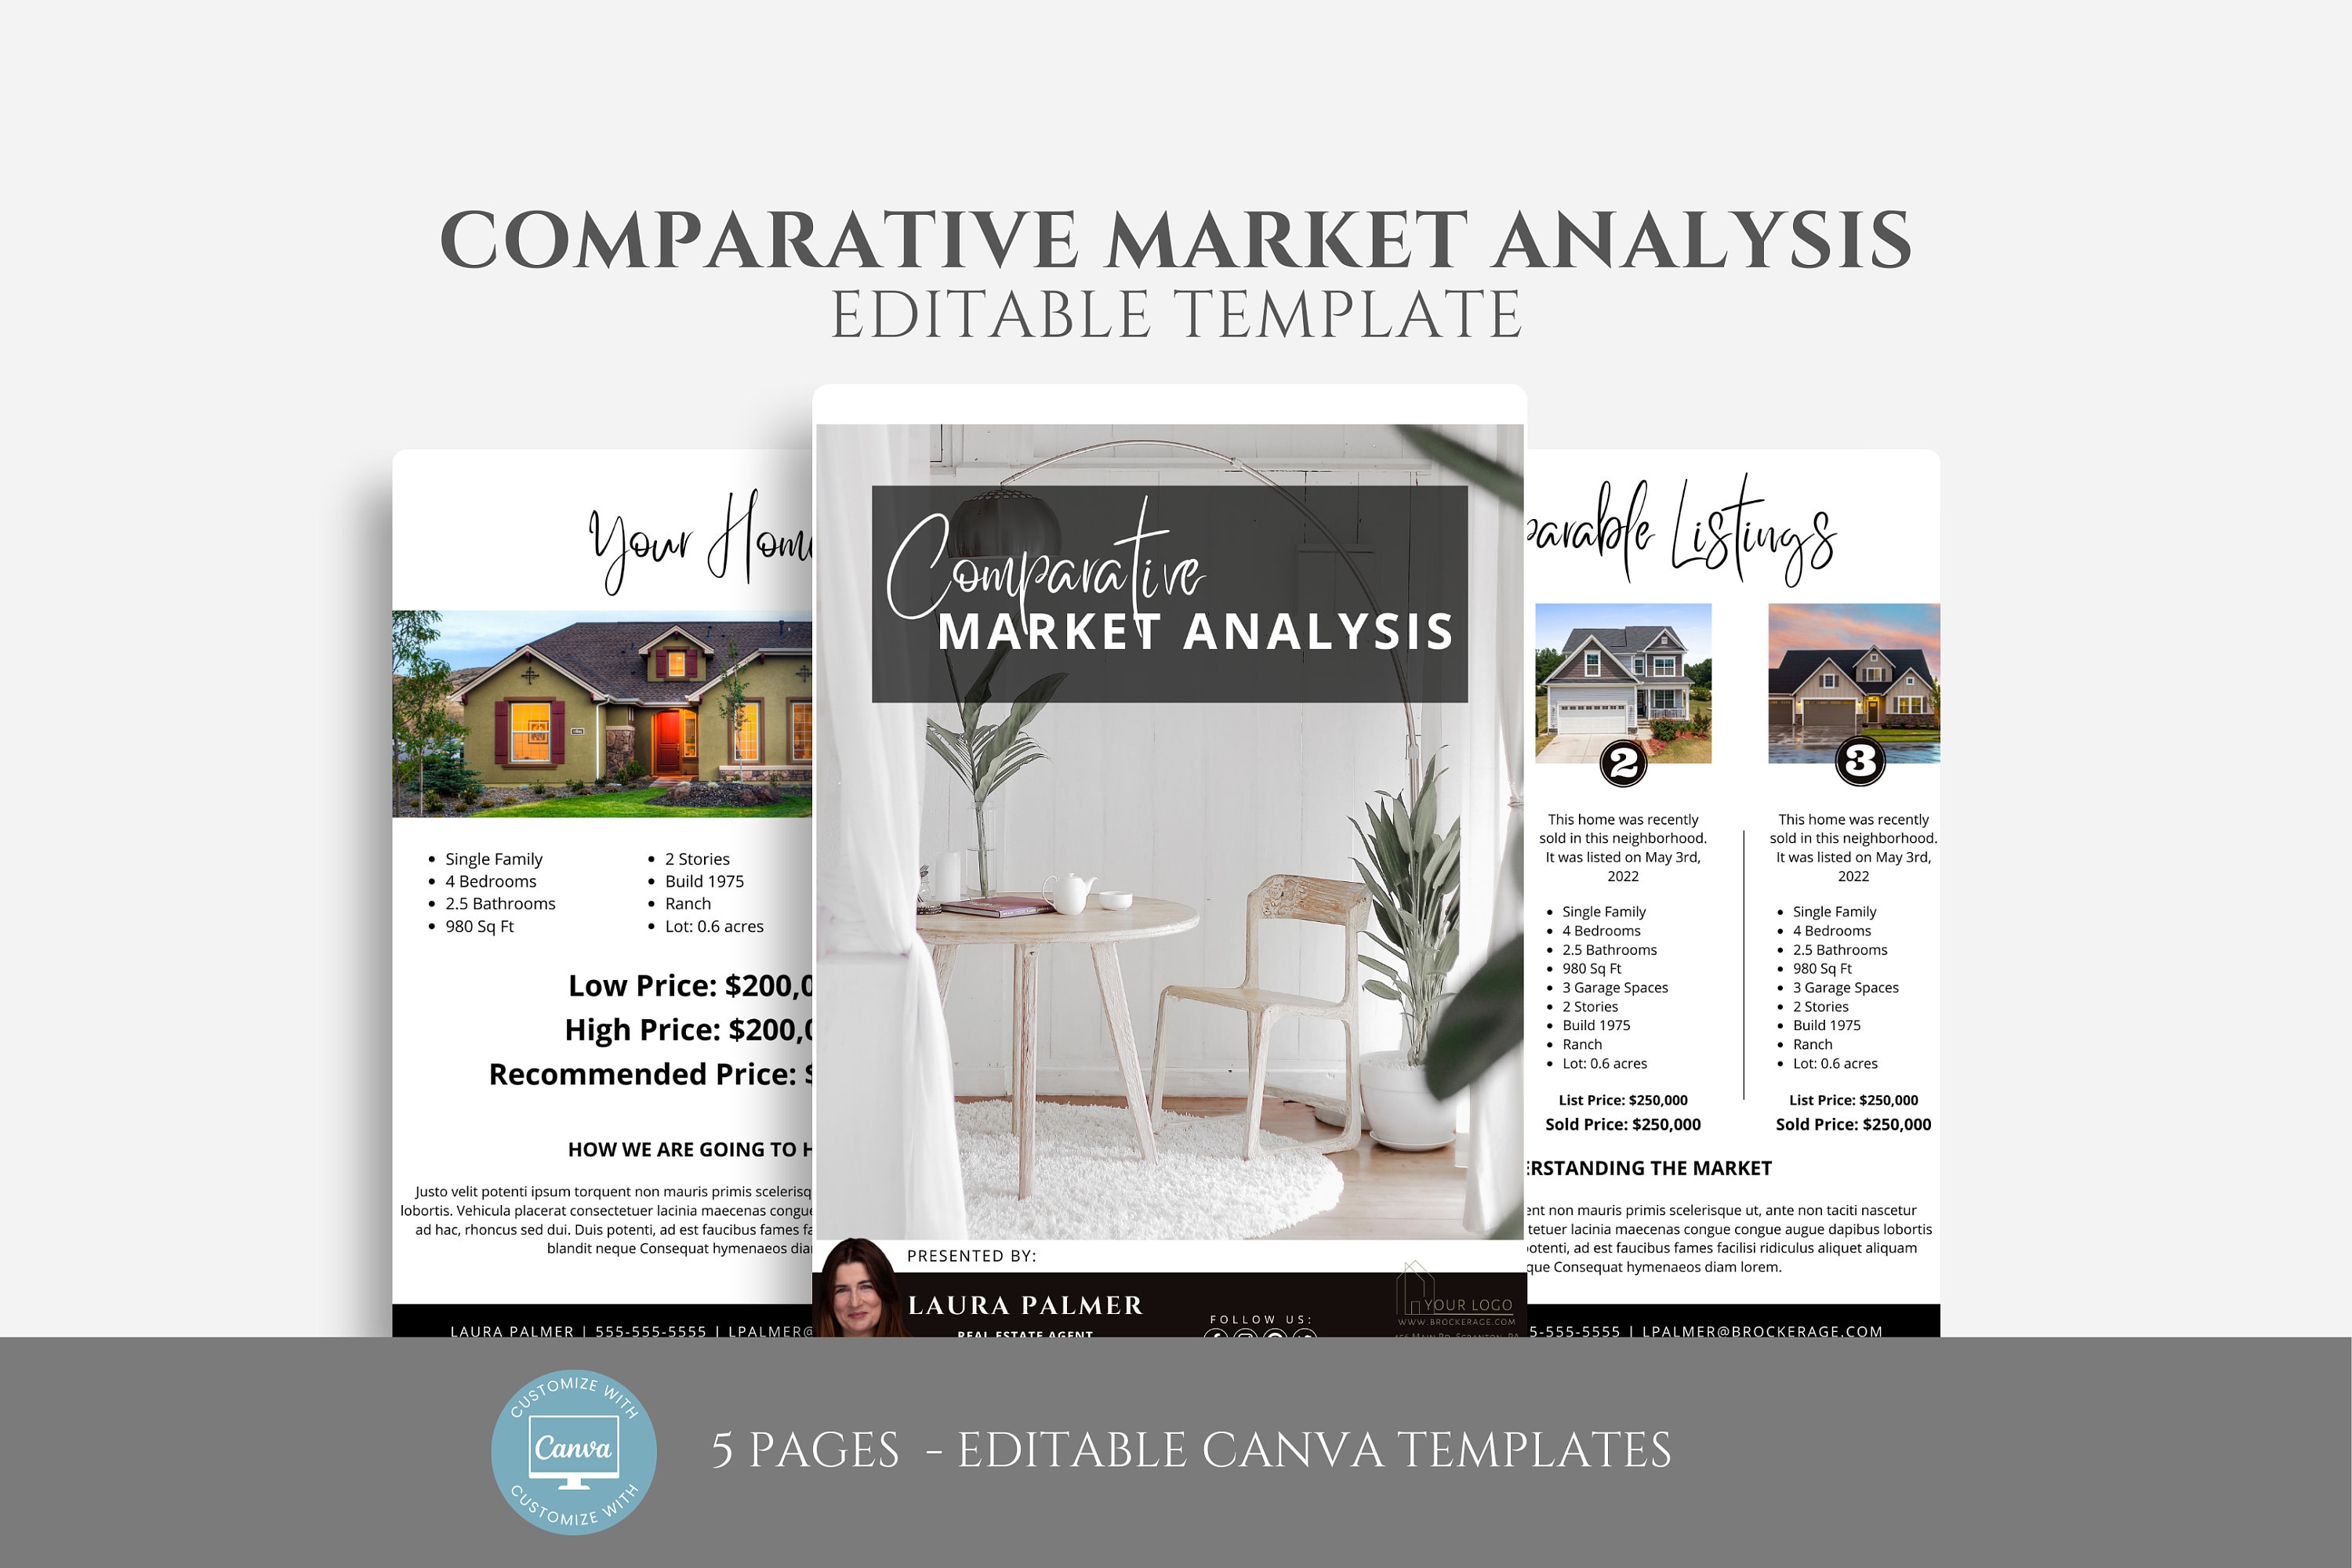
Start with a spreadsheet. Column A is the subject property. Columns B through E are your comparable sales. Under each comp, list the address, sale date, sale price, square footage, beds, baths, lot size, year built, and condition grade. Create a separate section for adjustments with rows for square footage, beds, baths, lot, condition, and age. The math is straightforward subtraction and addition. Adjusted sale price equals original sale price plus or minus each adjustment. Once you have adjusted prices for all comps, calculate the range and average. The average gives you a center point. The range tells you how much uncertainty exists. A tight range means you have confidence. A wide range means your comps weren't actually comparable and you need better ones. Add a notes row under each comp for anything the numbers don't capture. Proximity to a noisy street. A view of a parking lot. Recent flooding in the area. These details explain why a comp might be an outlier and help you decide whether to include or exclude it.
Save a master copy and create a new file for each property. Name it with the address and date so you can track your process over time. Reviewing past CMAs months later shows you whether your adjustment logic held up when actual sale prices came in. That feedback loop is how you get better at this without relying on anyone to teach you. If you want the actual template, I put mine on Google Sheets with preset formulas and color-coded adjustment cells. The link is in my signature. It's bare-bones, which is the point. You fill in the comps and let the spreadsheet do the arithmetic. The thinking part is yours.