Why Your Property Tax Bill Is Probably Too High
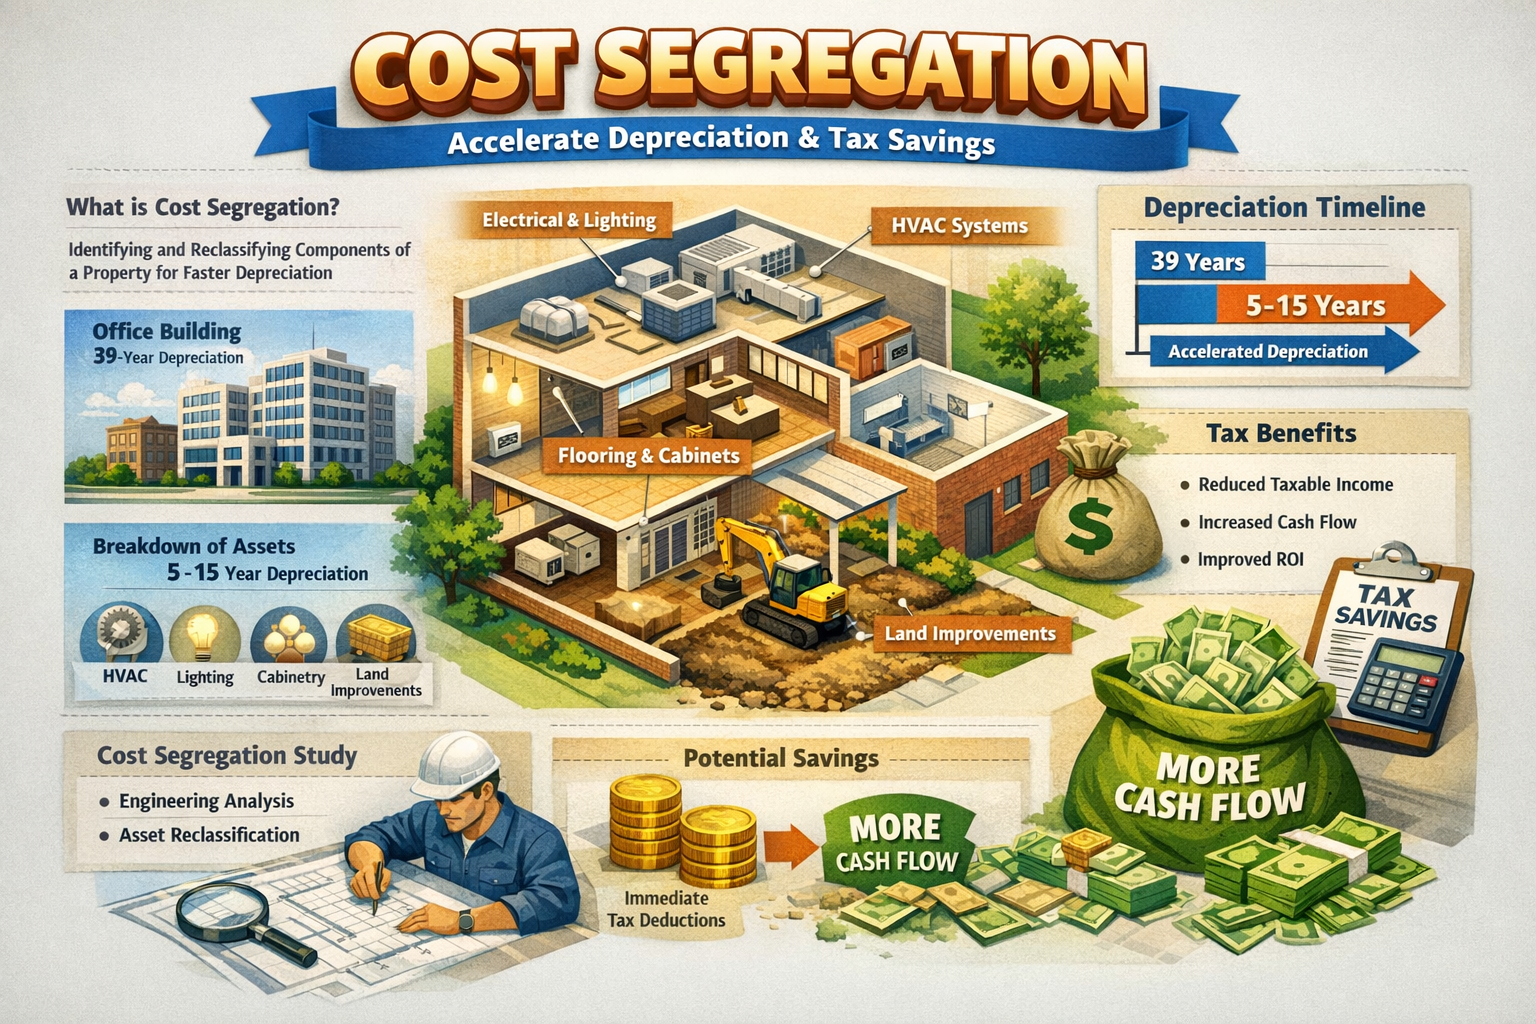
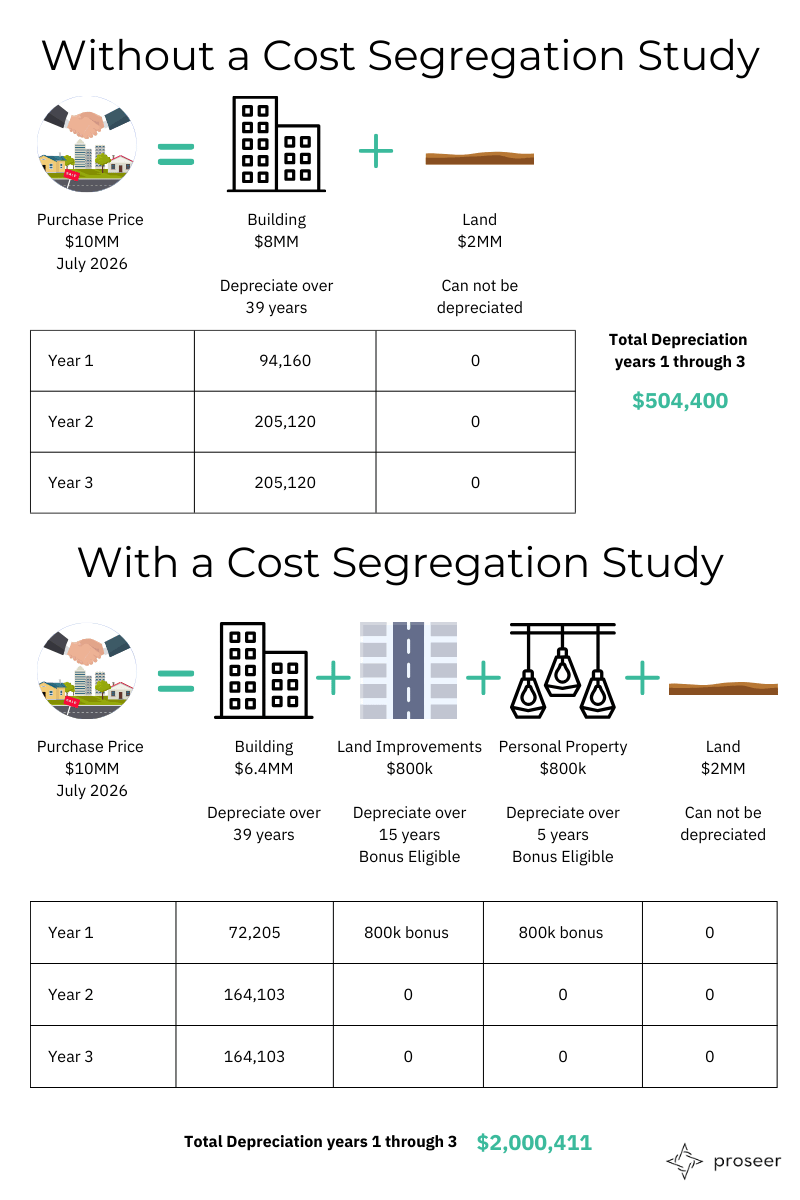
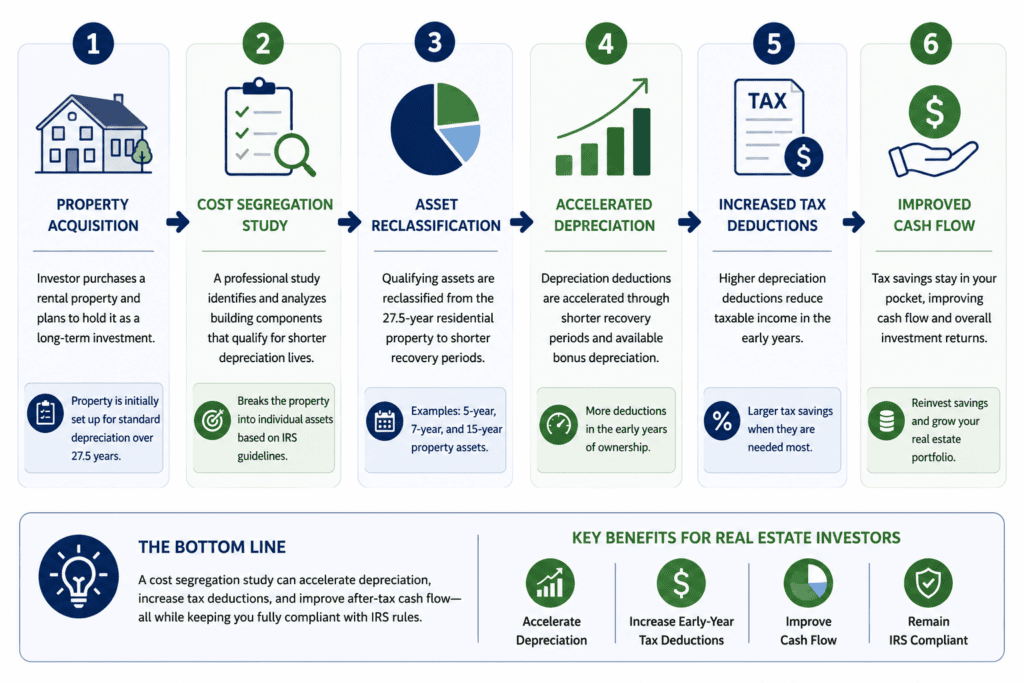
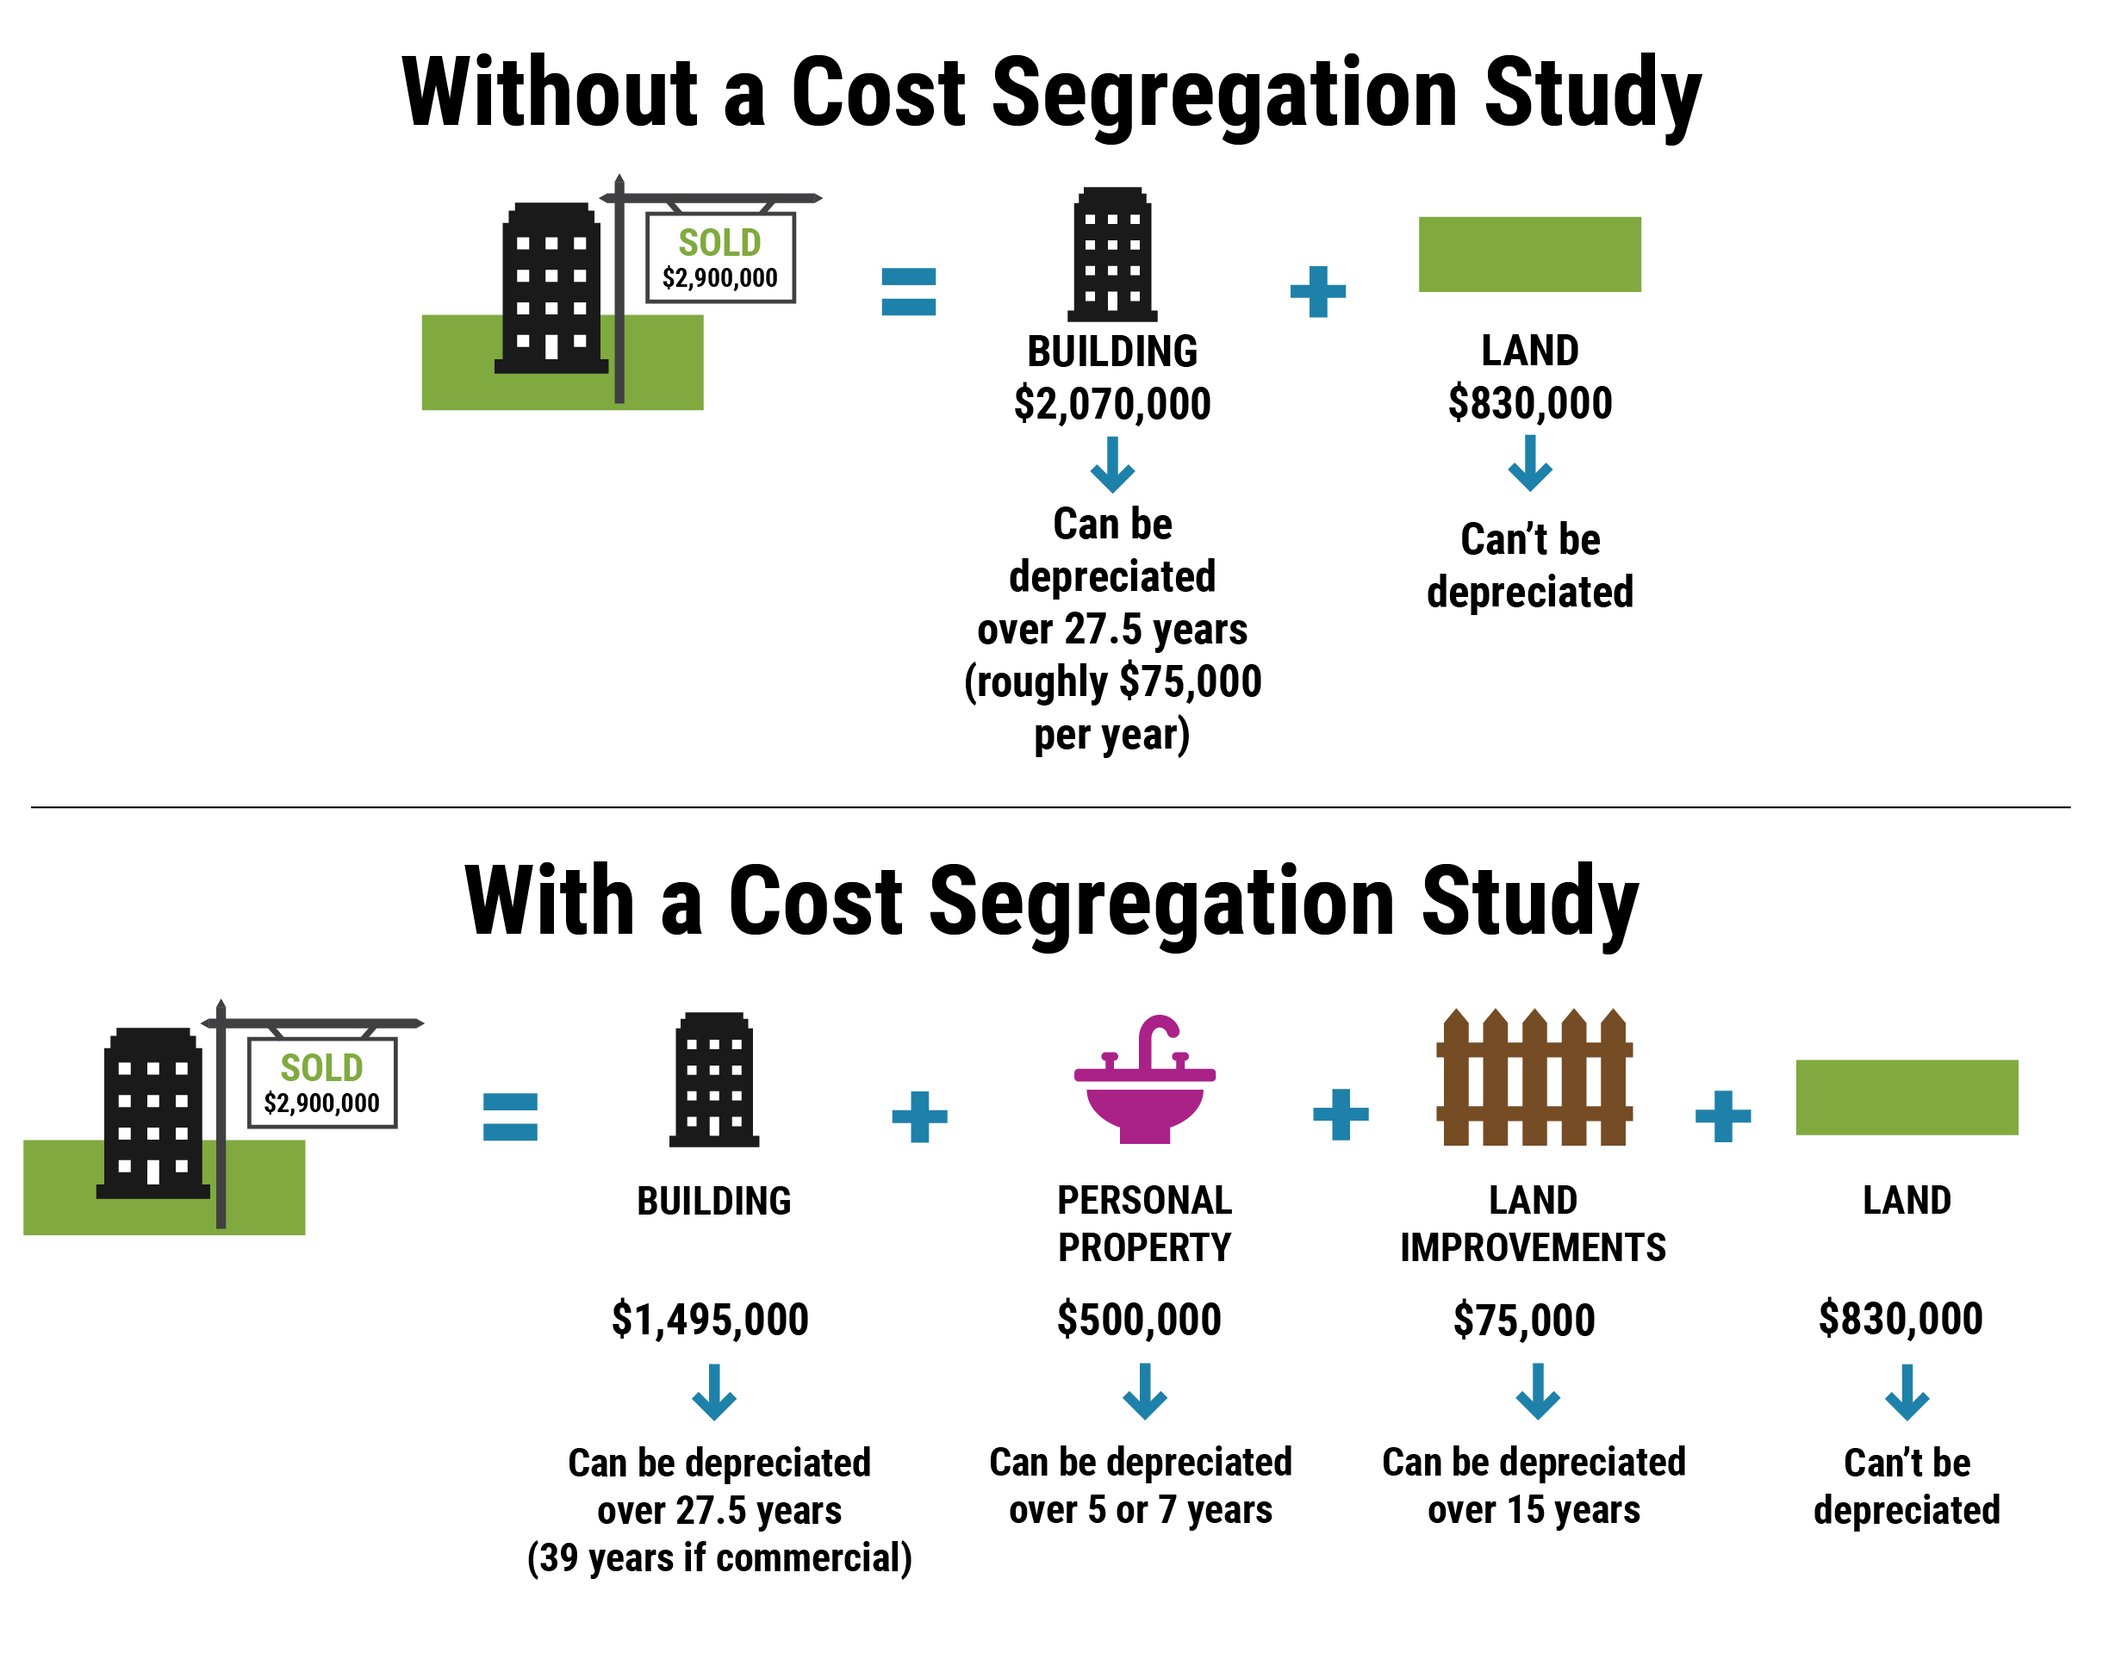
I've been doing this work for over a decade, mostly for commercial and multifamily properties. The basic premise is simple enough on paper but the actual execution trips up most people who try to handle it themselves. A Real Estate Cost Segregation Study breaks down a building's purchase or construction cost into shorter-lived asset categories so you can accelerate depreciation. Instead of writing off a property over 27.5 or 39 years, you reclassify portions into 5, 7, or 15-year buckets. The tax benefit comes from larger deductions in the early years of ownership. The process starts with the original purchase closing statement, construction draw schedule, or basis allocation from the settlement statement. You need the total cost breakdown by component. The engineer or cost seg professional walks the property, photographs everything, and categorizes each element according to IRS guidelines. Personal property gets the shortest recovery periods. Land improvements come next. Then the building structure itself, which stays on the long schedule. Here's where people get tripped up. The study doesn't change your accounting book depreciation. It only affects your tax return. So you end up with two depreciation schedules running simultaneously for the same asset. That's intentional. The accelerated write-down shows up on your tax return while your financial statements keep the longer timeline intact. Book-tax differences create deferred tax assets and liabilities that your CPA needs to track.
One specific problem I ran into recently involved a $4.2 million apartment complex in Texas. The property had been purchased in 2019 with an existing cost seg already in place. The new buyer assumed the original study applied automatically. It didn't. The previous owner's study was locked to their basis. When we pulled the 1031 exchange documents and compared the old allocation against the actual current year basis, there was a $340,000 gap between what was being depreciated and what should have been. The fix required a modified study using the rolled-over basis from the exchange, which meant digging through four years of prior depreciation schedules and reconstructing the remaining life on each component. Took about three weeks of back-and-forth with the appraiser and the buyer's CPA. Without that exercise, they were under-depreciating by roughly $18,000 annually across the remaining recovery period.
The Details Most People Miss
Manufactured or modular buildings are a different animal entirely. The IRS has specific guidance on these and some states treat them as personal property rather than real property. If your cost seg firm treats a manufactured housing unit the same way they'd treat a stick-built structure, you're leaving money on the table or creating an audit flag. I had a client with a 48-unit manufactured housing community where the original study categorized every unit as real property. We re-filed with the units split into land, land improvements, and personal property components. The additional acceleration came out to about $220,000 in first-year deductions. Another thing that doesn't get enough attention: the interplay between cost seg and bonus depreciation. Bonus depreciation phases down after 2022. For properties placed in service after 2022, you're looking at 60% bonus in 2023, 40% in 2024, 20% in 2025, and zero going forward. Your cost seg study needs to be planned around this timeline. If you're acquiring a property in 2025 and waiting until 2026 to complete the study, you've lost the ability to front-load the 20% bonus on the 5 and 7-year assets. The study should ideally be completed within 90 days of acquisition or completion of construction. Anything longer and you're working against the clock on bonus depreciation windows. The MACRS tables matter more than you'd think. Most firms default to the standard half-year or mid-month convention. But if your property qualifies, the mid-quarter convention can actually produce a different outcome depending on when components were placed in service during the year. I once saw a situation where switching from half-year to mid-quarter convention on a mixed-use property saved an additional $47,000 in the first year because the personal property components were placed in service in the third quarter.
Get the Full Details
What This Method Cannot Do
A cost seg study will not protect you from the passive activity loss rules. If you're not a real estate professional under the IRS definition, the accelerated depreciation from your study still flows through as a passive loss. It can offset passive income from other rentals, but it won't offset your W-2 income unless you qualify for the $25,000 rental real estate allowance, and even that phases out at higher income levels. This is the biggest misconception I see. People think a big cost seg study means they can deduct the loss against their salary. It doesn't work that way. It also won't help if you're in a depreciation recapture situation on a sale. The accelerated depreciation you claimed becomes ordinary income upon sale, not capital gain. The 25% depreciation recapture rate on real property and the 28% rate on collectibles-style assets (which applies to some personal property) eat into the benefit. If you're planning to sell within five years, the math changes significantly. The upfront tax savings need to be weighed against the eventual recapture hit. In my experience, cost seg makes the most sense when the ownership horizon is at least seven to ten years. There's also the audit risk factor. The IRS has a dedicated examination program for cost segregation studies. They review a sample every year and have published specific criteria they look for. Studies that rely heavily on engineering percent-completion methods without detailed component-level documentation get flagged more often than studies built on actual vendor invoices and construction estimates. If you're going to do this, keep every receipt, every invoice, and every work order. The study report itself should reference source documents for every line item.
Choosing the Right Approach
There are three main methodologies: the IRS-approved split method, the construction cost approach, and the survey method. The split method uses percentage allocations based on construction cost data from published sources like RSMeans. It's the fastest and cheapest option, usually producing results within two to four weeks and costing between $2,000 and $5,000 for a standard commercial property. The accuracy is reasonable but not precise. The construction cost approach uses actual contractor invoices and supplier quotes. This is more accurate and generally holds up better under IRS scrutiny, but it requires complete and organized construction documentation. If you bought an existing property, this method isn't feasible unless you have detailed cost records from the original build. The survey method, sometimes called the detailed physical inspection method, involves a physical walkthrough with laser measurements and component identification. This is the most thorough and defensible approach but also the most expensive. Expect to pay $5,000 to $15,000 depending on property size and complexity. The resulting report typically generates 15 to 30 percent more first-year depreciation than a split-method study on the same property.
For properties under $500,000 in depreciable basis, the de minimis safe harbor election under IRC Section 1.263(a)-1(f) might be worth considering instead of a full study. You can elect to expense items under $2,500 per invoice or $5,000 if you have an applicable financial statement. This bypasses the need for a formal study altogether and handles a significant portion of what would otherwise go into the 5 and 7-year buckets. The biggest practical bottleneck is timing. Most firms need 4 to 8 weeks from engagement to final report delivery for a standard commercial property. If you're dealing with a 1031 exchange, the report must be completed before you file your tax return for the year of acquisition, or you need to file an amended return afterward. Either way, plan for it months ahead, not weeks.