How the Development Pipeline Actually Works
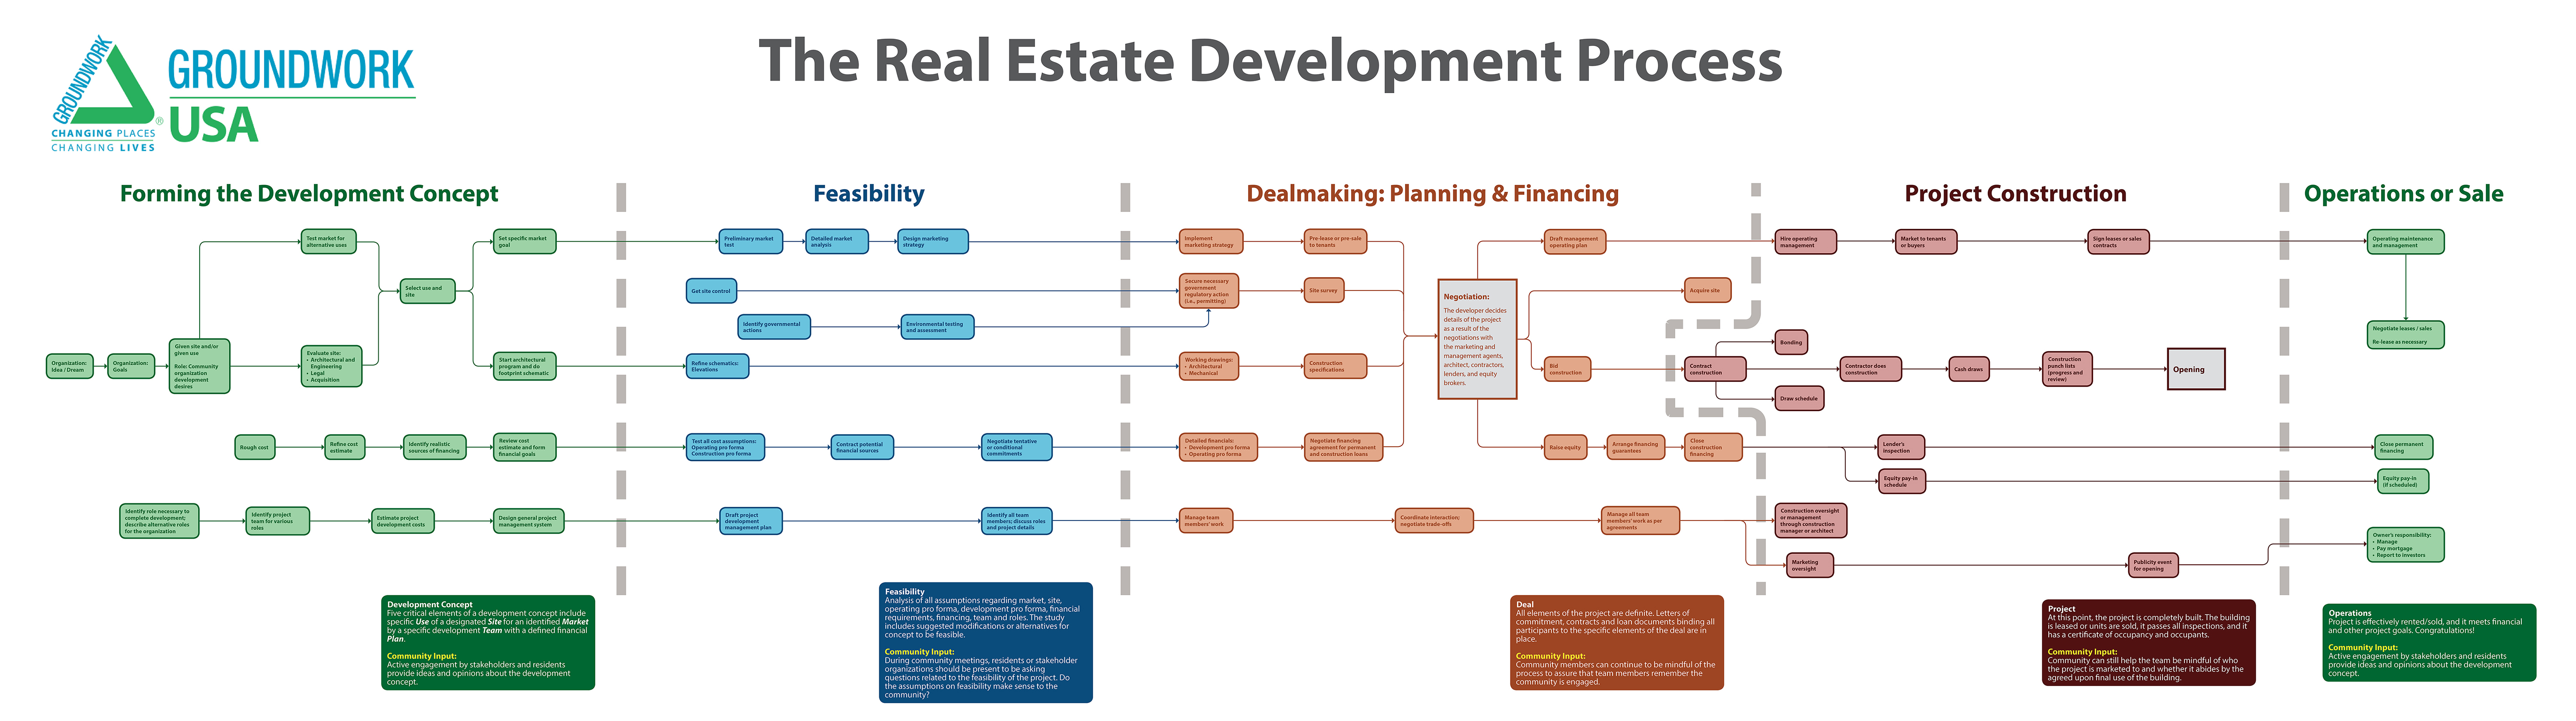
The Real Estate Development Process Step By Step is a lot like watching paint dry, except the paint is millions of dollars and someone's trying to sell you a condo on top of it. I've been through enough ground-ups and repositionings to know the difference between the textbook version and the actual mess that unfolds on the ground. You start with site control, which sounds simple but is where most deals die quietly. I once spent six weeks negotiating option agreements on a parcel that turned out to have a 40-year-old buried fuel tank the county geologist missed. The seller didn't even know. You learn early that you can't trust the Phase 1 environmental report alone. You hire your own consultant, even if it costs an extra $8,000 to $12,000. That money saved me from eating a $2.3 million remediation bill on a mixed-use project in Jersey City. After securing the site, the real work begins: entitlements. This is the part where developers either get smart or get screwed. Zoning changes, variances, special use permits, site plan approvals – each one is a separate proceeding with its own timeline, its own community opposition, and its own unpredictable outcome. I've seen projects sit in zoning board limbo for fourteen months because a single neighbor objected to shadow studies. The workaround? You don't wait until you need the entitlement to talk to the community. I started showing up at local association meetings six months before filing anything. Building relationships with the block council and the commercial tenant group ahead of time cuts opposition time by roughly half, sometimes more.
Then there's design and construction documentation. This stage runs concurrently with entitlements when you're competent about it. You bring the architect on early, not after you have the zoning approval. The reason is straightforward: the architect needs to design within the constraints you're asking the zoning board to give you. If you separate these, you end up redesigning everything after the entitlement comes through, which burns fees and delays the schedule by six to eight weeks on a mid-rise project. Financing sits in the middle of all of this like a nervous parent. You need two separate capital stacks: one for the acquisition and entitlement phase, usually a bridge loan or hard money at 10 to 14 percent, and another for construction, which is typically a CMV or agency loan at 6 to 9 percent depending on the market. The problem is timing. Lenders won't commit until you have entitlements in hand, but you can't get entitlements without proving you can finance the project. It's a circular dependency that kills more deals than anything else. I solved this on a 120-unit development by getting a commitment letter from my construction lender before I even filed the zoning application. They required a pro forma, a feasibility study, and a letter of intent from the general contractor. Once I had those three documents, they wrote a preliminary commitment that satisfied the zoning board's requirement for financial capacity. This took the entitlement clock from an uncertain timeline down to a controlled ninety-day window.
Construction itself is its own nightmare, but the boring truth is that it's mostly just project management with more paperwork. The critical path is foundation, structure, enclosure, and MEP rough-in. Everything else hangs off those four milestones. When one of them slips, everything else slips too. I track progress weekly using a modified critical path method schedule updated in Microsoft Project, and I require the GC to submit look-ahead schedules every Friday. This catches drift before it becomes a crisis. A two-week delay in steel delivery becomes a two-month delay if you don't catch it on a Wednesday. Sales and leasing happen in parallel with construction, not after it. Pre-leasing the ground floor retail before you break ground gives you leverage with the construction lender. It also provides rental income that some lenders will credit toward debt service coverage ratios. On a recent office renovation, pre-leasing 40 percent of the space before construction started moved our DSCR from 1.12 to 1.28, which was the difference between getting the loan and having to bring in additional equity. Stabilization and disposition close the loop. This is where most developers make their money or lose it. The exit strategy matters more than the entry strategy, and I've watched people buy beautiful deals at great prices only to realize three years later they had no clear path to sell or refinance. Know your exit before you know your entry. A partial sale-leaseback, a 1031 exchange, or a sale to a life-science operator are all valid exits that look completely different from the same starting point.
Get the Full Details
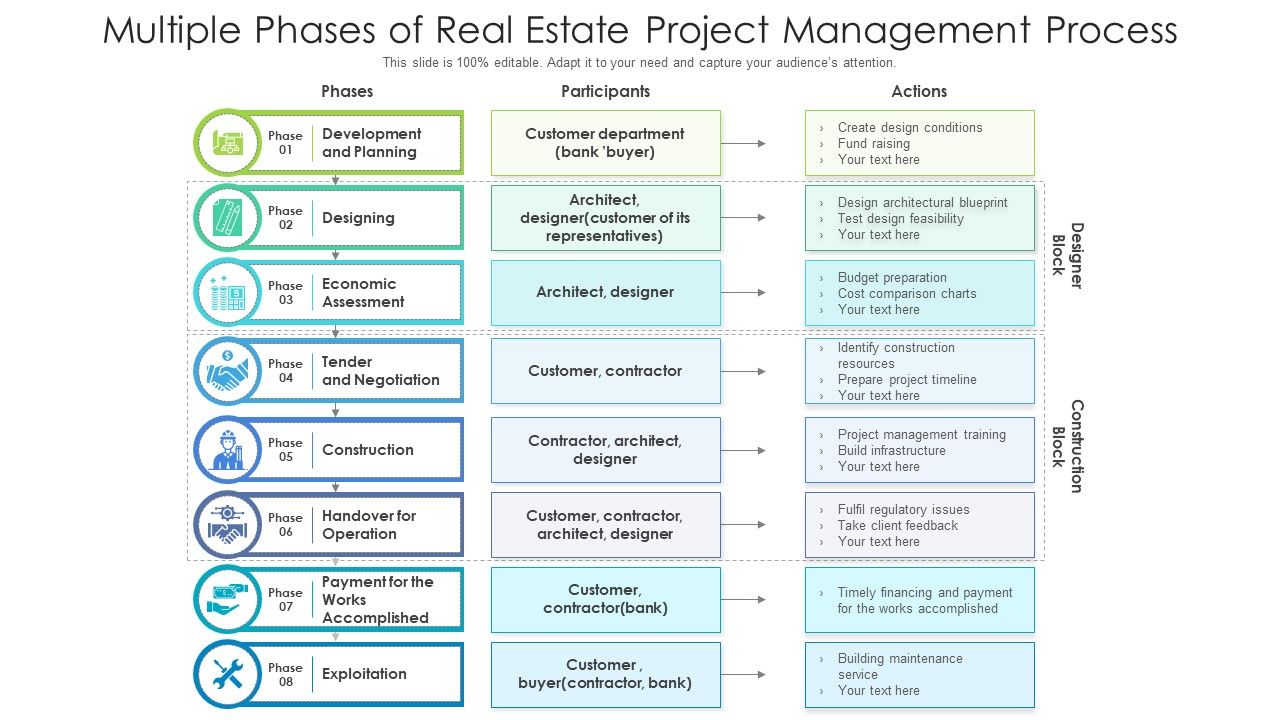
Here's something nobody tells you about this process: the biggest risk isn't construction cost overruns or interest rate spikes. It's the entitlement condition that changes midway through design. I had a project where the zoning board added a pedestrian plaza requirement two weeks after we submitted final plans. That one change cost us $340,000 in redesign fees, delayed groundbreaking by eleven weeks, and ate into our pro forma so badly we had to renegotiate the construction loan terms. The lesson is that you never treat entitlements as a finished product. They're a living document until you punch the certificate of occupancy. The whole thing usually takes eighteen to thirty-six months from site control to stabilized operations on a typical mid-scale project. Anything faster than that involves either luck, connections, or pre-existing zoning that someone hasn't challenged yet. And even then, you're probably cutting corners somewhere that will come back to bite you later.