Most people skip the boring parts and lose money because of it
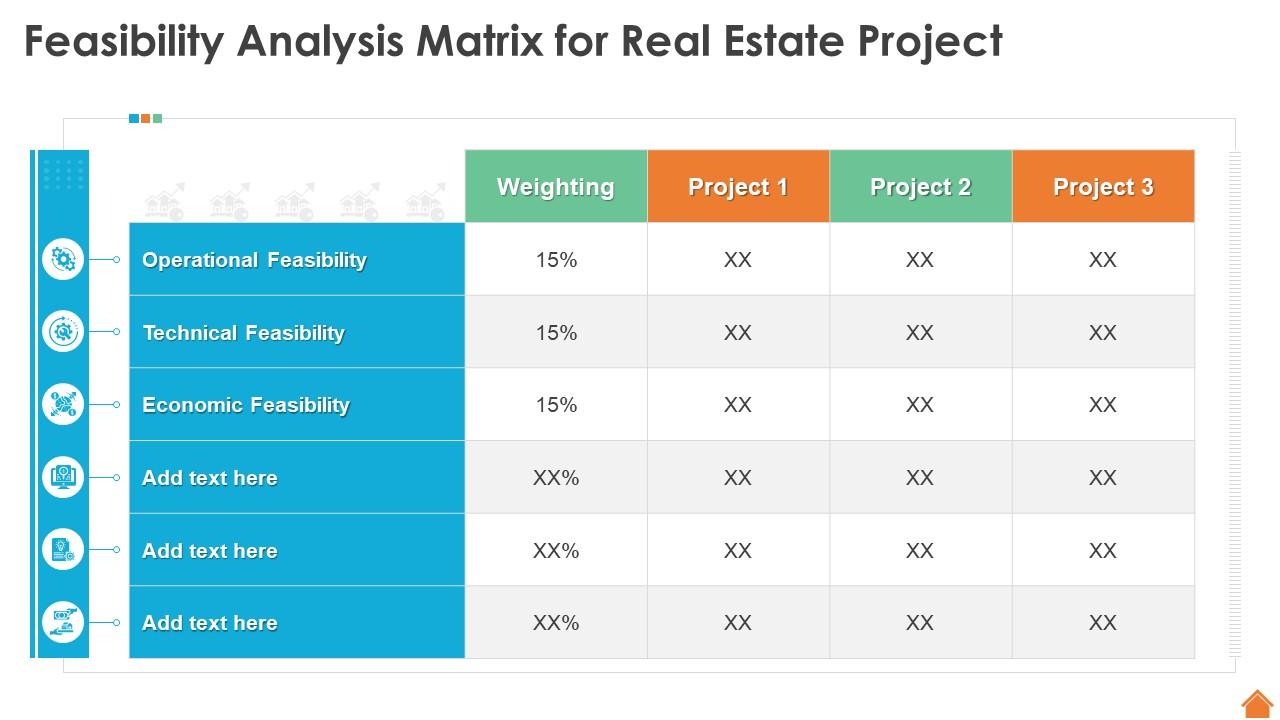
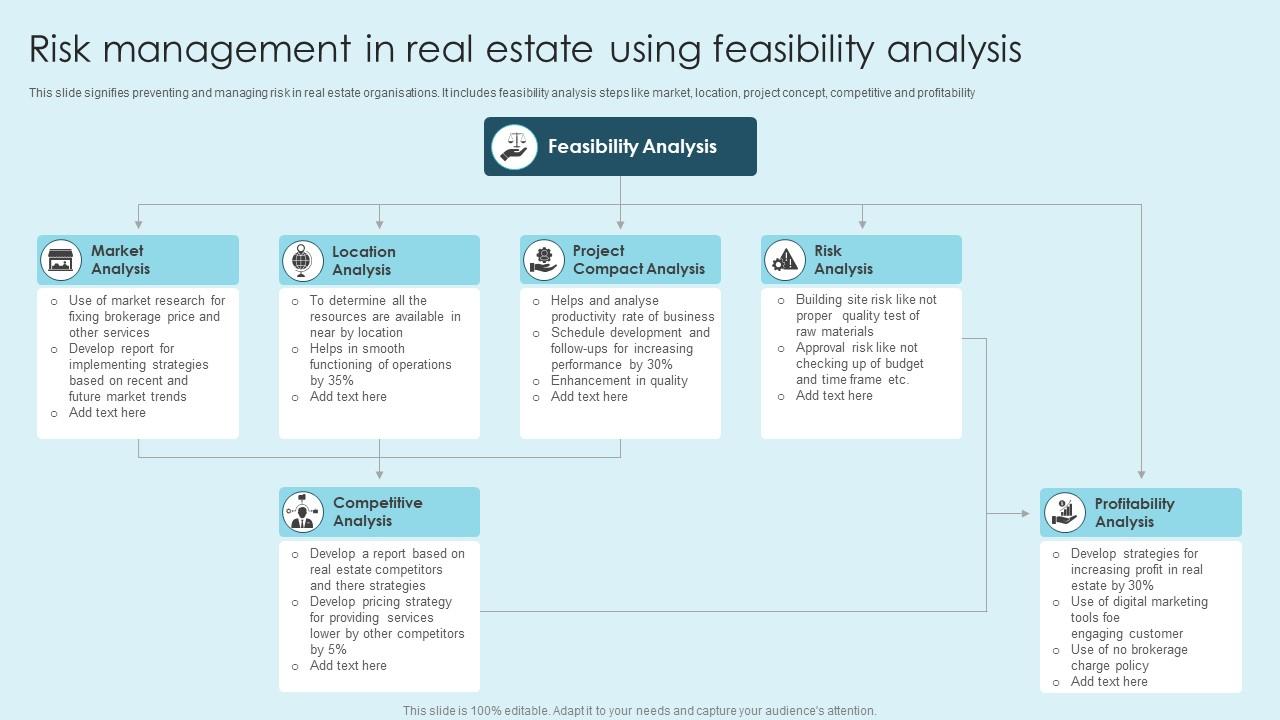
A Real Estate Feasibility Analysis is just a structured way of answering whether a deal works before you get emotionally attached to it. You plug in numbers, check the results, and then decide if the project moves forward or dies quietly. That is the entire concept. What makes it hard in practice is not the concept, it is the details that show up when you actually try to build the model. Start with the income approach. Estimate gross potential rent, subtract vacancy and credit loss, add other income like parking or laundry, and you have effective gross income. From there, subtract operating expenses to get net operating income. Operating expenses are where most people mess up. They forget property management fees, they forget capital expenditures, or they assume the HVAC system will last fifteen years when it actually lasts eight in a high-use building. Then you cap that NOI with a market-derived capitalization rate to get value, or you run a discounted cash flow model if the property has a hold period longer than five years. The cost approach matters more for special-purpose properties or ground-up development. You take the land value, add hard construction costs, add soft costs like permits and architecture and legal fees, then subtract physical depreciation and functional obsolescence. Hard costs in 2024 and 2025 are still nowhere near pre-pandemic levels. A student housing project in the Midwest might run $280 to $340 per square foot depending on finishes and site conditions. In coastal markets you can easily be $500 to $750 per square foot. If your pro forma does not reflect current contractor bids, you are working with fiction.
The sales comparison approach is simpler but also more dangerous if used alone. You find three to five comparable recent transactions, adjust for differences in size, condition, and location, and derive a per-unit or per-square-foot value. The trap here is choosing comps that are too old or too distant. A sale from eighteen months ago in a shifting market can be $15 per square foot off. That difference multiplies across fifty units and becomes a quarter million dollars of error. I learned this the hard way on a mixed-use infill project in a secondary Texas market. The zoning allowed residential above retail, so I built a pro forma assuming 85 percent residential occupancy and 70 percent retail occupancy. Standard assumptions, nothing exotic. Two months into the underwriting, I pulled actual lease rates from broker listings and realized the retail space was absorbing at 40 percent with two-year rent abatement being the only way to move units. My original model showed a positive spread. The corrected model showed a negative spread of twelve percent at target returns. I killed the deal before going to term sheet. It saved maybe two hundred thousand dollars in carrying costs and professional fees. The lesson was not that the math was wrong. The lesson was that I should never have trusted market rental estimates without pulling actual lease comps from brokers who had signed those deals in the last six months.
What goes into a practical pro forma
A workable spreadsheet model needs revenue lines, expense lines, debt service, and a return calculation. Revenue lines should include market rent multiplied by occupied units, phased appropriately if you have a lease-up period. Expense lines should separate operating expenses from capital expenditures. Debt service is your loan payment based on the assumed interest rate and amortization period. Your return metrics are usually cash-on-cash return, internal rate of return, and equity multiple. I also track the debt service coverage ratio because lenders care about that number before they care about your IRR. Vacancy rates should not come from a textbook. They should come from property management firms that manage buildings in your submarket. A property management firm will tell you their portfolio average vacancy is 7.2 percent this quarter. You use that number, not the 5 percent assumption from a 2019 report. Same thing for expense growth. Properties typically see 2 to 4 percent annual expense escalation in stable markets and 4 to 7 percent in markets with rising insurance and labor costs. Insurance premiums alone jumped significantly in Florida and California over the last three years. Ignoring that in a long hold model is a reliable way to lose money.
Get the Full Details

Common pitfalls that sink deals quietly
The biggest problem I see is scope mismatch. People run a light feasibility analysis on a billion-dollar project or a full five-statement model on a small multifamily fix-and-flip. The first one wastes time because the assumptions are shallow. The second one creates false confidence because the model looks detailed but is missing critical inputs like remediation costs or entitlement timelines. Match the depth of the analysis to the size and complexity of the deal. A simple office building reposition might need three pages of assumptions and a basic returns summary. A twelve-story mixed-use development needs a full model with phased construction draws, leasing curves, and sensitivity tables. Another pitfall is ignoring timing. Development takes longer than anyone expects. I have seen pro formas assume a twelve-month construction period for a project that required eighteen months because of permitting delays and supply chain issues. That extra six months means six more months of interest carry, property taxes, and insurance with no rent coming in. The IRR drops enough to make the deal unfeasible even though the underlying numbers looked fine on paper. Condo conversion deals are a special category that deserves its own warning. The math looks attractive because you are selling units instead of holding them, but the exit assumptions are fragile. You need to know the selling price per unit, the absorption rate, and the cost of condo documentation and legal fees before you commit. A lot of people forget that condo conversions require a condo regime approval process that can take three to nine months depending on the municipality. That timeline affects your financing and your exit strategy simultaneously.
Sensitivity analysis is not optional
Build a sensitivity table that shows how returns change when key assumptions move. Rent decreases by 5 percent. Expenses increase by 10 percent. Vacancy stays at 12 percent for eighteen months. Interest rates go up by 200 basis points. If the deal breaks under any of those scenarios, you need to know before you underwrite it seriously. I use a simple tornado diagram in my head when I am reviewing deals quickly, but for anything that will go to an investment committee, I build an actual sensitivity matrix in the spreadsheet. It takes about ten minutes once the base model is solid, and it prevents embarrassing moments when a lender asks what happens if the market turns. Sometimes the numbers cannot save a deal and you need to walk away early. This happens most often with special-purpose properties like self-storage in oversupplied submarkets or needlecare facilities in areas with restrictive zoning. The cap rate compression you need to justify the purchase price does not exist because the market has too much supply. A feasibility analysis will show a negative return no matter how efficiently you operate the asset. In those cases, the model is telling you something important. The problem is not the management plan. The problem is the market structure. Stop trying to make the numbers work and look for a different asset class or a different geography. Another scenario where this breaks down is when you do not have access to real data. If you are analyzing a niche asset type in a market where you have never operated, your assumptions become guesses dressed up as facts. An industrial logistics building in a rust belt city might look great on paper if you assume current market rents from a different region. They will not translate. The only honest answer in that situation is to either get a market study from a local consulting firm or walk away until you have better information. A feasibility analysis built on bad input produces bad output every single time, regardless of how sophisticated the model is.
Where to get the tools and templates
Most investors build their own models or adapt existing ones from professional services. Commercial mortgage bankers and investment banks provide template pro formas to their clients. Some real estate software platforms like Yardi, MRI, and Argus offer modeling capabilities, though they are designed more for portfolio-level analysis than individual deal underwriting. For ground-up development, a lot of people use custom Excel models or tools like Reonomy for market research combined with a standalone financial model. There is no single industry-standard template that works for every deal type, so the model you use should reflect the specific asset class and strategy you are pursuing. If you want a starting point, the best approach is to take a simple four-statement model, add revenue and expense lines that match your asset type, and layer in a debt schedule and return calculations. Start with a multifamily property because the cash flow pattern is predictable and the data is widely available. Once you understand how vacancy, expenses, and debt service interact in a basic model, you can adapt it for commercial, industrial, or mixed-use deals. The core mechanics do not change significantly between asset classes. Only the assumptions change, and those come from local market knowledge, not from the model structure itself. Running a thorough Real Estate Feasibility Analysis on every deal before you commit capital is the difference between building a portfolio and accumulating regret. The work is tedious. The models are never perfect. But the cost of skipping it is always higher than the cost of doing it.