Getting Started with Real Estate Formulas
What Is a Real Estate Formulas Cheat Sheet?
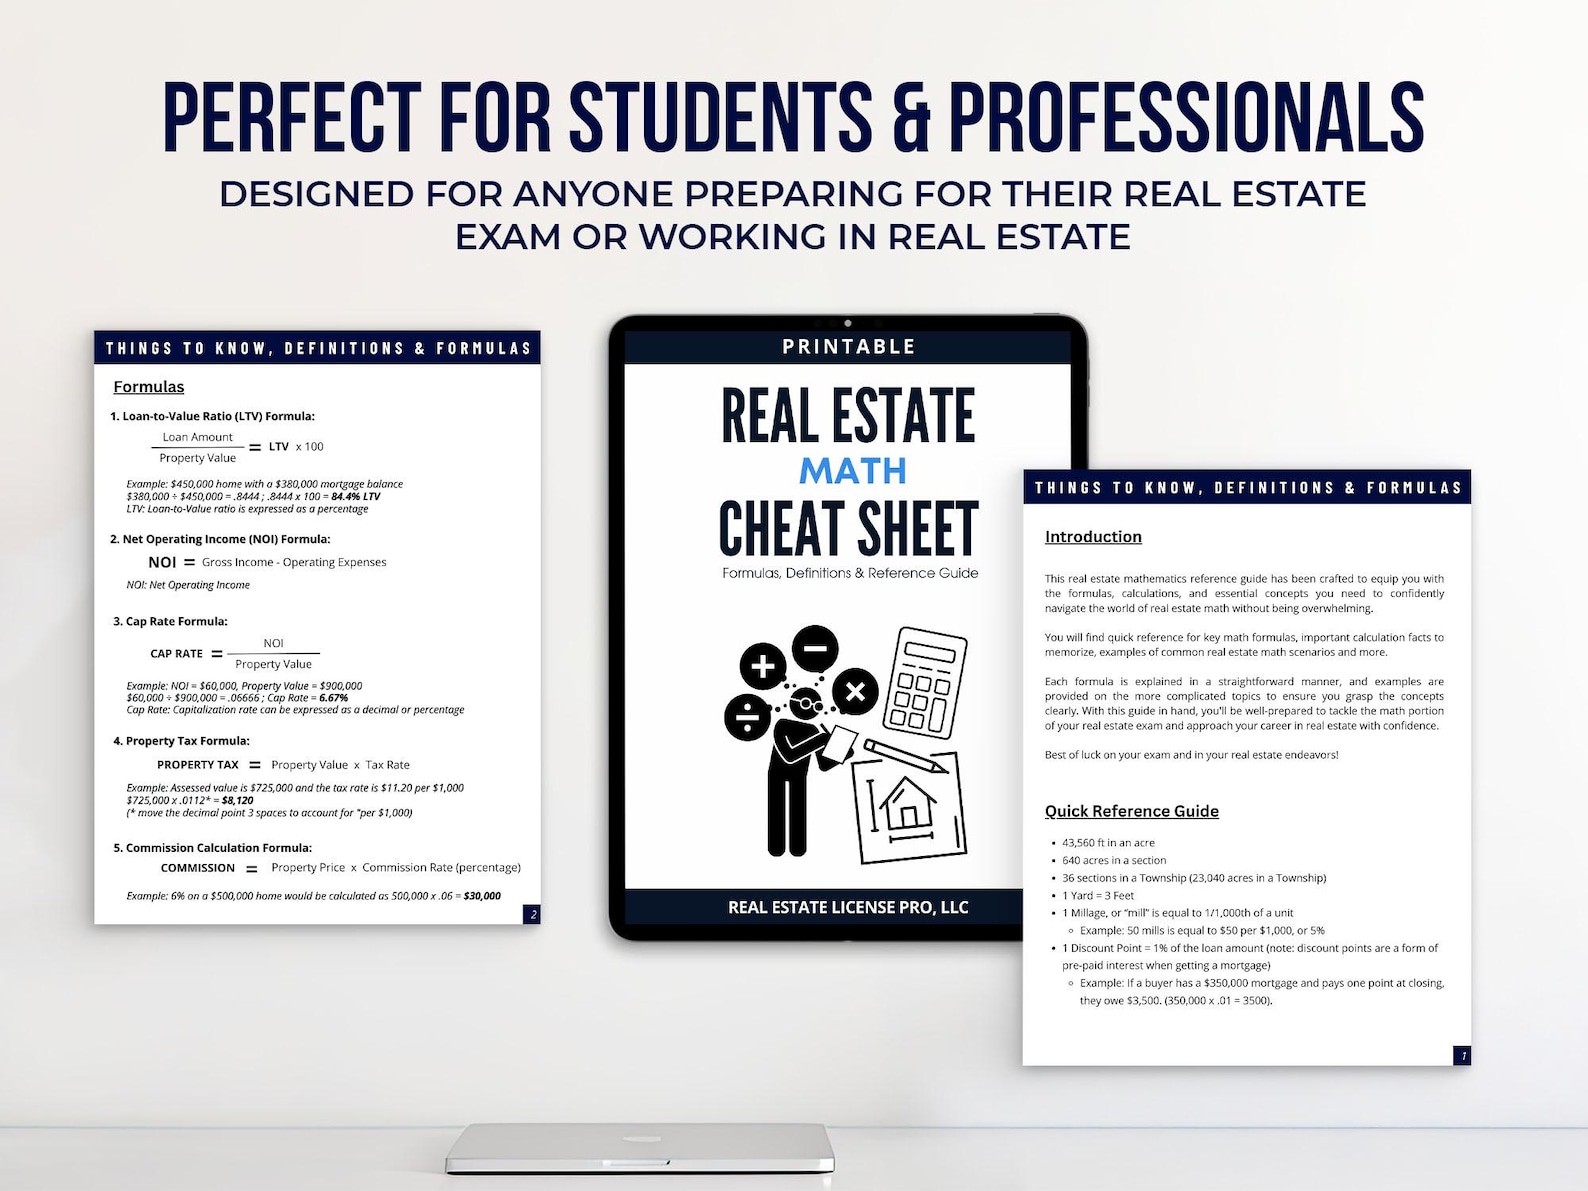
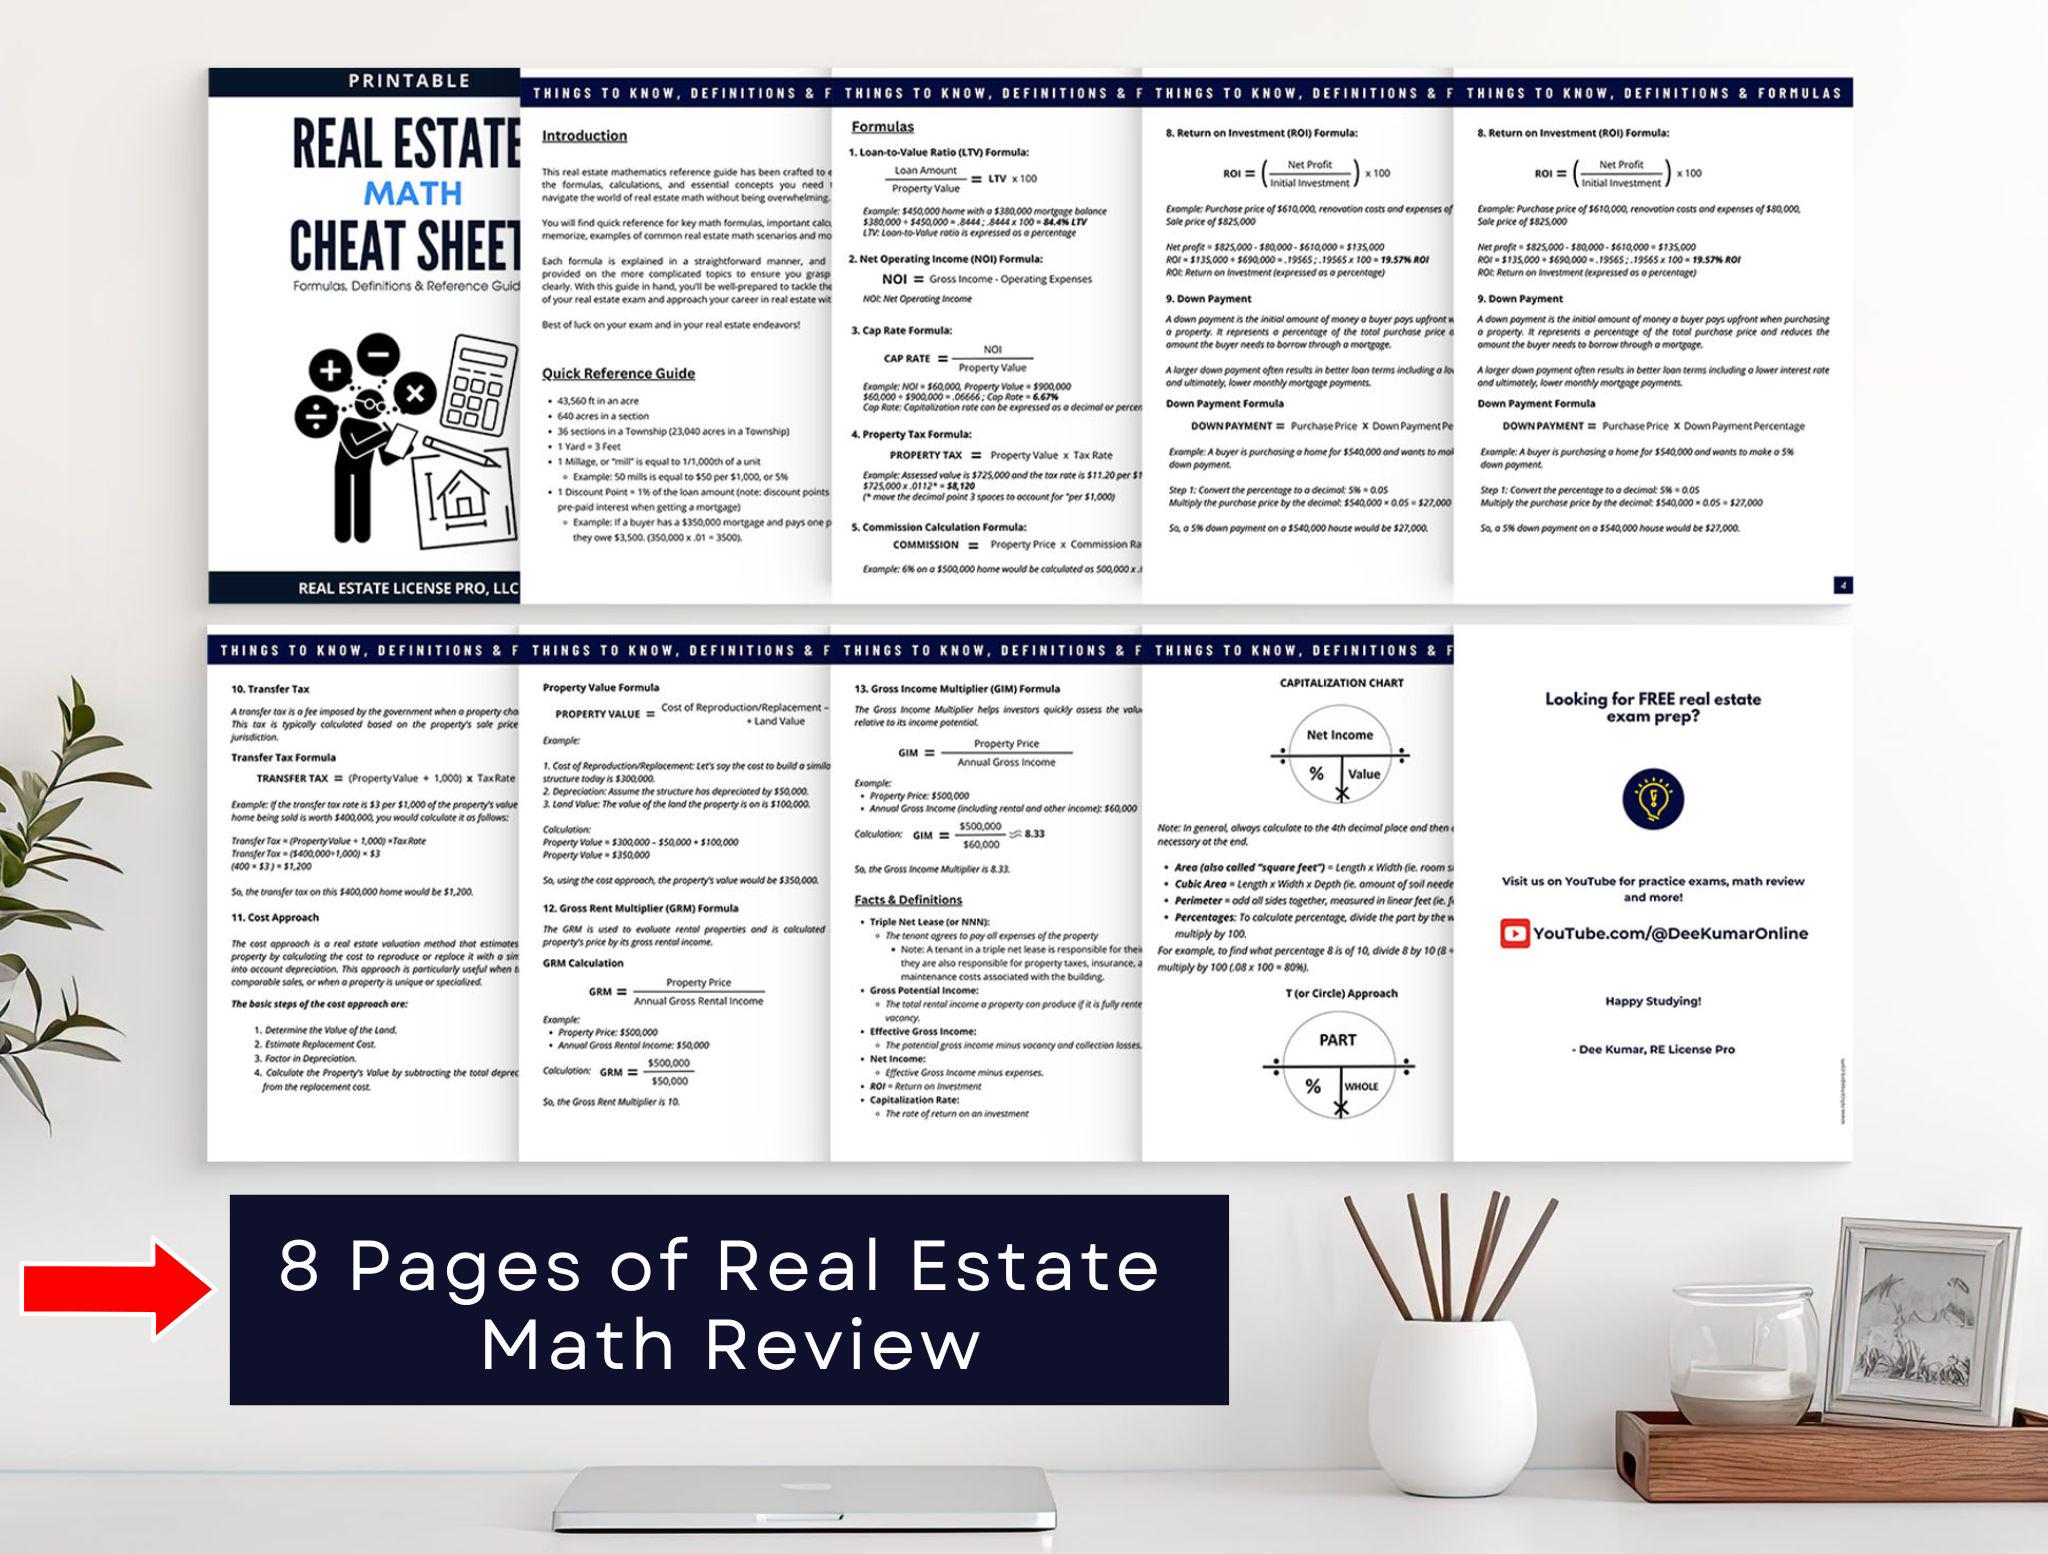
A Real Estate Formulas Cheat Sheet is essentially a one-page reference that consolidates the math you actually use when evaluating properties. Cap rate, cash-on-cash return, gross rent multiplier, debt service coverage ratio, internal rate of return. The ones that matter, laid out with the variables clearly labeled so you don't have to derive them from scratch every time you're staring at a spreadsheet at 10 PM. I keep mine tucked into Notion and occasionally pull it up when I'm underwriting a multifamily deal and need to verify whether I've been calculating NOI correctly. It saves maybe ten minutes per deal, but those ten minutes prevent bigger mistakes downstream.
The Core Formulas You Actually Need
Cap rate is the simplest one and the most misunderstood. It's Net Operating Income divided by property value or purchase price. The tricky part is knowing what goes into NOI. You strip out mortgage payments, depreciation, and capital expenditures, but you keep property taxes, insurance, management fees, repairs, and utilities. If you include the debt service in there, your cap rate is wrong and you'll make a bad decision. Here's the thing nobody tells beginners: cap rate doesn't account for appreciation, financing structure, or future value changes. Two identical buildings in different neighborhoods can have the same cap rate but wildly different risk profiles. I learned this the hard way back in 2019 when I was underwriting a small multifamily in the Southwest. The seller quoted a 7.2% cap rate and everything looked clean on paper. What they left out was that the property had two major roof systems and a parking lot that needed resurfacing within eighteen months. Once I factored in roughly $140,000 in deferred maintenance spread across the remaining hold period, the effective cap rate dropped to around 5.8%. Not deal-breaking, but enough to change my offer by nearly $80,000. I started requiring a minimum five-year capital expenditure schedule before running any cap rate calculation after that. Cash-on-cash return measures the annual pre-tax cash flow against the total cash invested. That includes your down payment, closing costs, and any immediate rehab expenses. The formula is straightforward, but people routinely forget to include closing costs and rehab in the denominator, which inflates their return. A 15% cash-on-cash look impressive until you realize you left out $25,000 in renovation costs that you had to cover out of pocket.
Debt service coverage ratio comes from the lender's world. It's NOI divided by annual debt service. Most conventional lenders want to see a DSCR of 1.25 or higher. Below that and you're either putting more equity down or the deal doesn't qualify. Some portfolio lenders will go to 1.10, but the rate will be steeper. This ratio matters more than cap rate for determining whether a deal actually qualifies for financing, not just whether it looks good on paper. Gross rent multiplier is purchase price divided by gross annual rental income. It's a quick screening tool, not a due diligence tool. Use it to filter listings, not to decide whether to write an offer. GRM ignores operating expenses entirely, so a property with a low GRM could still be a money loser if expenses are high. For IRR calculations, you need a spreadsheet. There's no shortcut formula that works in your head because IRR is iterative. You feed it the initial investment, each year's cash flow, and the eventual sale proceeds, and Excel's XIRR function gives you the annualized return. If you're doing this manually, you're going to waste an hour and get the number wrong.
Get the Full Details
Building Your Own Reference
Download or create a simple Google Sheet. Put each formula in its own row with the formula on the left and the calculation on the right. Add notes columns for common adjustments like when to use gross income versus effective gross income, or when to annualize monthly expenses. I structure mine with a definitions section, the formulas themselves, and a sample deal walkthrough at the bottom. The walkthrough is where the whole thing pays off because it shows you how the numbers connect. One edge case that trips people up consistently: treating tenant-paid utilities as part of NOI. If the landlord pays water and trash but the tenants pay electric, those utility reimbursements count as income. But if the tenant pays electric directly to the utility company, it's not your income and it shouldn't be in the calculation. I've seen analysts include both and inflate NOI by 3 to 5 percent, which translates to hundreds of thousands of dollars on a $2 million deal. Another nuance that matters: vacancy and credit loss should be estimated separately. Don't just apply a flat 5% vacancy rate across the board. Class B multifamily in a stable market might run 3 to 4 percent. A retail property in a declining trade area could be 8 to 10 percent. The difference between 4% and 8% vacancy on $200,000 in annual rent is $8,000 in NOI, which shifts your cap rate by about 0.4 percentage points on a $3 million property.
When These Formulas Break Down
The biggest limitation is that all of these metrics look backward or assume forward conditions match the past. They don't capture local market dynamics, regulatory risk, or sudden changes in expense ratios. A property that has carried a 4.2% property tax rate for a decade could face a reassessment that pushes it to 5.5%. Your cap rate calculation becomes irrelevant overnight. For value-add deals with significant renovation plans, cap rate and DSCR based on current numbers will mislead you. You need to model pro forma NOI after stabilization, which means estimating rent increases, expense changes, and lease-up timelines separately. If you're doing this for multiple properties simultaneously, a cheat sheet alone won't cut it. You'll need a dynamic underwriting model with scenario toggles for best case, base case, and worst case. Gross rent multiplier falls apart completely in markets where some units are month-to-month and others have long-term leases at below-market rates. The gross income number becomes meaningless without understanding lease expirations. Same problem with single-tenant net leased properties where the rent escalations are built into the lease structure rather than market-driven.
If you're analyzing syndication deals or commercial mortgages with balloon payments, you need to factor in the re-financing risk. A deal that shows a healthy cash-on-cash return in years one through three might collapse in year four when the loan matures and rates have shifted. The formulas on your cheat sheet don't address this. You need to layer in a maturity wall analysis on top of everything else.
Quick Reference Summary
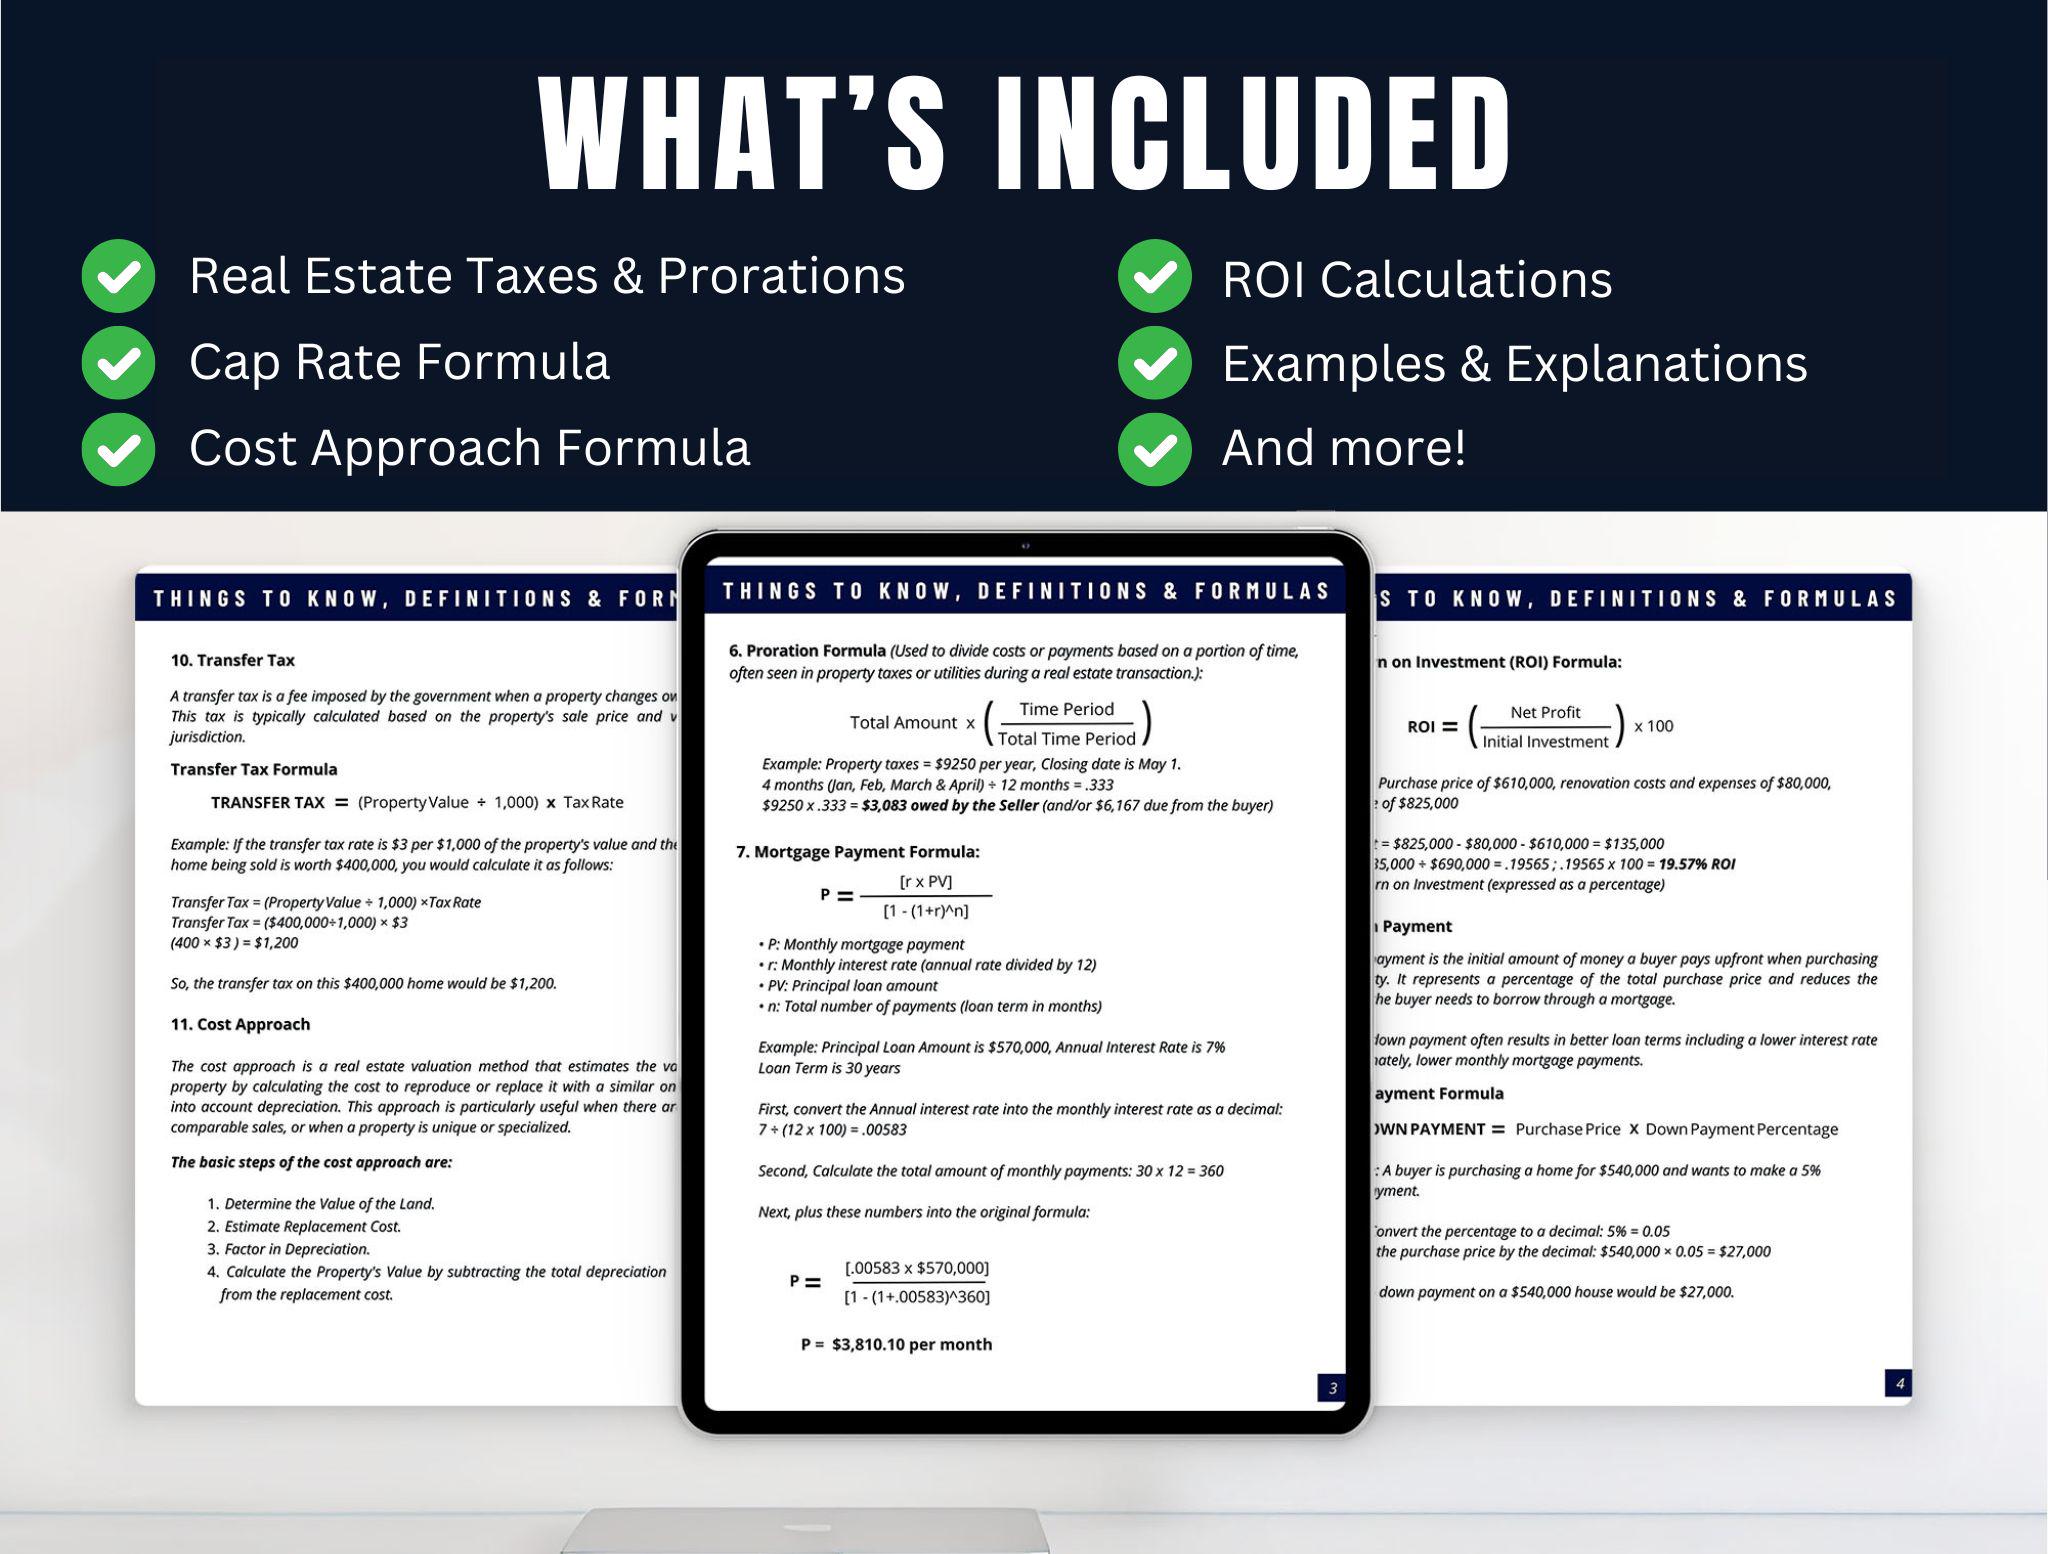
Cap rate = NOI / Property Value. Use for comparing similar properties in the same market. Ignore financing effects. Don't use it for value-add deals. Cash-on-cash = Annual Pre-Tax Cash Flow / Total Cash Invested. Include down payment, closing costs, and rehab in the cash invested. Don't forget them or your return looks better than it is. DSCR = NOI / Annual Debt Service. Lenders care about this. Aim for 1.25 minimum on conventional loans. Check local lender requirements before assuming a standard threshold applies.
GRM = Purchase Price / Gross Annual Rental Income. Quick screening only. Never use it for final underwriting. IRR = Requires a spreadsheet. Feed it all cash flows including sale proceeds. Use XIRR if dates are irregular. Manual calculation is not worth the effort. NOI = Gross Potential Income minus Vacancy and Credit Loss minus Operating Expenses. Operating Expenses exclude debt service, depreciation, and income taxes. Include property management, repairs, insurance, property taxes, utilities paid by owner, and landscaping.
Keep your cheat sheet updated. Market conditions shift, lender requirements change, and new expense categories pop up in deals you haven't seen before. A static document gets stale within a year if you're actively closing deals.