Why most people fail the real estate exam isn't what you think
It's not the math itself. It's that they're studying formulas they never actually use. I've sat through more exam prep sessions than I care to count, watching people memorize half a dozen different formulas for commission splits, then completely blank when a question asks them to back into the rate instead of forward. Here's what actually matters. You need to understand the relationships between the variables, not just memorize which letter goes where on the equation sheet.
Mastering Real Estate Formulas For Exam
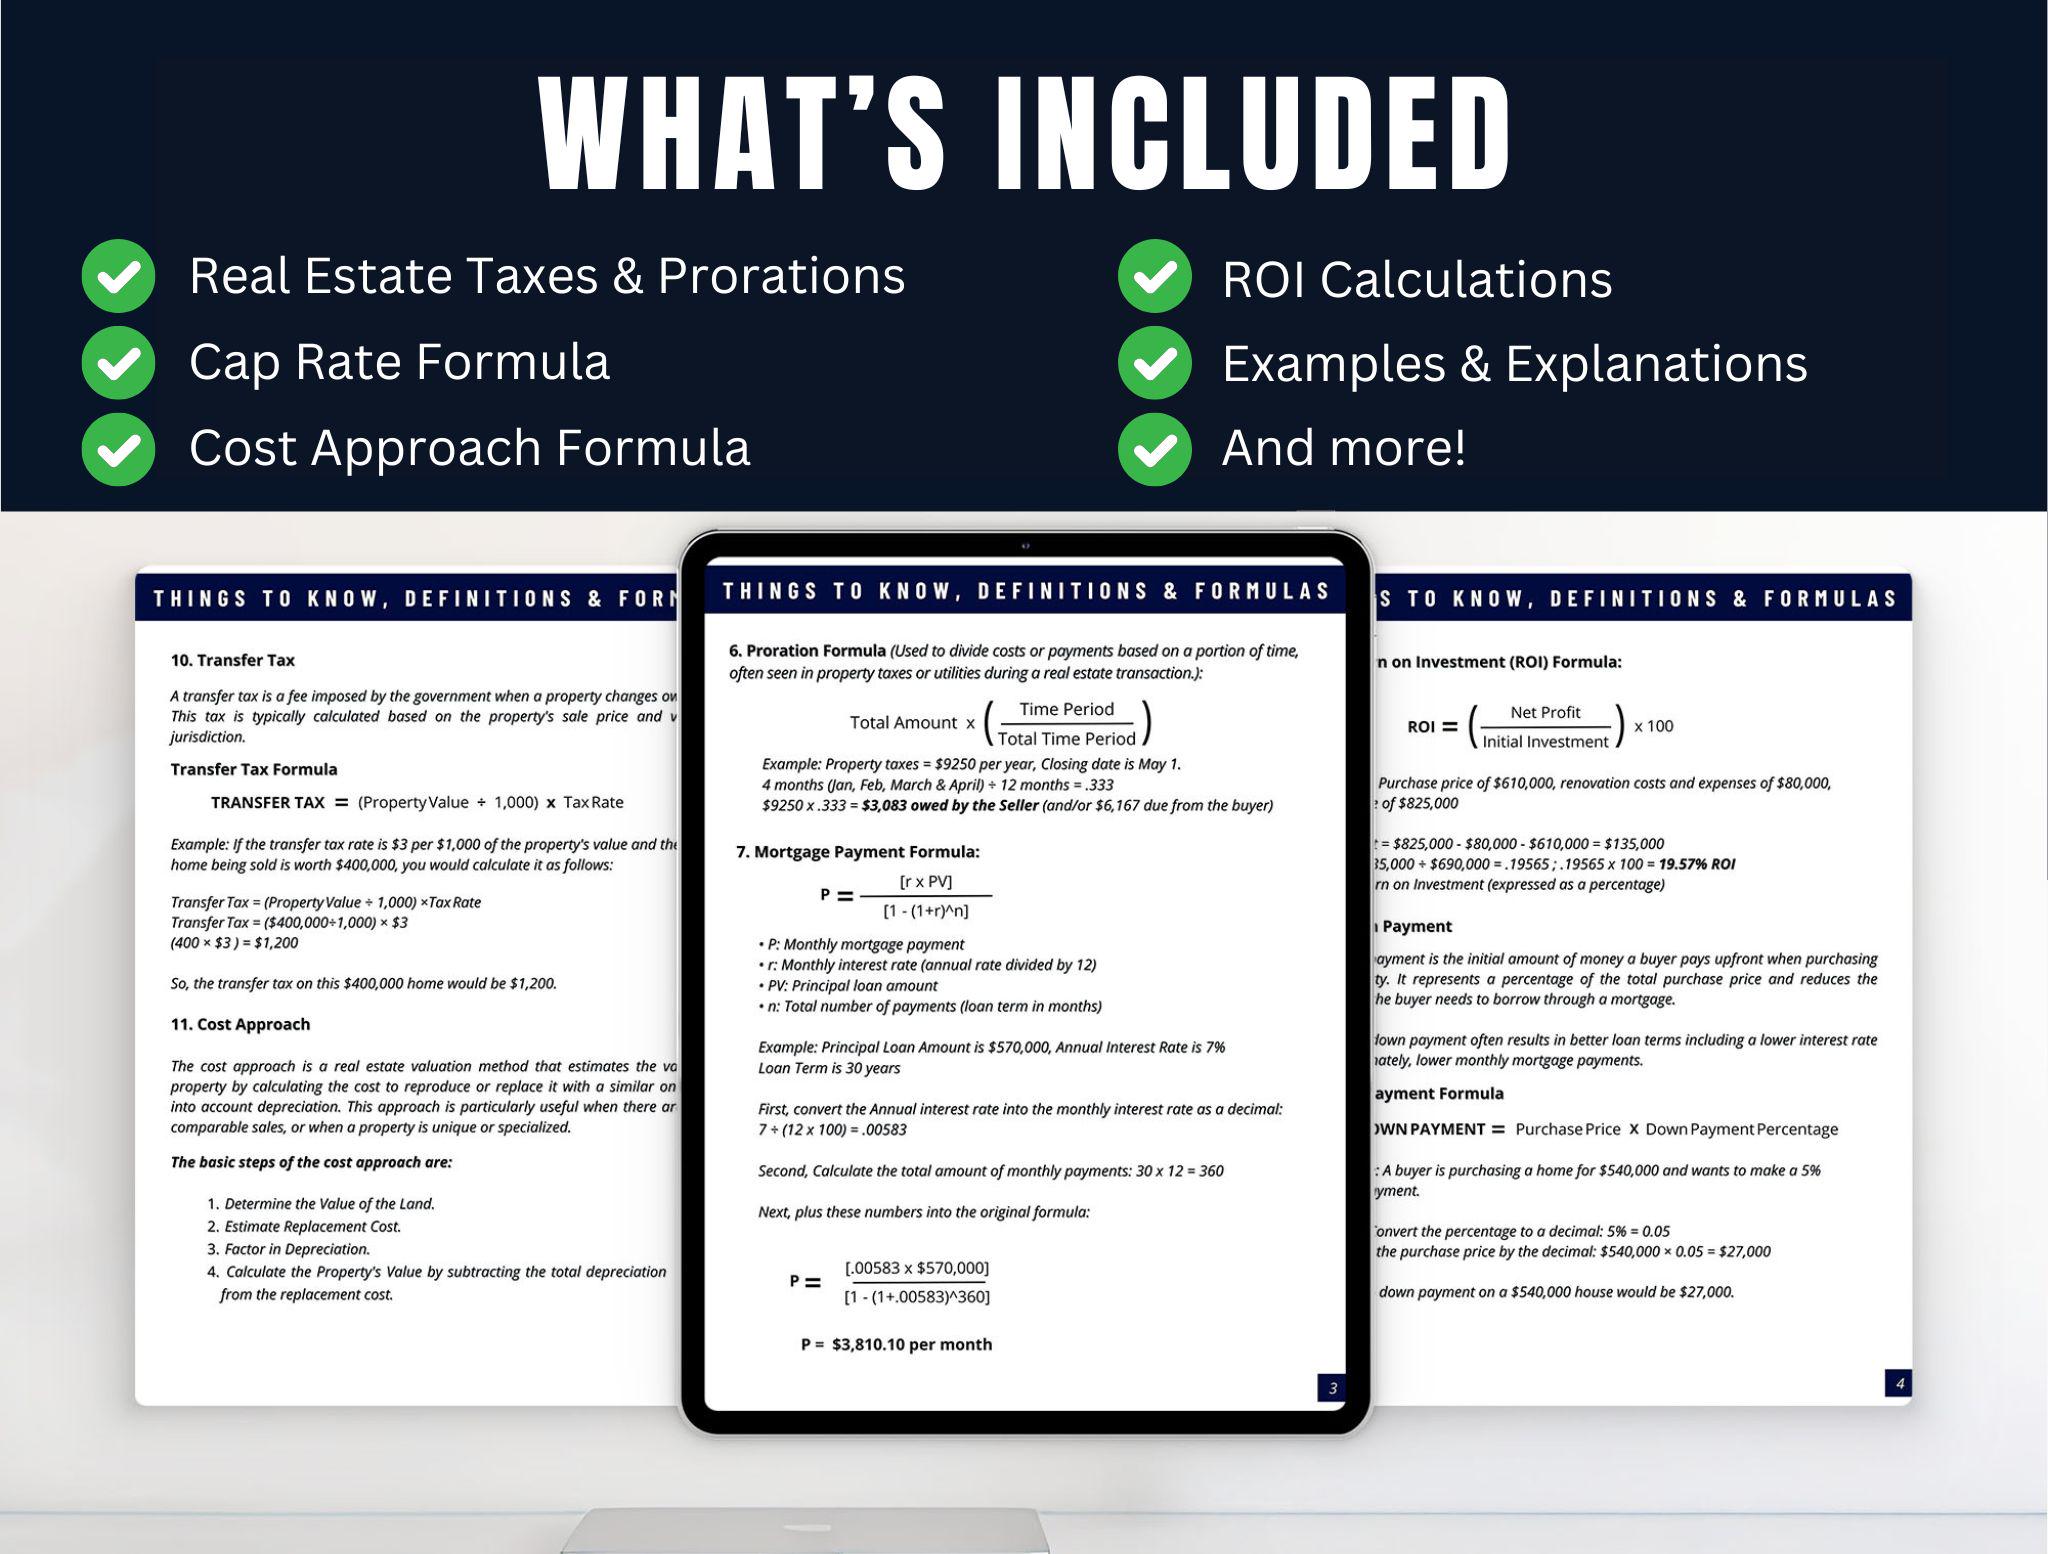
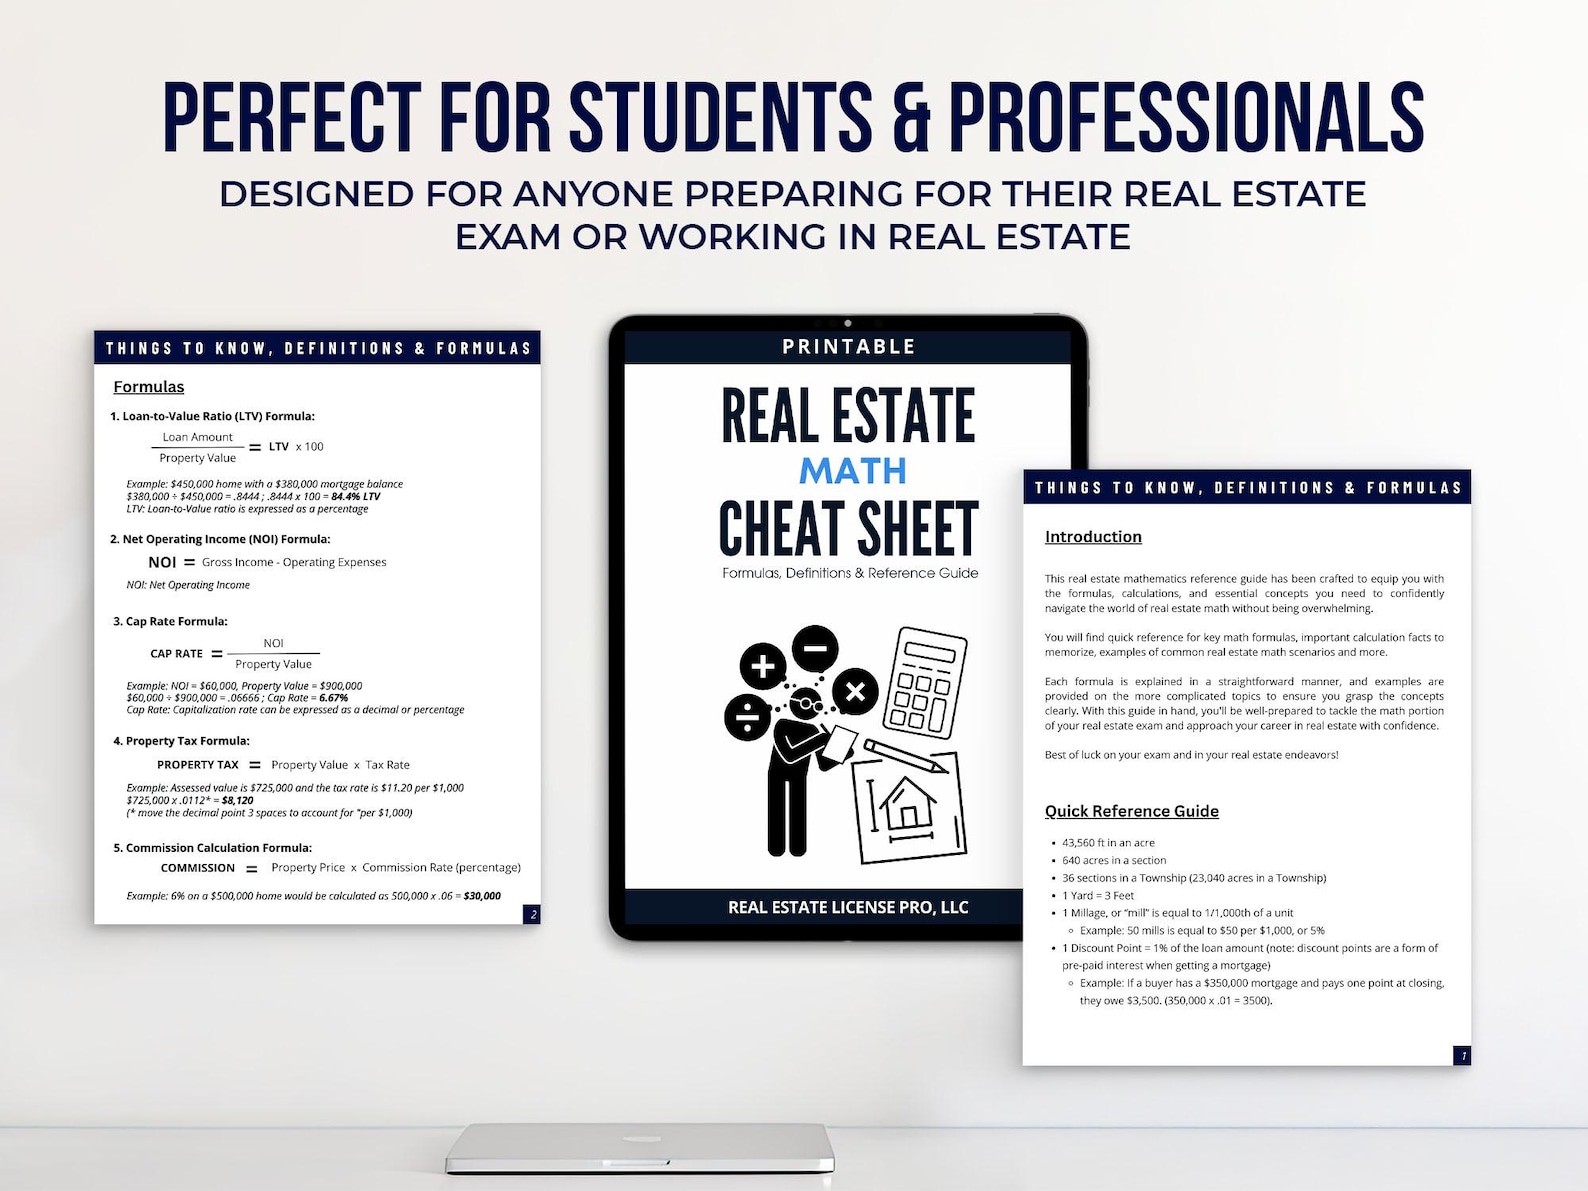
Let me walk you through the ones you'll actually see, and the ones you'll second-guess because the question is worded sideways. Commission Formula: Sale Price × Rate = Commission. Simple, right? The trap is when they give you the commission and ask for the rate, or give you the rate and ask for the price. You have to be comfortable rearranging. If the commission is $12,000 on a $240,000 sale, the rate is Commission ÷ Sale Price. That's 5%. Don't overthink it. Test writers love to swap the knowns around so you have to solve for the missing piece. Price Per Square Foot: Total Price ÷ Square Footage = Price Per Sq Ft. This shows up in almost every exam I've seen. The edge case is when they give you the price per square foot and ask for the total price of a property described in acres or lots rather than just straight square footage. I had a student once who froze on a question because they gave the lot size in acres and the price per square foot. She needed to convert acres to square feet first (1 acre = 43,560 sq ft), multiply by the price per sq ft, and then divide by the number of lots. Took her five minutes once she saw it, but she blanked under pressure.
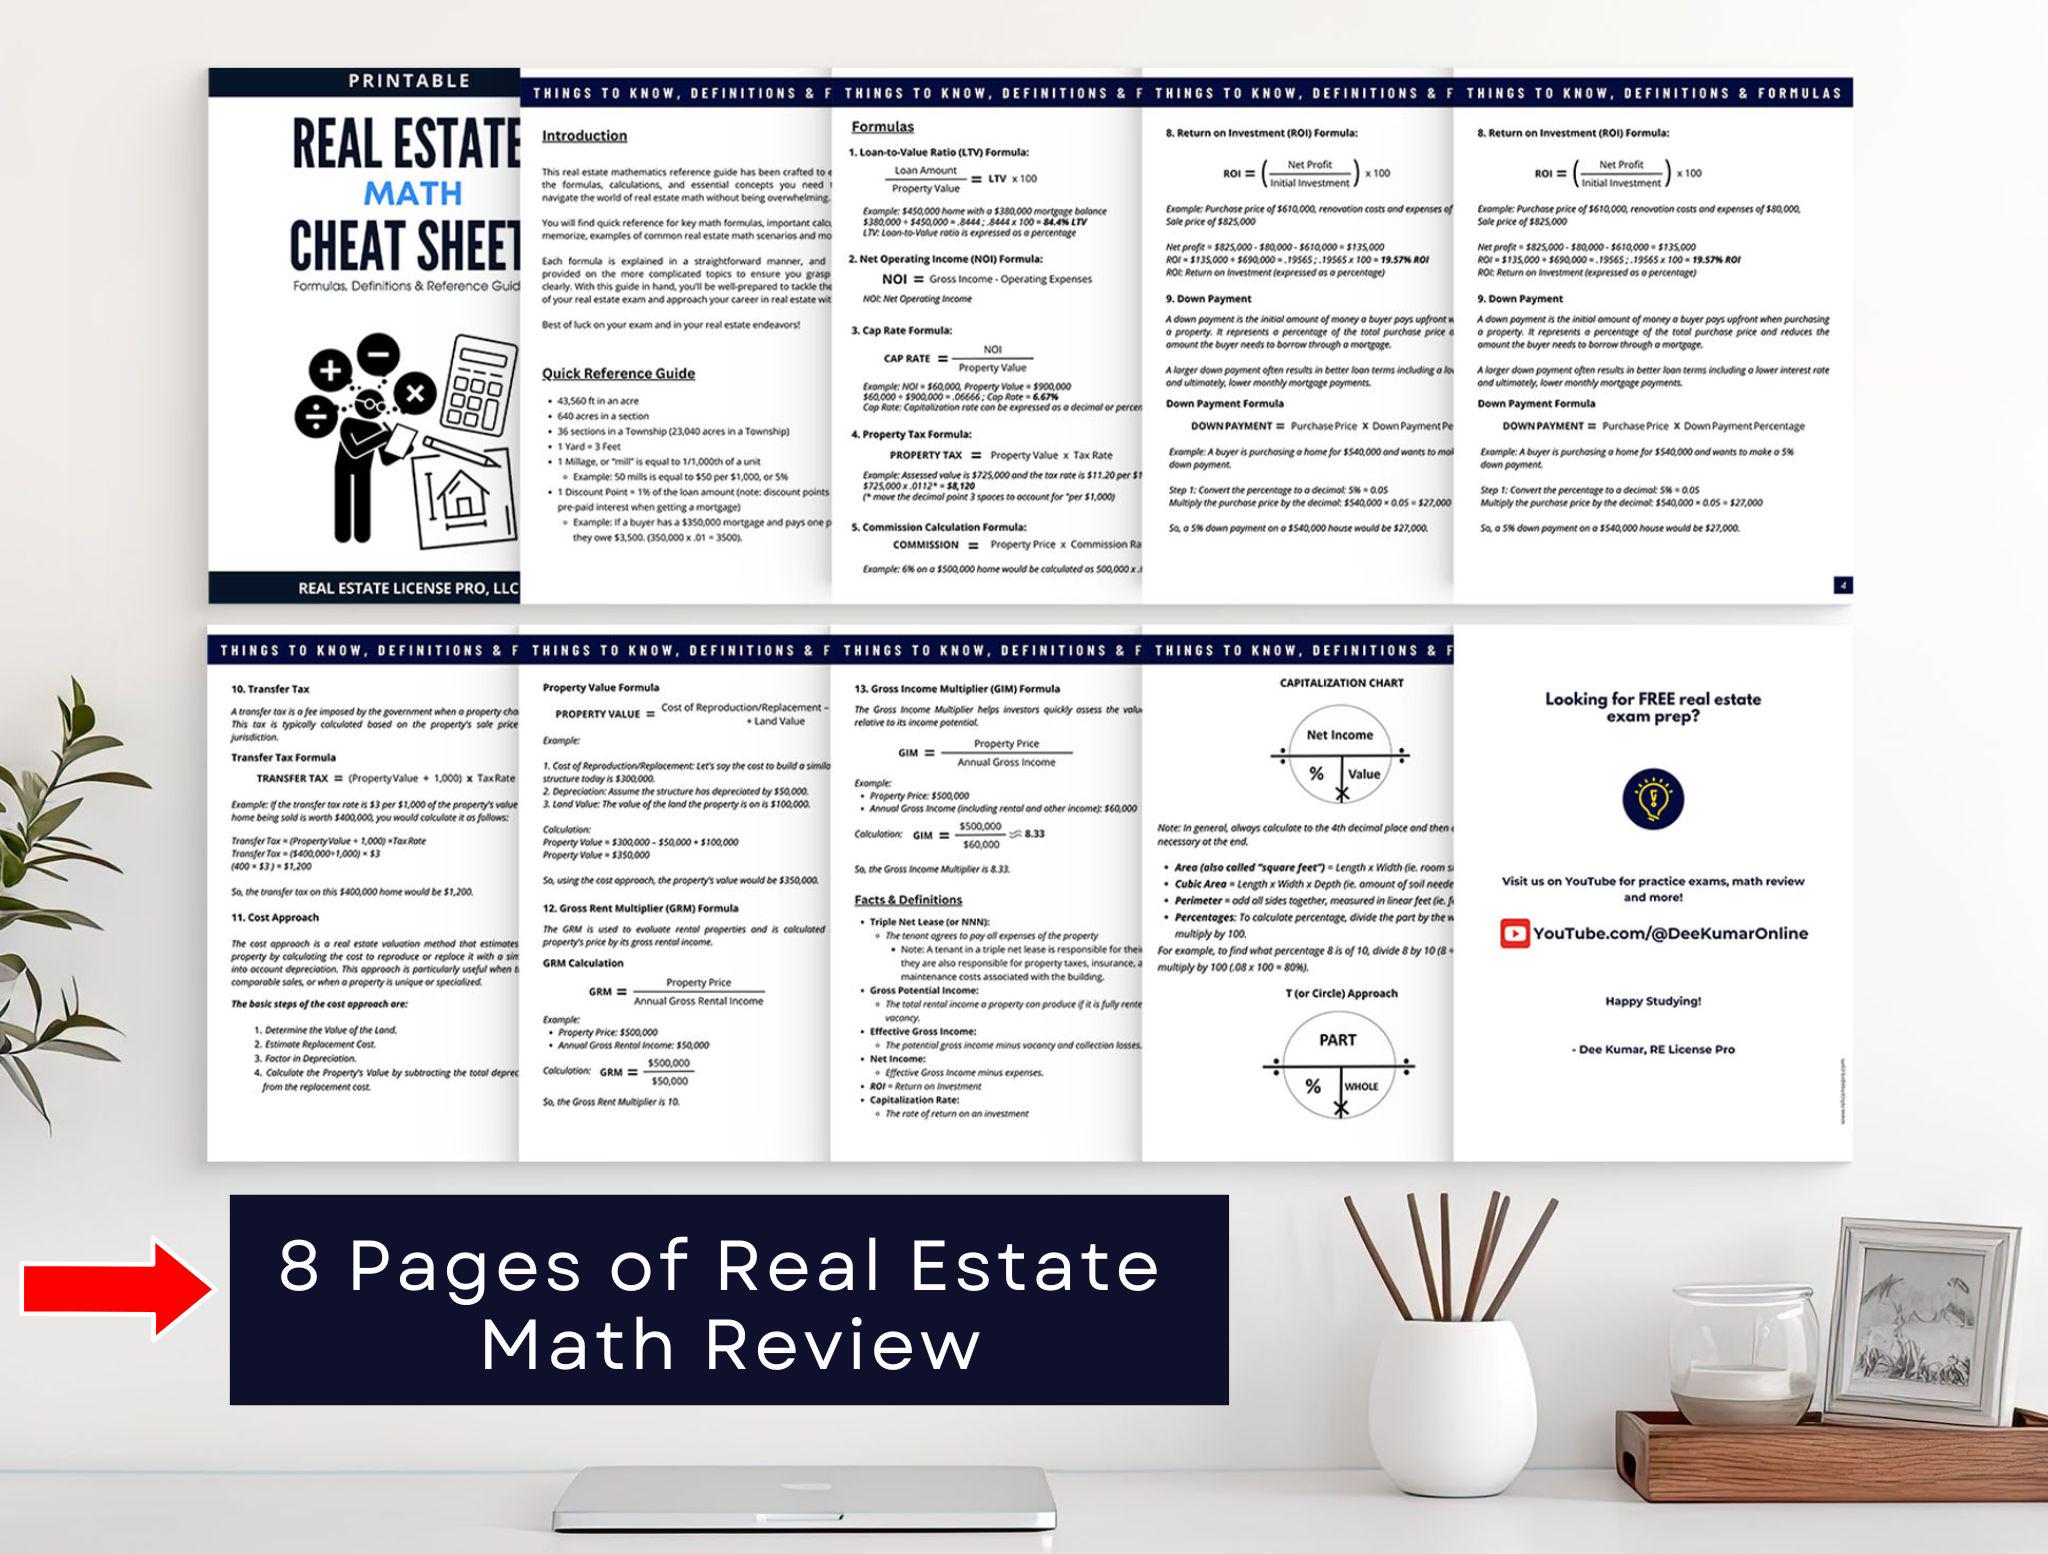
Cap Rate: Net Operating Income ÷ Property Value = Cap Rate. Or rearranged: NOI ÷ Cap Rate = Value. This one trips people up because they confuse gross income with net operating income. Gross income minus vacancy and credit loss equals effective gross income. Then subtract operating expenses to get NOI. Operating expenses do NOT include mortgage payments or depreciation. That's a common mistake on the exam. If a question includes debt service in the expense list, you ignore it for the cap rate calculation. Transfer Tax: Usually calculated per $500 or $1,000 of the sale price. Check your state's specific rate because it varies wildly. In some states it's a flat amount, in others it's tiered by price bracket. Memorizing a national formula here is pointless. Know how to look it up quickly and apply the bracket system your jurisdiction uses.
Get the Full Details

The proration problem most people mess up
Property tax proration and rent proration are two of the most consistently poorly answered sections. Here's the practical way to handle them without getting tangled. Rent proration is straightforward if the rent is paid in advance. The seller owns the property until closing, so the buyer owes the seller for the days after closing that fall within a prepaid rent period. Days owed = (daily rent) × (days after closing). Daily rent is monthly rent ÷ 30. Some exams use 365 ÷ 12 for a more precise daily figure, but the standard is 30-day months unless stated otherwise. Property tax proration is the opposite direction because taxes are typically paid in arrears. The seller has already lived in the property during the current tax year but hasn't yet paid the bill. The buyer owes the seller for the portion of the year the seller occupied. Same daily calculation, different direction. Sellers credit buyers at closing.
I ran into a situation a few years ago where a client was selling with delinquent property taxes from the prior year. The standard proration formula assumes current-year taxes only. I had to calculate the accrued daily amount for the prior year's delinquency separately and negotiate who absorbed that cost. It wasn't on any exam, but it's the kind of thing that separates people who understand the concept from people who just memorized a formula. On the exam, if taxes are delinquent, they'll usually tell you explicitly. Don't assume standard proration applies.
Loan-to-value and down payment relationships
These show up constantly and they're deceptively simple. Loan-to-value ratio is Loan Amount ÷ Property Value (or sale price, whichever is lower). If someone puts 20% down on a $300,000 home, the loan amount is $240,000 and the LTV is 80%. The exam loves to flip this. They might give you the loan amount and the LTV and ask for the purchase price. That's Loan Amount ÷ LTV = Value. $240,000 ÷ 0.80 = $300,000. Points are another area where people lose easy marks. One point equals 1% of the loan amount. Discount points are prepaid interest. Origination fees are separate and not always expressed as points. If a lender charges 1.5 points on a $200,000 loan, that's $3,000 at closing. The exam will sometimes mix points with other closing costs and ask for the total cash to close. Add everything: down payment, loan amount, points, origination, appraisal, inspection, title insurance, recording fees. Don't forget the down payment is part of cash to close even though it's not a fee.
Area calculations you can't afford to skip
Trapezoid area = ((Side A + Side B) ÷ 2) × Depth. This one is basically guaranteed on the math section. Rectangle is length × width, triangle is (base × height) ÷ 2. Circle area is × r². Most exams use 3.14 for pi unless specified. A circular lot with a 100-foot radius is approximately 31,400 square feet. If they ask how many acres that is, divide by 43,560. That's about 0.72 acres. The trapezoid formula is where I see the most wrong answers. People add the two parallel sides, divide by two, then forget to multiply by the depth. They stop at the average width. Make sure you do both steps. I had a practice exam where the answer choices included the result of stopping after step one, and about 40% of my study group picked it. It's an easy trap.
What the formulas won't tell you
Formula knowledge alone won't pass this exam. The questions are designed to test whether you can identify which formula applies in a word problem. You'll read a 3-to-4 sentence scenario and need to extract the relevant numbers and the relationship between them. Here's the brutal truth about the formulas: they work perfectly for straightforward problems and fall apart the moment a question includes extra information meant to distract you. I've seen questions list five different numbers and only three are relevant. Your job is to identify which three before you touch a calculator. Practice reading questions backward from the answer choices sometimes helps — see what the question is actually asking for, then figure out which numbers you need to get there. Another limitation of pure formula study is that it doesn't prepare you for the ethics and law sections, which make up roughly half the exam in most states. The math is maybe 30 to 40 percent. Don't neglect the rest because the formulas feel more concrete. Ethics questions have no formula. They test your judgment, and the only way to prepare is to read the actual code and practice applying it to scenarios.
If you're stuck on a particular topic after studying the formulas, the best workaround I found is to create your own word problems. Take a formula, write five different scenarios that use it, and solve each one. It forces you to recognize the formula in different contexts, which is exactly what the exam does.