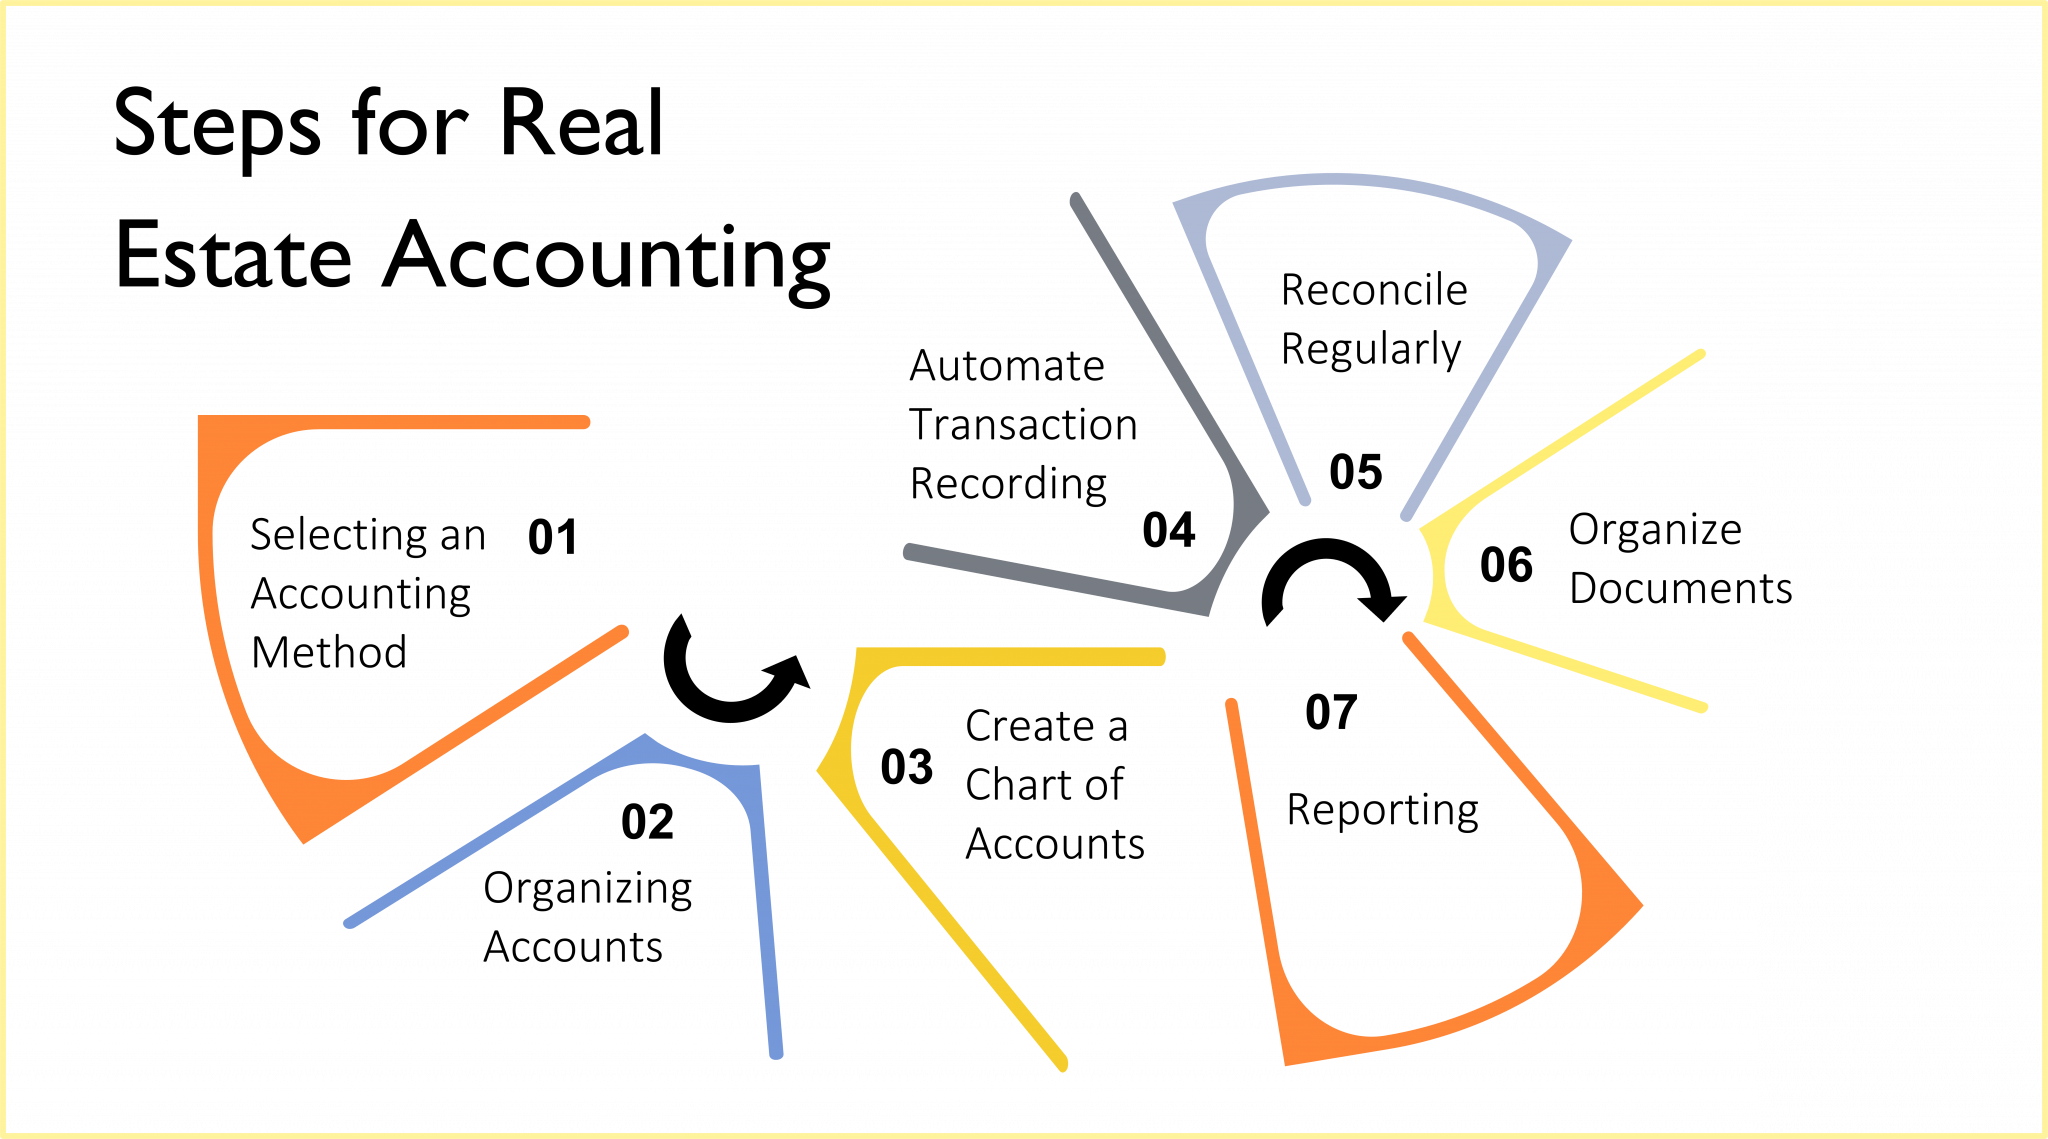
What actually happens when you book entries for a real estate fund
Most people think real estate fund accounting is just property management with more spreadsheets. It isn't. You are tracking capital calls, distributions, waterfall calculations, and partnership interests across multiple entities that all feed into a single reporting picture. The day-to-day work involves coding rent receipts to the right property, the right lease, and the right investor bucket while simultaneously making sure you haven't double-counted something because two funds share the same asset. I spent years doing this manually before any of the software tools I am about to describe existed, so I know what breaks first. Usually it is the cash application process. A tenant sends one payment that covers three months of rent for unit 4B and part of a common area maintenance charge. If your chart of factoring doesn't separate operating expenses from capital expenditures clearly, your waterfalls get wrong at the distribution stage. That error shows up six months later when you are trying to explain why Investor B got $12,000 less than their catchment schedule predicted.
Real Estate Fund Accounting Basics that actually matter
The core mechanics break down into five buckets that every practitioner handles constantly: revenue recognition, expense accruals, capital call processing, distribution waterfalls, and financial statement consolidation across partnership interests. Revenue goes into the system when it is earned, not when cash hits the bank. That distinction matters because GAAP compliance for real estate funds follows the same accrual rules as corporate accounting, even though the cash flow feels very different. Expense accruals are where most mistakes happen. Property taxes come in quarterly but benefit the full year. Insurance premiums are annual but cover twelve months. If you expense them when paid, your monthly P&L looks garbage and your quarterly reports will require manual adjustments that nobody wants to do. I built a simple accrual matrix in Excel years ago that mapped each expense type to its monthly recognition pattern. It cut my month-end close from three days down to about nine hours for a fund with twelve properties. Capital calls arrive when the fund needs money to deploy into new acquisitions or to cover operational shortfalls. Each call has a specific amount, a due date, and an allocation across investors based on their committed capital. Processing these correctly requires matching the call to the right investor group, recording the equity increase, and then tracking the unfunded commitment remaining. Miss one detail and your capitalization table is wrong, which cascades into every distribution calculation downstream.
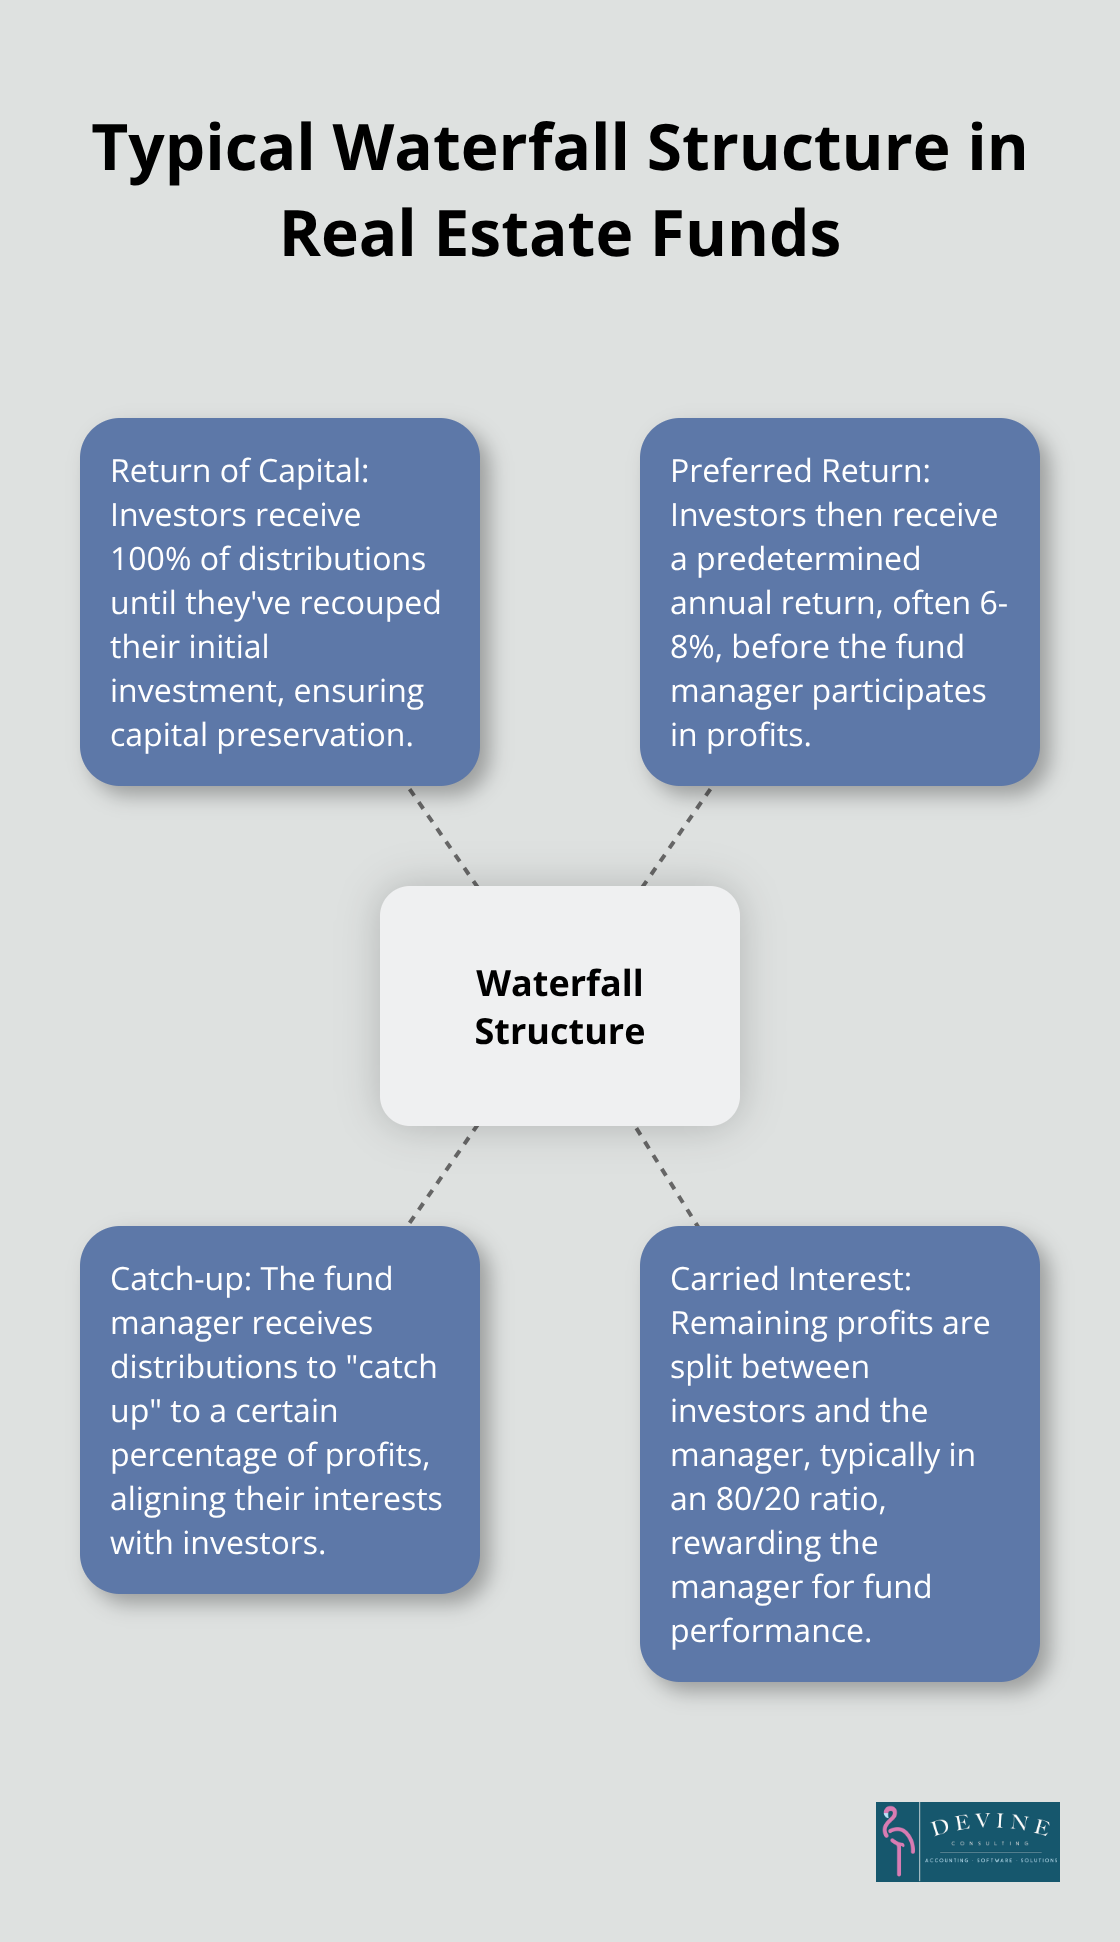
Distribution waterfalls determine how profits split between the general partner and limited partners. The most common structure in the US is the traditional waterfall with a preferred return hurdle, a catch-up clause, and then a split like eighty-twenty. But the math only works if your profit calculation is clean. I once worked with a fund where the waterfall was calculated on cash flow instead of net operating income, which meant properties with heavy depreciation appeared more profitable than they actually were. The GP took out significantly more money than they should have for two years before anyone noticed. Switching the basis from cash flow to accounting profit fixed it, but the reconciliation took most of a weekend. Consolidation across partnership interests means every fund, every property, and every special purpose vehicle feeds into one set of financial statements. This is harder than it sounds because each entity may use a different sub-ledger, a different chart of accounts, or a different fiscal month close. I have seen funds where the tax basis books used straight-line depreciation while the GAAP books used MACRS, creating temporary differences that showed up on Schedule K-1s as unexplained variances. Documenting those differences early in the setup phase saves enormous time later. Here is something most introductory guides do not mention: the difference between fund-level and property-level accounting drives almost every downstream decision. Fund-level accounting tracks the investment vehicle itself—capital contributions, management fees, performance allocations, and investor returns. Property-level accounting tracks individual asset operations—rent roll activity, vendor payments, reserve spending, and unit-level profitability. Your general ledger should maintain both views simultaneously, or you will spend weeks every quarter trying to reconstruct property performance from fund-level data that was never captured at that granularity.
Get the Full Details
Management fee calculation is another area that looks simple until you encounter pause periods, clawback provisions, and catch-up calculations during exit scenarios. A typical management fee is two percent of committed capital during the investment period and two percent of invested capital during the deployment period, but the switch between those two bases happens at different times for different funds. I had a fund manager who expected the switch to occur at first closing. The Limited Partnership Agreement actually stated it occurred at first capital call. Those are four to six months apart on a typical deal, and the fee difference on a fifty-million-dollar fund is substantial. For practical setup, you need a chart of accounts that separates revenue by source type—rent, parking, laundry, late fees, application fees—because each behaves differently and some are restricted by lease terms or local regulations. Expense accounts should mirror the nature of the cost, not the vendor, so you can group property taxes separately from insurance separately from utilities regardless of who sends the invoice. I recommend starting with the AICPA Real Estate Industry Audit Guide chart of accounts and trimming it down to what your specific fund structure actually needs. Most people add too many accounts and then regret it when they have to reconcile fourteen different variations of maintenance expense. Software choice depends entirely on fund size and complexity. For a single-property LLC with three investors, QuickBooks Online with a real estate add-on handles things adequately. For a multi-fund platform with waterfall distributions and institutional investors, you are looking at Yardi, RealPage, or dedicated fund accounting platforms like Black Knight or Entrata. The cheaper tools fail when you need to generate Schedule K-1 data, calculate internal rate of return, or produce investor-level profit splits. Nothing about that is intuitive in a standard accounting package.
One thing I wish someone had told me early: audit trails matter more than convenience. Every journal entry, every reclassification, every manual adjustment needs a documented reason that survives a IRS examination and an LP review. I learned this the hard way when a fund auditor asked me to justify a sixty-thousand-dollar reclassification between two expense categories and I could not produce anything beyond a note that said "moved to correct account." We spent three weeks reconstructing the supporting documentation from email threads and spreadsheet versions. Never skip the justification field. Month-end close typically takes five to seven business days for a fund with moderate complexity if the prior month was clean. If you carry forward unprocessed items or have unreconciled accounts, it stretches to two weeks and often eats into the time you need for investor reporting. Building a standardized close checklist with hard deadlines for each step—bank recs by day two, accruals by day three, waterfall calculations by day four, draft financials by day five—keeps everything moving predictably. The biggest bottleneck in this work is always data quality at the property level. Garbage in, garbage out applies relentlessly here. If lease abstracts are incomplete, if CAM reconciliations are approximate, if tenant improvement allowances are not tracked against the correct budget line, your fund-level numbers will be wrong regardless of how sophisticated your accounting system is. I recommend implementing a data governance policy at the property manager level with mandatory fields before any transaction enters the general ledger. It adds about ten minutes to each transaction but prevents hours of cleanup work later.
If you want a practical starting point for getting organized, I put together a basic real estate fund accounting template that covers the core structures—a capital call tracker, a distribution waterfall calculator, a month-end close checklist, and a chart of accounts mapper. It is not a complete solution for any specific fund, but it gives you a foundation that is better than starting from scratch. You can find it at the link below and adapt it to your particular situation. The download link for the Real Estate Fund Accounting Basics template is here: [Download Template] Once you have the template loaded, spend the first week mapping your existing data into its structure rather than trying to force your current system to fit the template. The mapping step reveals gaps in your chart of accounts, missing lease data, and reconciliation discrepancies that would otherwise hide until you needed accurate numbers most. That single step typically uncovers three to five material issues in a fund that has been running for twelve months or more without a formal accounting review.