How the Numbers Actually Work When You Rent Out Property
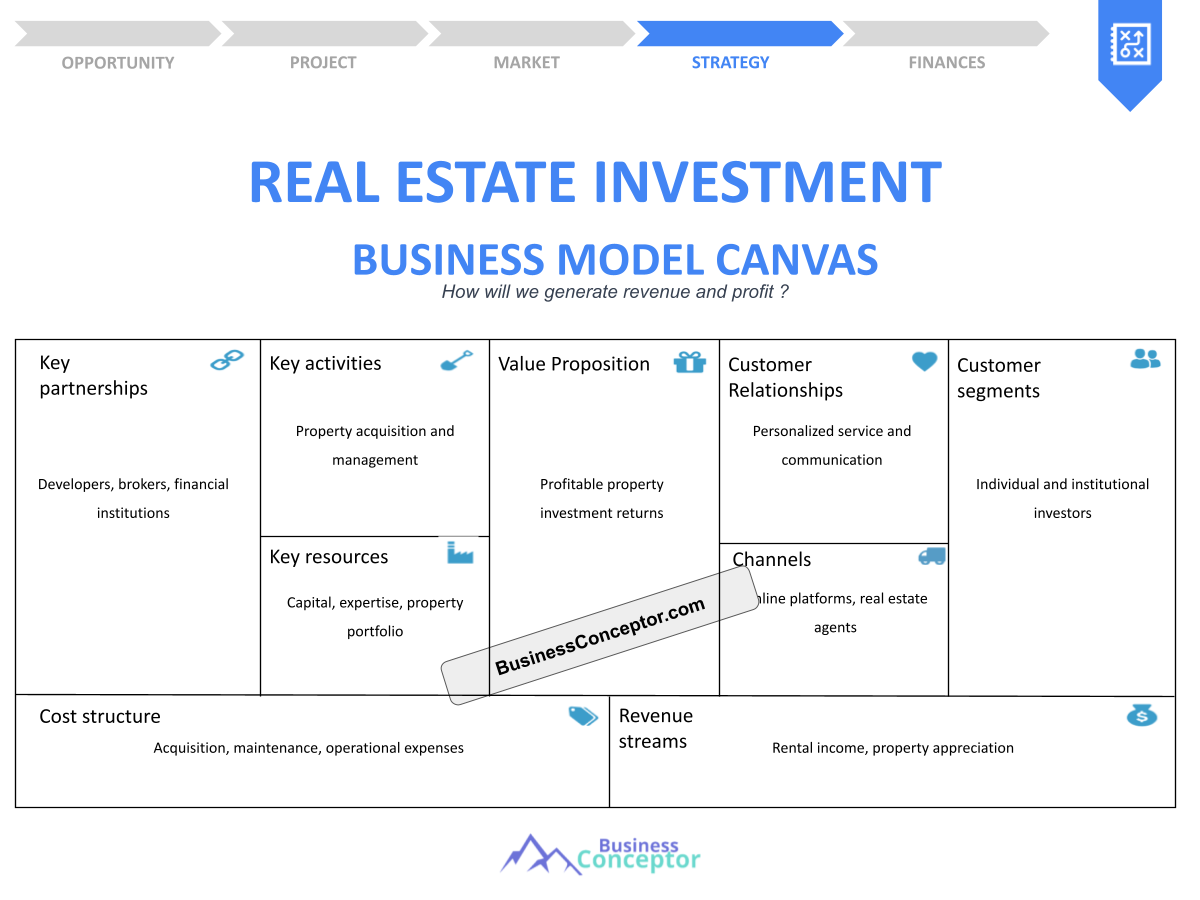
The biggest mistake I see people make with the Real Estate Investment Business Model is confusing cash flow with profit. You can have positive monthly cash flow and still lose money every year once you account for vacancies, maintenance, capEx, property management fees, insurance bumps, property taxes, and the opportunity cost of your down payment. I learned this the hard way on a duplex I bought in 2019. The bank approval looked clean on paper. Arrears were projected at 95% occupancy. For eight months it ran fine, then the water heater blew, the tenant in unit B found a mold issue that triggered a $4,200 remediation job, and the third-floor apartment sat vacant for eleven weeks. My monthly cash flow went from positive to negative three months in a row. The property made money when I averaged it over three years. It didn't when I looked at any single quarter. The core structure is simple enough. You acquire a property or portfolio, you place tenants who pay rent that covers all operating expenses plus debt service, and the surplus flows to you as cash on cash return. Over time you capture appreciation when the market moves up, and you capture tax benefits from depreciation and mortgage interest deductions. Some plays stack these three engines together. Others lean heavily on just one. I'll break down the main operational models because they behave differently under stress.
Long-term residential rental. This is the bread-and-butter model. Tenants sign twelve-month leases. You manage turn-over every few years instead of every few days. Vacancy risk is lower but cash flow is thinner per unit. The key lever here is expense control. If you can keep vacancy under 5%, maintain your CapEx reserve at 8-10% of gross rent, and hold insurance and property tax escalations below 3% annually, the math works even in flat markets. Multifamily apartments. More units mean more diversification of tenant risk and more predictable cash flow, but also more complexity. A 12-unit building is not twelve times easier than a single family home. It usually demands professional property management or at least a solid vendor network. I've seen investors buy 24-unit complexes where the NOI looked strong at closing, only to realize the roof was six years past replacement and the HVAC systems were three replacements away. The underwriting needed to include a deferred maintenance audit before anyone signed a LOI. Short-term rentals. Higher per-night revenue, higher turnover costs, higher regulatory risk. In my experience, the gross yield advantage usually evaporates once you factor in cleaning, guest amenities, platform fees, dynamic pricing tools, and local permitting. Cities like Austin, Denver, and Nashville have tightened STR regulations aggressively since 2022. If you're playing this model, you need to verify short-term rental ordinances in writing before you buy, not after you close.
Commercial long-term leases. Triple net leases shift most expenses to the tenant. That sounds ideal. It isn't always. A single tenant default on a ten-year NNN lease can wipe out years of steady income, and finding a replacement tenant in a submarket with rising vacancy takes time. I worked a deal where a well-credentialed tenant left after year four. The unit sat empty for fourteen months. The lender refused to restructure the debt during COVID disruptions because the original guarantor had moved offshore. That deal taught me to underwrite for lease rollover risk even when the tenant looks bulletproof.
Get the Full Details

Underwriting Basics That Actually Matter
Most beginners underwrite using only gross rent minus mortgage payment. That ignores real operating costs. A proper underwrite uses this sequence: Effective Gross Income minus Operating Expenses equals Net Operating Income. Effective Gross Income is not the same as Potential Gross Income. You must subtract vacancy and credit loss, which typically runs 5-8% for residential and 8-12% for commercial depending on the market. Then you deduct property management at 8-10%, insurance, property taxes, utilities if you pay them, repairs and maintenance, and CapEx reserves. What's left is NOI. Debt service comes after that. Cap rate is just NOI divided by purchase price. A 6% cap rate on a $400,000 property means $24,000 annual NOI. If your debt service is $18,000, your pre-tax cash flow is $6,000. That looks fine until you add actual vacancy, a $3,000 roof repair, and a 4% insurance increase. Suddenly your $6,000 becomes $1,200.
Cash on cash return measures your actual equity yield. Take annual pre-tax cash flow and divide it by total cash invested, including closing costs and immediate renovations. On a $80,000 cash investment yielding $4,800, your cash on cash is 6%. That number matters more than cap rate when you're comparing properties with different financing structures.
A Specific Edge Case I Faced
I once inherited a property through an estate sale where the prior owner had never updated the title. The deed listed a deceased sibling as a co-owner who had died five years earlier without probate. The county recorder flagged the title insurance application immediately. Underwriting stalled for six weeks while my attorney traced the probate records and filed a corrective affidavit. During that window, the buyer's financing lock expired and rates jumped forty basis points. The seller's estate wanted a full-price close. I had to renegotiate the purchase contract with a rate-jump contingency clause and extend the closing timeline. The workaround was straightforward but tedious. I pulled the death certificates, drafted the affidavit of heirship, recorded it with the county, and obtained a new commitment letter from title. Total delay: five weeks. Total cost added: roughly $2,800 in legal fees and a $1,200 financing float. It was worth it because the property appraised $30,000 above asking. But it would have destroyed my deal timing if I hadn't flagged the title issue before committing earnest money. Over-leveraging in rising-rate environments. Adjustable-rate mortgages look cheap when you're underwriting at 3.5%. They become brutal at 7%. I saw a buyer in Columbus lock a five-year ARM at 3.75% on a 16-unit building. When rates reset in year three, the debt service jumped 40%. He refinanced into a fixed commercial loan at 8.2%, but the higher rate ate his entire cash flow cushion. The lesson is straightforward. If you're buying with variable debt, stress-test the reset scenario before you sign. Assume rates will rise at least 200 basis points above your anchor rate. Ignoring tenant quality variance. Not all tenants cost the same to manage. A reliable tenant who pays on time and calls in repairs through the proper channel costs you almost nothing beyond routine maintenance. A problematic tenant who violates the lease, skips payments, and files frivolous code complaints can cost you $3,000 to $8,000 in legal fees and vacancy in a single incident. Screen aggressively. Run credit and eviction history checks. Call previous landlords. A good tenant is worth more than a slightly higher rent check from a marginal tenant.

Underestimating CapEx cycles. Roofs last 20 to 25 years. HVAC systems last 15 to 20. Water heaters last 8 to 12. Appliances last 7 to 10. Every property has aging systems, and every system fails on schedule. I budget CapEx reserves at 6% of gross rent for newer construction and 10% for buildings older than twenty years. When I skip the reserve and treat that money as operating cash, I always regret it within eighteen months.
When This Model Doesn't Work
The Real Estate Investment Business Model fails in markets where property taxes are rising faster than rent growth, or where local governments restrict rental supply through zoning or permitting hurdles. It also fails for investors who can't handle illiquidity. Real estate takes weeks or months to sell. You can't liquidate a rental property during a downturn without taking a steep haircut. If you need access to your capital within a year, this is the wrong vehicle. A practical alternative in those situations is REITs or real estate debt funds. They give you liquidity and remove the operational burden of property management. The trade-off is lower control and thinner margins after fees. Some investors split their allocation between direct ownership and fund exposure to balance liquidity with returns.
Practical Next Steps
Start with one property in a market you understand personally. Live near it or visit it regularly. Underwrite conservatively. Run vacancy at 7%, maintenance at 8%, and insurance escalation at 4%. Use a property management company even if you think you can self-manage. Their fees buy you time and reduce your exposure to tenant disputes. Track your actual numbers monthly against the underwritten assumptions for at least twelve months. Adjust your model when reality diverges from projections. Most investors skip that step and repeat the same mistakes. The model works if you respect the math and accept that real estate is an operational business, not a passive investment. Cash flow comes from disciplined expense management and tenant quality. Appreciation comes from market trends you can't control. Depreciation benefits come from tax code changes you can only plan around. Focus on what you can influence. The rest will sort itself out.