Property Math Breakdown
The biggest mistake people make is assuming that all real estate calculations are straightforward multiplication. They aren't. The moment you introduce pro-rations, commissions, and closing cost allocations, the arithmetic gets messy fast. I once had a situation where a prorated HOA fee was based on a 31-day month instead of the standard 30-day method, and it threw off my closing figure by $47. I caught it because I double-checked the settlement statement line item by line item, but most buyers would have walked through the door without noticing. The core concepts you actually need to understand are simple enough. Property tax calculations, prorations, loan-to-value ratios, cap rates, gross rent multipliers, and commission splits. That's the full toolkit. Everything else is just context.
Real Estate Math For Dummies
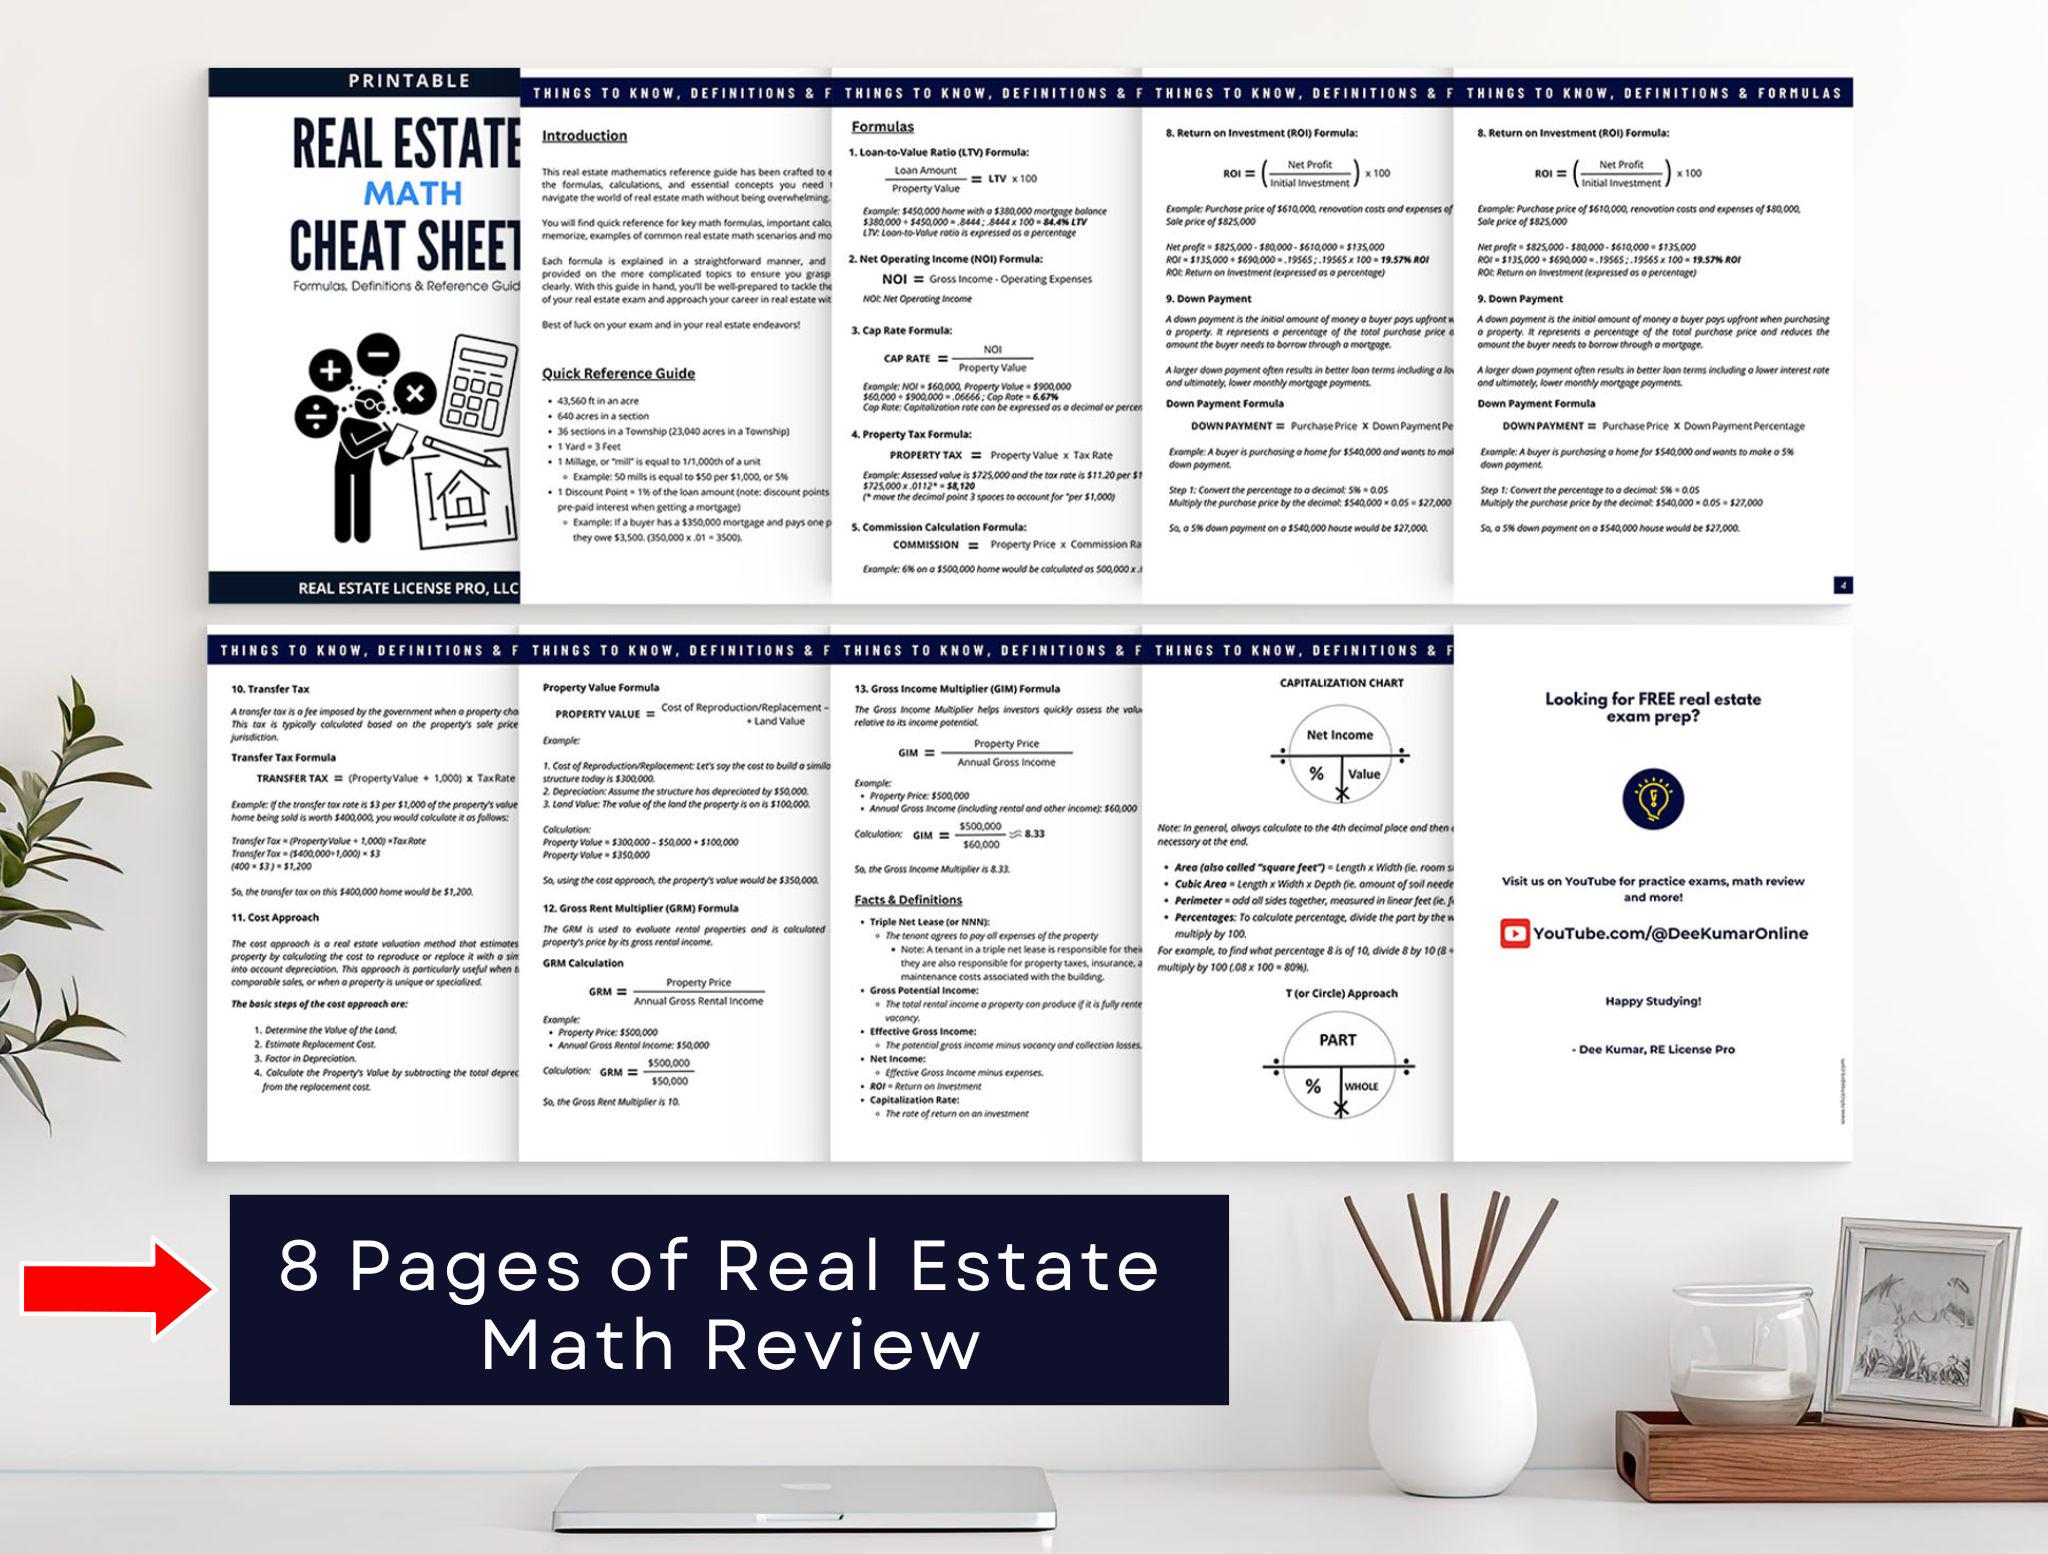
Starting with the basics. Most people who ask me about this topic are either prepping for a licensing exam or trying to evaluate a rental property without getting burned. The math doesn't require calculus. It requires comfort with percentages, decimals, and reading a table of contents in a contract. Loan-to-value ratio is straightforward. Take the loan amount, divide it by the appraised value or purchase price, whichever is lower. Multiply by 100 to get a percentage. If you're putting 20% down on a $300,000 property, your LTV is 80%. That's all there is to it. The confusion usually comes when people mix up the down payment percentage with the LTV. They are inverses of each other. Down payment plus LTV always equals 100%. Cap rate trips people up more than anything else. You take the net operating income and divide it by the property value. Simple formula. But here is the thing nobody tells beginners: cap rate assumes you are buying the property in cash. It does not account for financing. If two properties have the same cap rate but different mortgage terms, your actual return will be completely different. I ran into this when comparing two multifamily units in Columbus. One had a better cap rate on paper, but the financing structure on the second property made the cash-on-cash return significantly higher. Never let cap rate be your only decision point.
Gross rent multiplier is even simpler than cap rate. You divide the property price by the gross annual rental income. It gives you a rough sense of whether a property is overpriced relative to its income potential. A GRM of 8 means the property costs eight times its annual rent. Lower is generally better, but it depends on the market. In some areas, a GRM of 12 is normal. You have to know your local numbers before you judge anything. Here is the practical workflow I use. When evaluating a property, I start with the GRM because it takes about thirty seconds. Then I move to cap rate, pulling the actual operating expenses from the seller's statements. Then I calculate the cash flow after debt service. If the numbers work at that level, I do a more detailed analysis. This three-step process cuts my initial screening time from around forty minutes down to roughly twelve minutes per property. Pro-rations are where most people lose money. Property taxes, HOA fees, rent, and utilities all need to be split between buyer and seller based on the closing date. The standard method is the 30-day month and 360-day year approach, but some contracts use the actual days in the month. If you assume the wrong method, your settlement statement will be off. I worked a deal in Nashville once where the county taxed on a calendar year basis, but the contract prorated using a 360-day year. The difference was small on a low-tax area, but in a high-tax county it added up to over $200 in a single transaction.
Get the Full Details

Commission math is another area that gets glossed over. A 5% commission on a $400,000 sale is $20,000. That part is fine. But commissions are typically split between the listing agent and the buyer's agent, and then each of those splits again with their broker. If the total commission is 5%, and the listing side gets 60% of that, you are looking at $12,000 to the listing broker before their own split. Most new agents forget to account for the broker commission when they are negotiating their own take-home pay. They think they are making 2.5% when they are actually making closer to 1.5% after the broker cut. Debt service and monthly mortgage payments deserve attention too. The standard formula is P equals the loan amount, r is the monthly interest rate divided by 12, and n is the total number of payments. The formula itself is M equals P times r times 1 plus r all to the power of n, divided by 1 plus r all to the power of n minus 1. You do not need to memorize that. Every calculator app handles it. What you need to understand is how extra principal payments affect the total interest over the life of the loan. A $50,000 loan at 6.5% over 30 years costs about $60,000 in interest. Add $200 per month toward principal and you save roughly $18,000 in interest and pay off the loan almost three years early. That matters more than people realize when they are evaluating investment properties. One counter-intuitive thing about real estate math: the numbers on paper rarely match the numbers in practice. Market comps shift. Closing costs vary by county. Inspection credits change the effective purchase price. I always build a 5% buffer into my initial calculations to account for this. It sounds conservative, but in a tight market a 5% cushion can mean the difference between a deal that works and a deal that bleeds you dry at closing.
The biggest limitation of any simplified math approach is that it cannot replace an actual due diligence period. Cap rate and GRM are screening tools, not valuation tools. If you are serious about a property, you need the full financial package: rent rolls, expense history, tax records, and a physical inspection. No formula compensates for bad data. I have seen deals fall apart because someone ran the numbers on a property without verifying the actual operating expenses. The seller reported $18,000 in annual expenses. The reality was closer to $31,000 once you factored in maintenance reserves, vacancy, and management fees. That kind of discrepancy turns a profitable deal into a loss. For anyone just starting out, the practical next step is to grab a spreadsheet and run ten properties through the GRM and cap rate workflow. Use public records and listing data. You will quickly see which markets make sense for your criteria and which ones are just noise. Once you have done that a few times, the calculations become automatic. You stop thinking about the formulas and start thinking about the numbers.