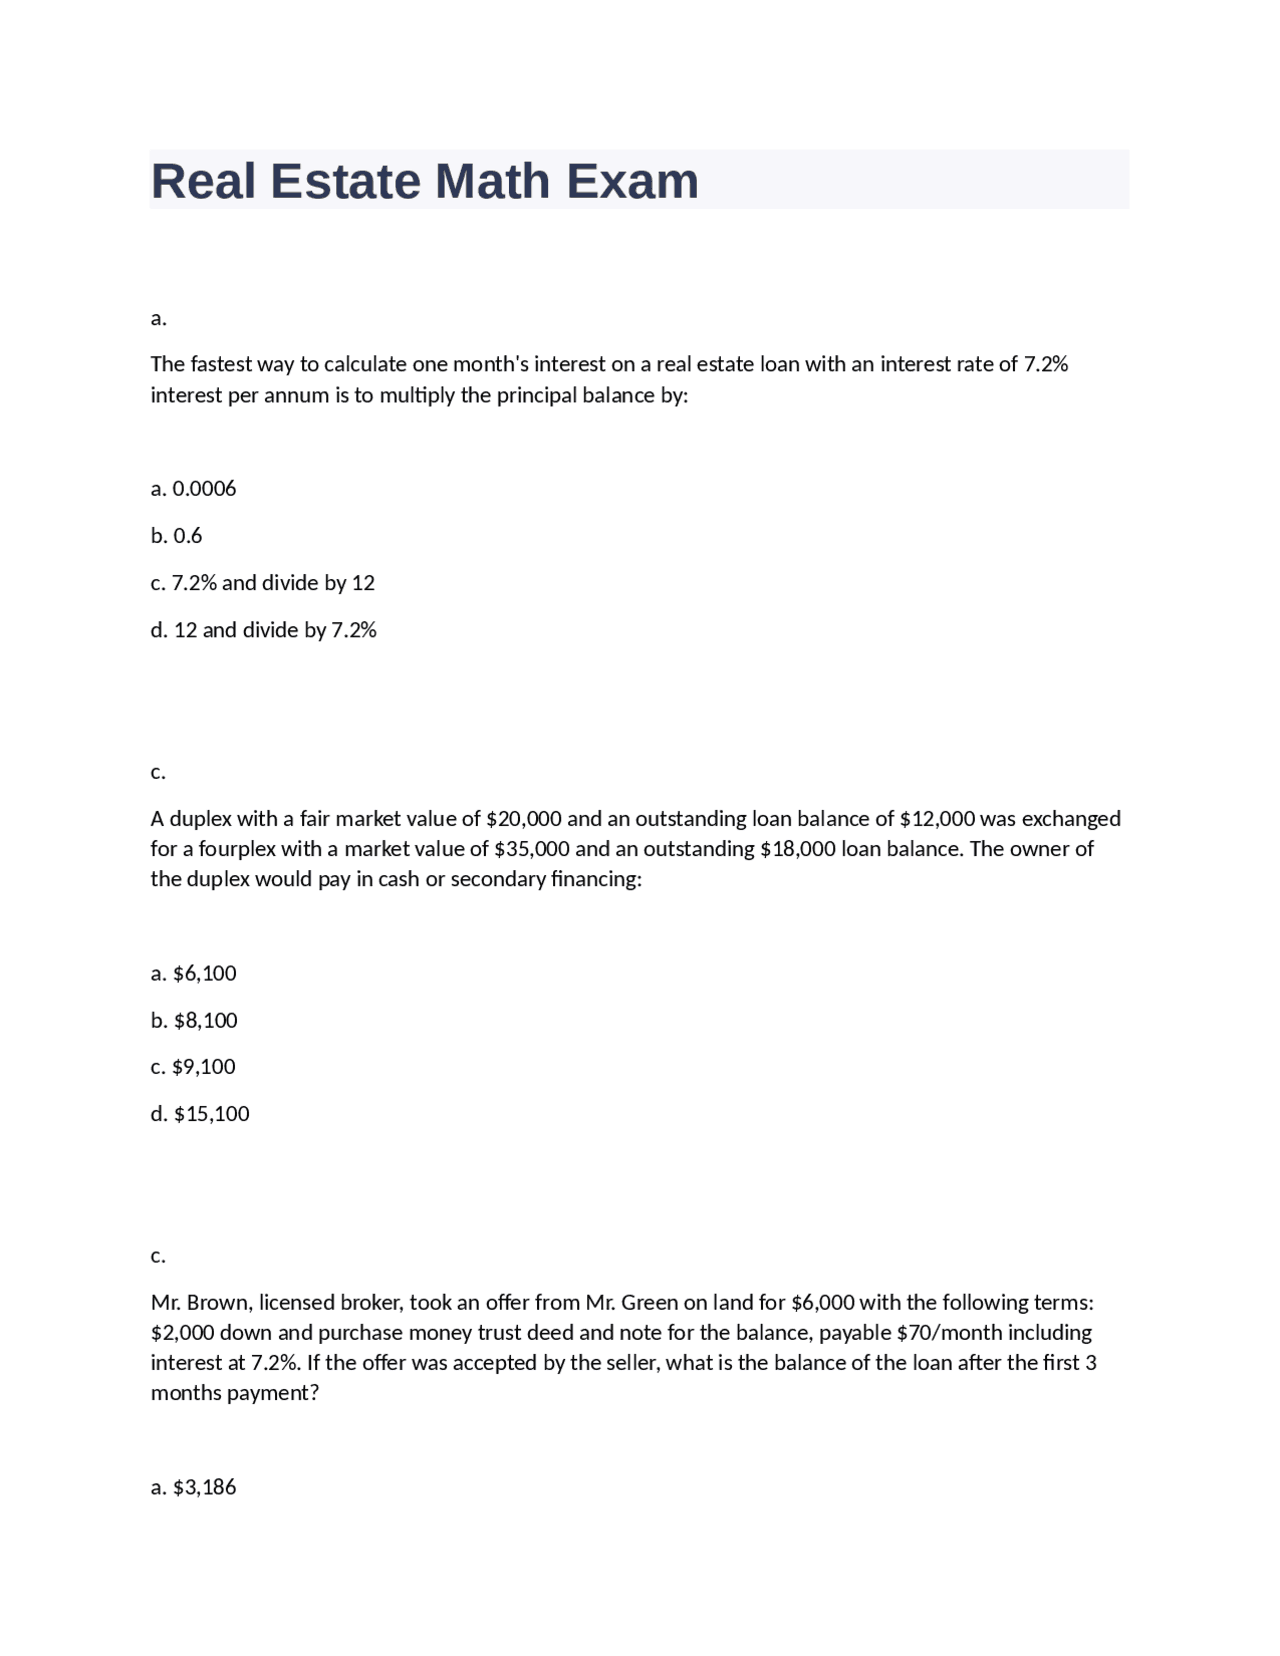
Running Pro Forma Numbers Without Losing Your Mind
Most people approaching real estate math panic when they see a page full of numbers. The math isn't hard. It's just that most beginner guides don't actually show how these calculations connect to each other in practice. You're looking at vacancy rates, CapEx reserves, debt service coverage ratios, and closing cost all at once. Let me walk through how I actually work through these problems. The first thing most people do wrong is start from the bottom of the deal instead of the top. You pull rental income first, then build down through expenses, debt service, and finally net operating income. When you start with NOI and work backward, you end up circular-reasoning your way into errors that don't show up until your investor calls and asks why the returns look too good. I learned this the hard way on a multifamily deal in 2019 where I had projected a 14% cash-on-cash return and it turned out to be 8.2%. The gap was entirely in my vacancy assumption—I'd used market vacancy instead of effective vacancy, which includes credit loss and collection fees. That's a 3-4% drag most people miss on their first run.
Real Estate Math Problems And Answers
Let me break this down by the types of problems you'll actually encounter in the field, not just on licensing exams. Cap Rate and Valuation Problems This is the foundation. Cap rate equals net operating income divided by property value. But here's what people get wrong: they use gross income instead of NOI, or they forget to subtract operating expenses that aren't debt-related. I had a client once who was appraising a small retail strip and plugged $120,000 in gross rents directly into the formula with a 7% cap rate, arriving at a $1.71 million valuation. The actual NOI after TMI (taxes, insurance, and maintenance—typical triple-net operating expenses) came to about $94,000, which values the property at roughly $1.34 million at the same cap rate. That's a $370,000 error from skipping one step.
The correct sequence is gross scheduled income minus vacancy and collection losses equals effective gross income minus operating expenses (property taxes, insurance, management, maintenance reserves, utilities if landlord-paid) equals net operating income. Then NOI divided by your going-in cap rate equals value. Debt Service and DSCR Problems Debt service coverage ratio is NOI divided by annual debt service. Lenders typically want to see 1.20 or higher. The tricky part is calculating monthly debt service from a loan amount, interest rate, and term. The formula is:
Get the Full Details
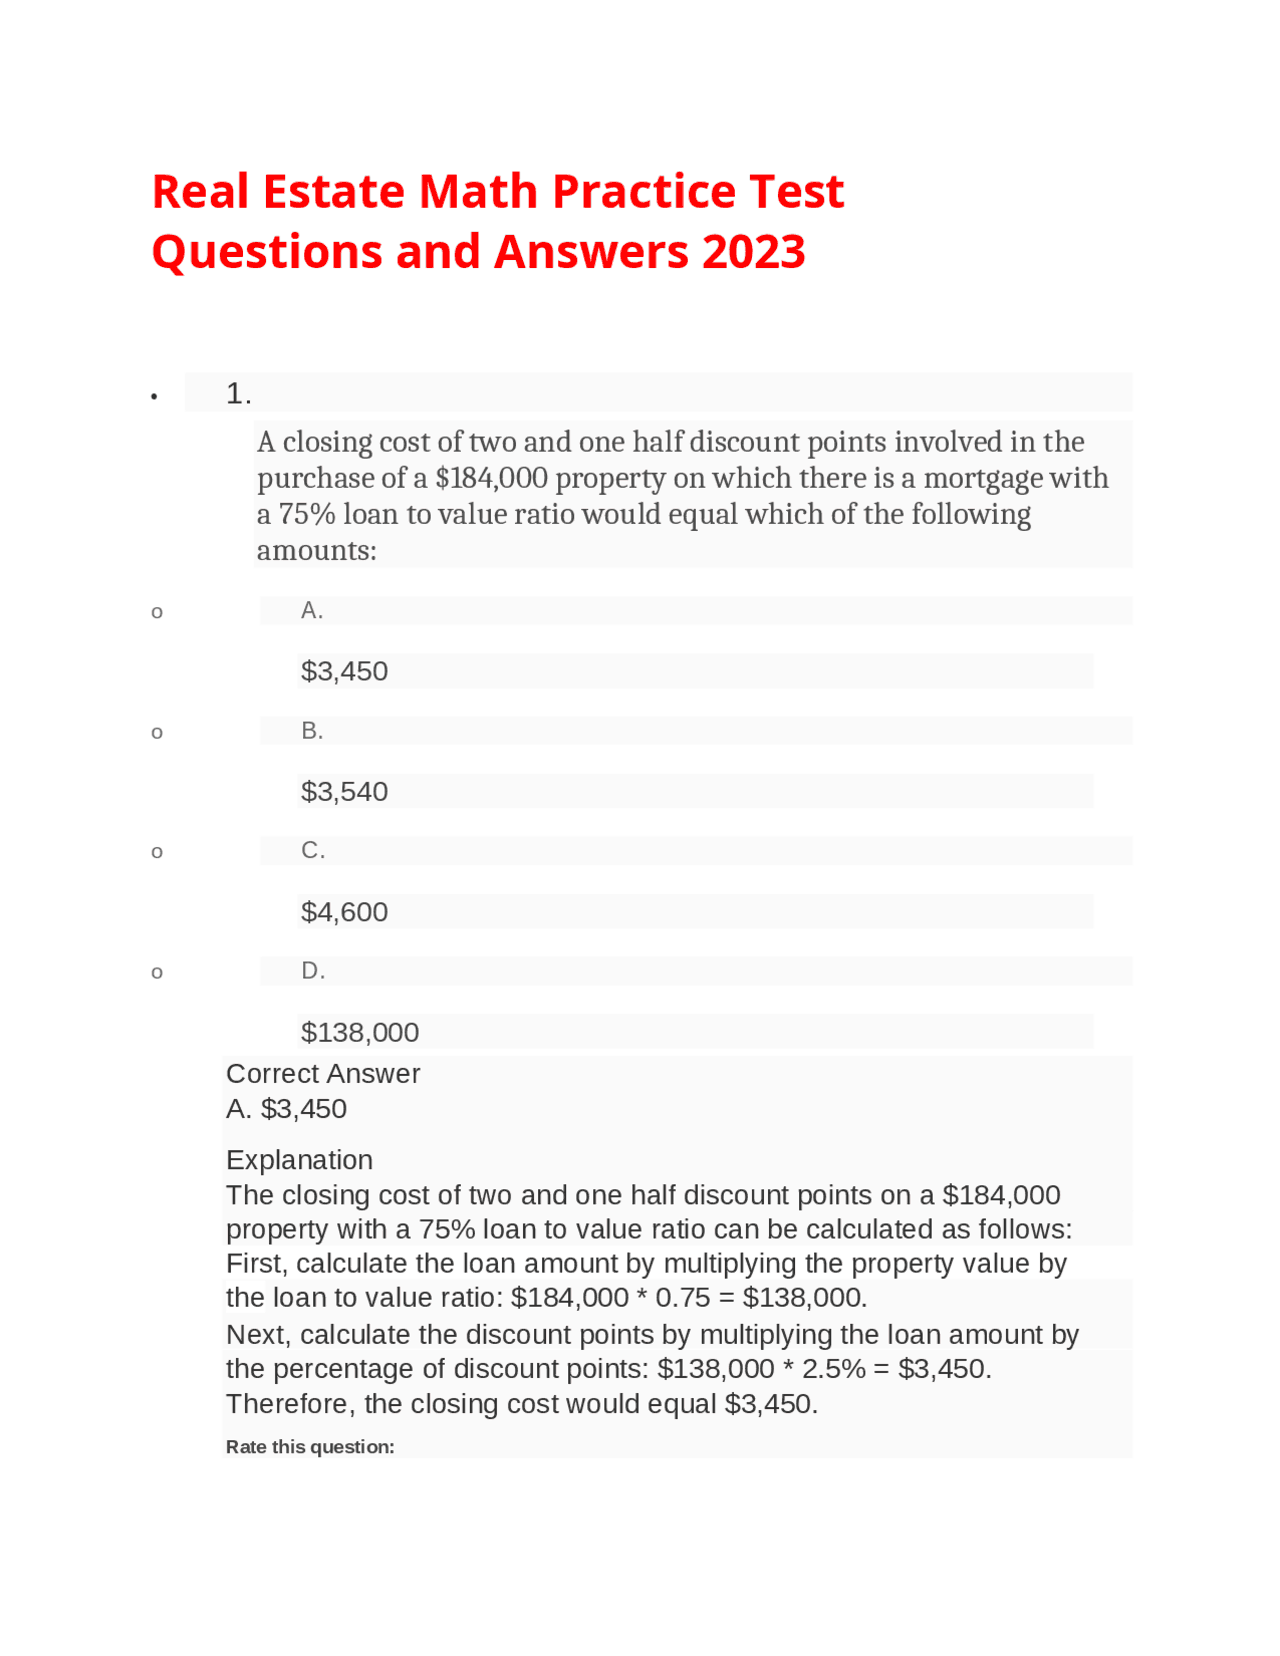
M = P × [r(1+r)^n] / [(1+r)^n - 1] Where P is the principal, r is the monthly interest rate, and n is the total number of payments. This is where most people fumble because they try to do it by hand instead of just using a financial calculator or spreadsheet. On a $500,000 loan at 6.5% over 30 years, that's roughly $3,160 per month or $37,920 annually. If the NOI is $52,000, your DSCR is 1.37. Clean deal for most lenders. Commission and Closing Cost Split Problems
These come up constantly in transaction analysis and they're simpler than people make them. A 6% commission on a $450,000 sale is $27,000. Split between listing and buying agent at 50/50, that's $13,500 each. But here's the nuance that matters: some brokerages have different splits, and some deals have broker coordination fees baked in. I worked a deal last year where the listing side had a 2.5% cooperate offer and a 50/50 split with the brokerage, meaning the agent actually walked away with $5,625 from the buyer's side portion alone, not the $13,500 someone would calculate blindly. Closing costs vary by market but typically run 2-5% of the purchase price for the seller and 3-5% for the buyer. When you're analyzing an investment purchase, you need to factor the buyer's closing costs into your total cash required. A $350,000 purchase with 4% closing costs means $14,000 at closing on top of your down payment. If you're doing an 25% down payment, you're bringing $87,500 + $14,000 = $101,500 to the table, not just the down payment. ROI and Cash-on-Cash Return Problems
Cash-on-cash return is annual pre-tax cash flow divided by total cash invested. This is different from ROI, which factors in appreciation and equity build. Beginners consistently conflate the two. Let me show you with a concrete example. Property price: $400,000
Down payment (25%): $100,000
Closing costs (3%): $12,000
Immediate repairs: $8,000
Total cash invested: $120,000 Monthly rent: $3,800
Annual rent: $45,600
Operating expenses (40% of rent): $18,240
NOI: $27,360
Annual debt service: $28,200 (on a $300,000 loan at 7% over 30 years)
Annual cash flow: -$840
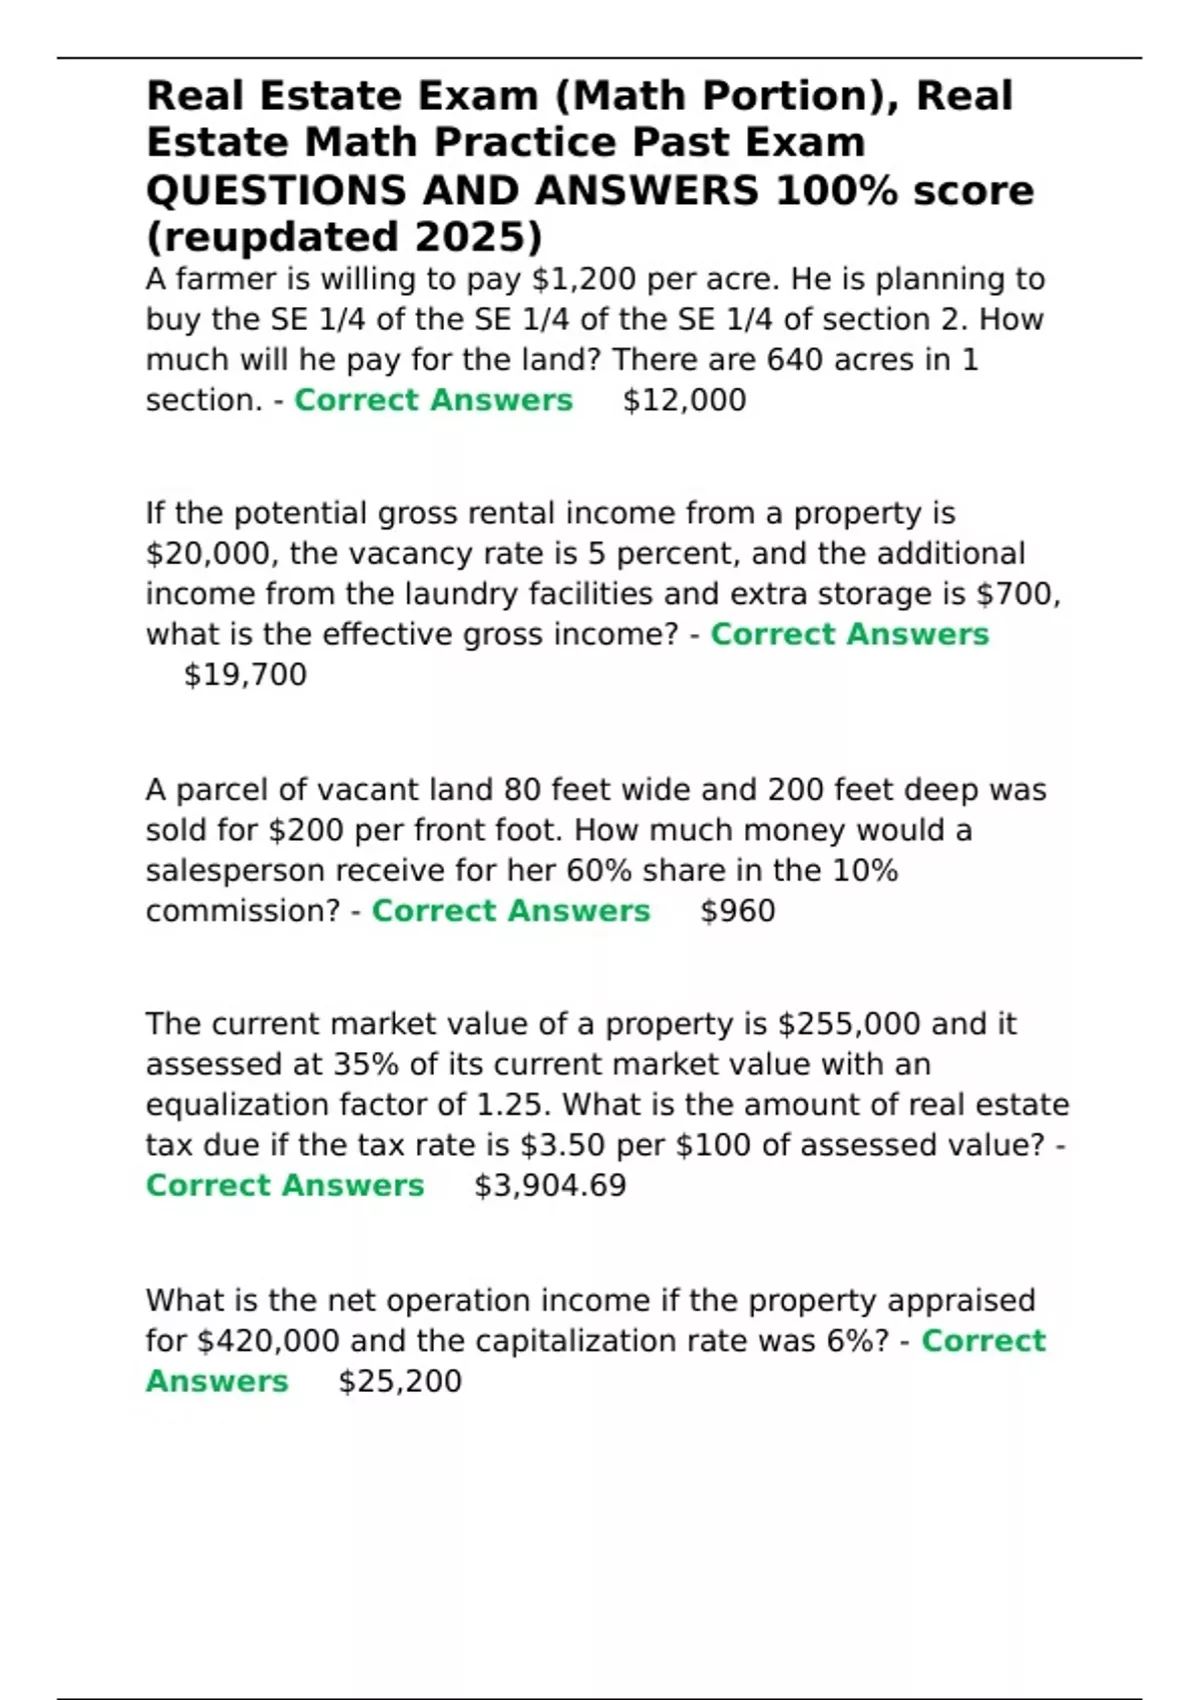
That's negative cash flow. The cash-on-cash return is negative 0.7%. Most people would have looked at the $27,360 NOI and thought this was a decent deal. The debt service wiped it out. This is exactly why you need to model the debt service before you fall in love with a property. I've walked away from deals that looked positive on paper because I forgot to include the debt service in my head and was only looking at NOI margins. Lot Yield and Development Problems These show up when you're evaluating land or multi-family development. If a parcel is 87,120 square feet (exactly 2 acres) and local zoning allows units at a density of 15 units per acre, you can develop 30 units. At $120,000 per unit land cost allocation, that's $3.6 million in land value supporting that density. If you're paying more than that per unit, you're overpaying for the land relative to what the zoning allows.
The tricky part here is always the usable versus gross area. A 5-acre tract might only yield 3.2 acres of buildable land after setting aside roads, utilities, green space, and setback requirements. I've seen developers bid on 5 acres at 12 units per acre for 60 units, then find out after entitlement that only 40 units were actually permit-able. The math looked great until it hit the planning department.
The Problems People Actually Mess Up
Here's the stuff that doesn't show up in textbooks but will cost you money: Tenant improvement reserves. Most pro formas understate TI costs. The standard assumption is $2,000-$5,000 per unit turnover. If you're replacing carpet, painting, appliances, and locking everything up, $3,000 per turnover is realistic for a mid-market apartment. Over a 10-year hold with 20% annual turnover, that's roughly 2 turnovers per unit, or $6,000 per unit in TI over the hold period. On a 40-unit building, that's $240,000 you need to reserve. If your pro forma doesn't include this, it's wrong. Captioning management fees twice. Property management is typically 8-10% of effective gross income. But if you're also budgeting for a leasing fee or acquisition management fee on top of that, you need to make sure you're not layering percentages on the same dollar figure. I once saw a pro forma where management was calculated at 10% of NOI and then again at 5% of gross income. That's roughly double-counting about 12-15% of your management expense, which materially screws up your cash flow projection.
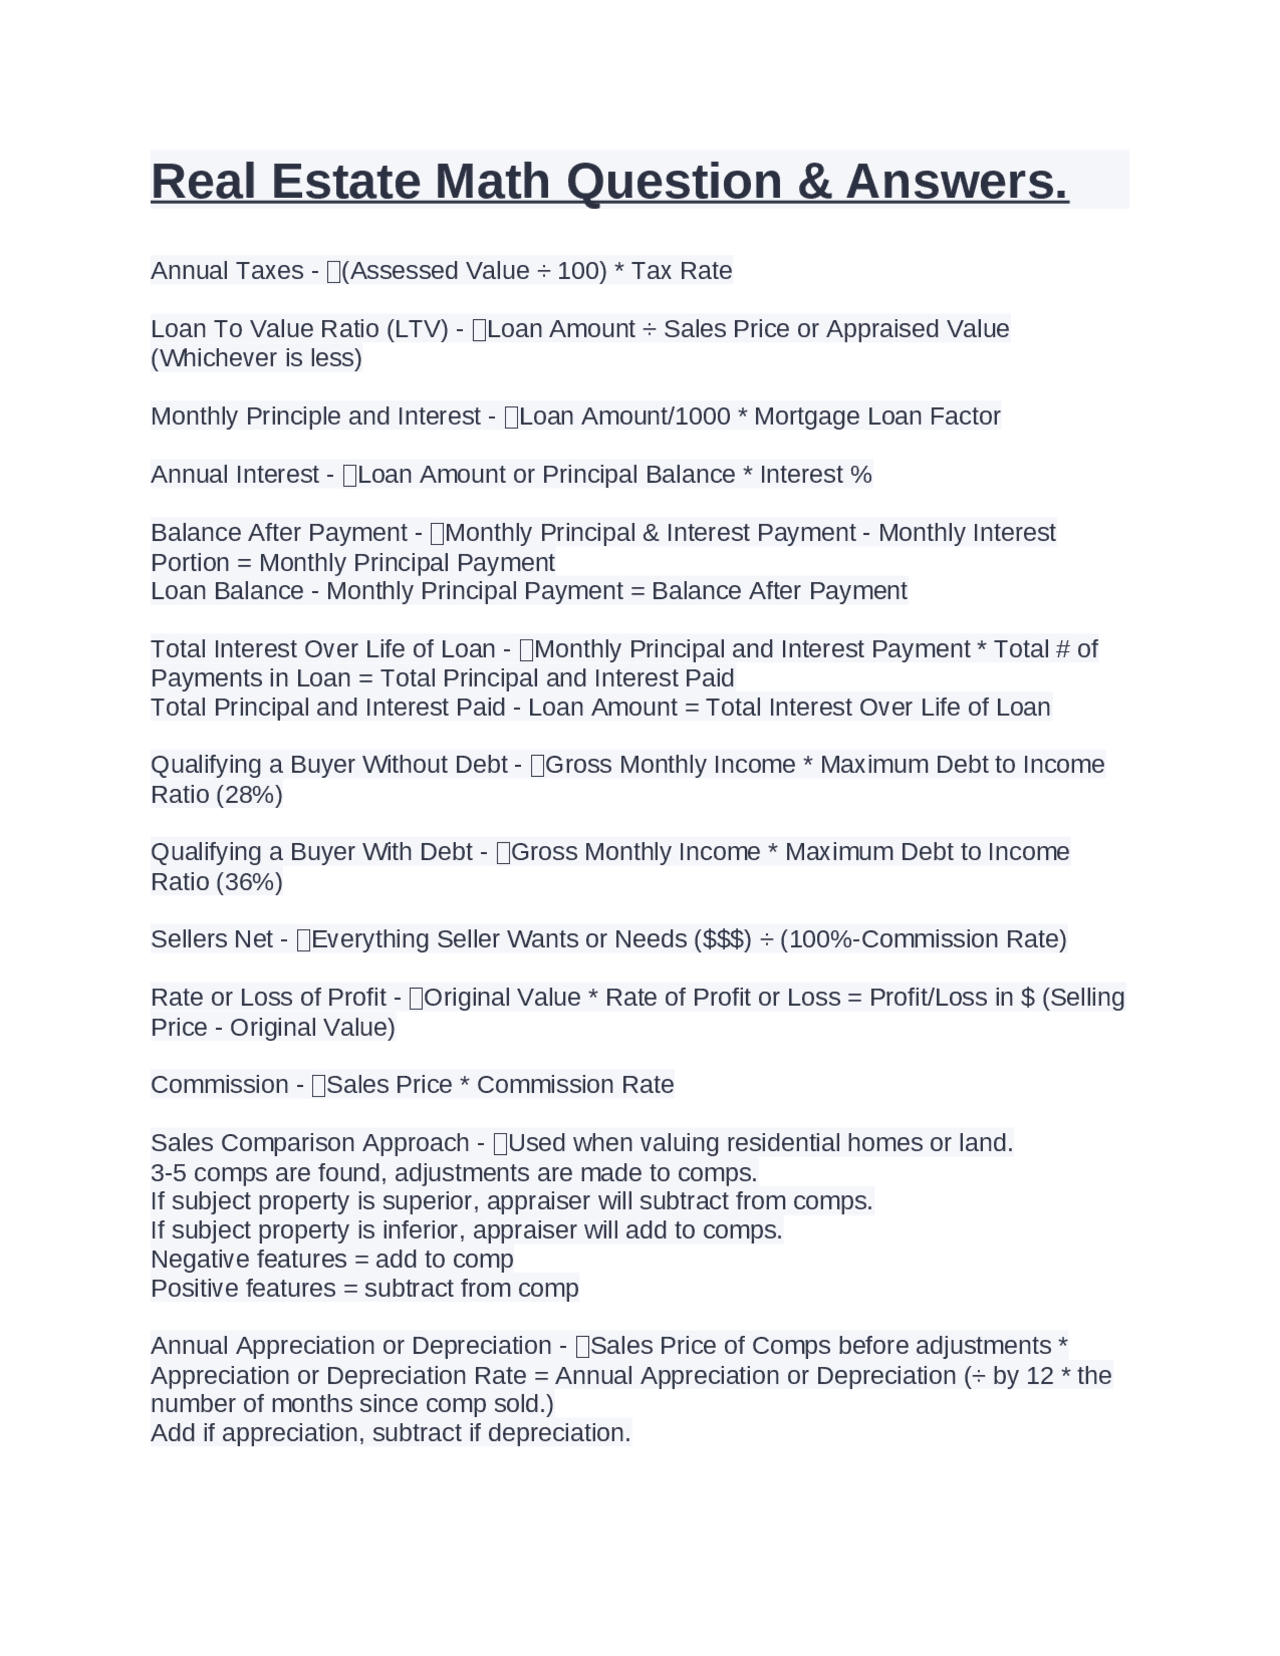
Ignoring the sponsor equity waterfall in syndication math. If you're analyzing a deal as a limited partner, the promote structure changes your actual return significantly. A typical 7% preferred return with a 70/30 split after that means you're not getting 70% of all profits—you're getting 70% of profits above the 7% hurdle. This makes the math more complex and most spreadsheets handle it poorly. I built my own model for this because every template I found either ignored the water fal or assumed a single trigger point when the deal actually had two tiers (a 12% catch-up and then an 80/20 split). Proration errors at closing. Property taxes, rents, and HOA fees all get prorated at closing, and doing this wrong is the most common simple mistake. If the seller has already collected November and December rent but the closing is October 15th, you need to credit the buyer for those two months. But if the rental is $2,400/month and you prorate by day, that's $2,400 × 46 days / 30 days = $3,680 credit to the buyer, not $4,800 which you'd get if you just subtracted two full months. The daily proration is the correct method and closing attorneys typically handle this, but if you're analyzing the numbers yourself without understanding the proration logic, you won't catch when it's done incorrectly.
How to Build a Pro Forma That Doesn't Lie to You
Start with a spreadsheet. Not a calculator. Not your phone. A spreadsheet where every number traces back to an assumption you can see and adjust. First tab: income. List every revenue source separately—market rent, other income (laundry, parking, pet fees), and then apply vacancy and credit loss as a percentage line item, not a guess. I use 5% vacancy plus 1% collection loss for stabilized multifamily in most markets. That's 6% total, which is conservative but not paranoid. In softer markets or newer buildings with high turnover, I bump that to 8-10%. Second tab: expenses. Group them by category. Taxes, insurance, utilities, maintenance CapEx reserve (this is the one everyone skimps on—use $500-$1,000 per unit per year depending on asset class and age), management fee, property management oversight if self-managed, legal and accounting, and miscellaneous. Total these up and divide by effective gross income to get your expense ratio. For a well-run apartment building, 35-45% is typical. If your expense ratio comes in below 30%, you're probably under-budgeting somewhere. Above 55%, the deal likely doesn't work unless you're in an extremely high-rent market.
Third tab: debt and cash flow. Input your loan terms and calculate debt service. Subtract from NOI to get annual cash flow. Divide by total cash invested to get your cash-on-cash return. Run three scenarios: base case, downside (10% higher vacancy, 5% lower rent), and upside (5% lower vacancy, 5% higher rent). If your downside case still shows positive cash flow and a DSCR above 1.15, the deal is genuinely sound. If it flips negative, you're relying on perfect conditions, which is how deals go wrong. I run this entire process in about 45 minutes for a standard acquisition analysis. The first time I did it, it took me three hours because I was still looking up formulas. Now it's muscle memory. That's the difference between knowing the math and actually being able to use it under pressure when a deal is moving fast and the seller is waiting on your numbers.

When the Math Breaks Down
No pro forma is perfect. The biggest limitation is that all your inputs are estimates. You might have perfect math with garbage assumptions and still make a bad decision. I've seen investors with flawless spreadsheets lose money because they assumed rents would grow 5% annually in a market where they were actually flat. The math was right. The assumptions were wrong. The second limitation is that static models can't capture dynamic market shifts. If you lock in a 30-year pro forma and interest rates jump 200 basis points in year three, your refinancing math is completely different than what you modeled. I've started running sensitivity tables on interest rates as a second layer—what happens to my cash flow if rates are 1% higher, 2% higher, or if I can't refinance at all and have to sell? Some deal structures simply resist clean mathematical analysis. Value-add multifamily with phased renovations, mixed-use developments, or ground-up construction all have variables that shift so frequently that a detailed pro forma is almost meaningless beyond the first six months. For these, I keep the model simpler and run wider sensitivity bands. A 2% error margin on a stable Class A property is worth worrying about. A 2% error margin on a ground-up development is noise.
If you're learning this for a licensing exam, the formulas are straightforward and the problems are clean. The math works out to nice round numbers because that's how test questions are designed. Real deals don't work that way. The numbers are messy, the assumptions are uncertain, and the point isn't to get a precise answer—it's to understand whether the deal makes sense directionally before you commit capital. The math is a tool for eliminating obviously bad deals, not for confirming that a good deal is good. If you need the math to convince you a deal works, it probably doesn't.

