What You Actually Need to Know Before Walking Into the Room
Most people preparing for these interviews treat them like a trivia game. They memorize definitions of IRR, MOIC, and pro-forma without understanding how those numbers actually move in a real fund. That approach gets you through the first screening but falls apart by the technical round. I have watched candidates who could recite every formula in the back of a textbook choke on a simple question about how acquisition costs flow through a construction period. The truth is that real estate private equity interview questions are designed to separate people who have actually built models from people who have watched someone else build one. The bar isn't particularly high. You do not need to be a walking spreadsheet. You need to show that you understand the mechanics of a deal and the language that operators use every single day.
Real Estate Private Equity Interview Questions Breakdown
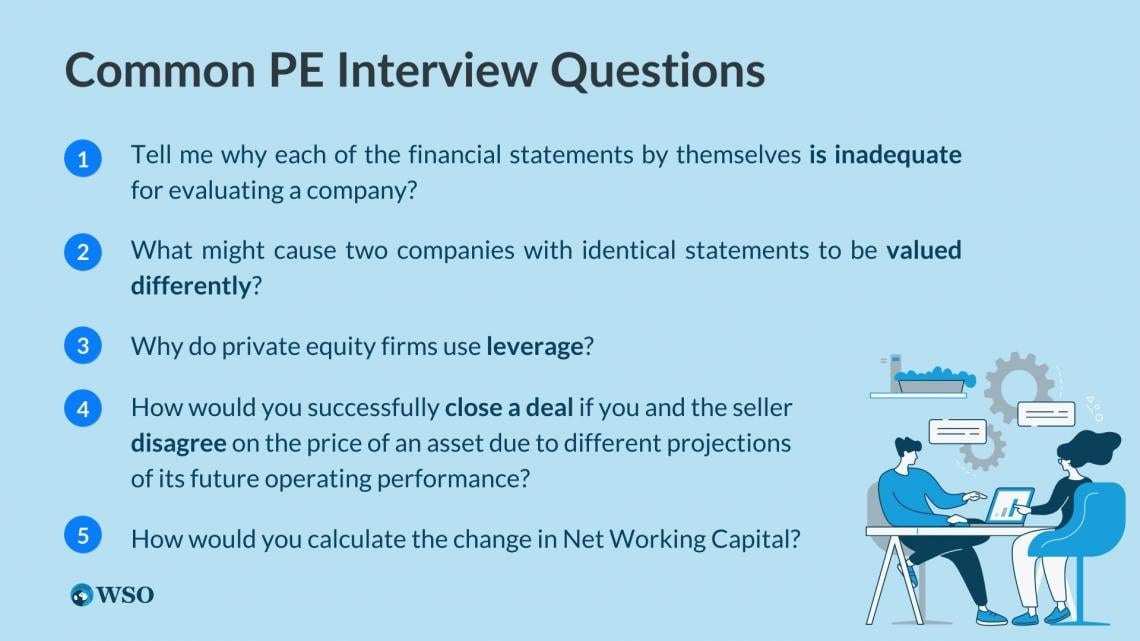
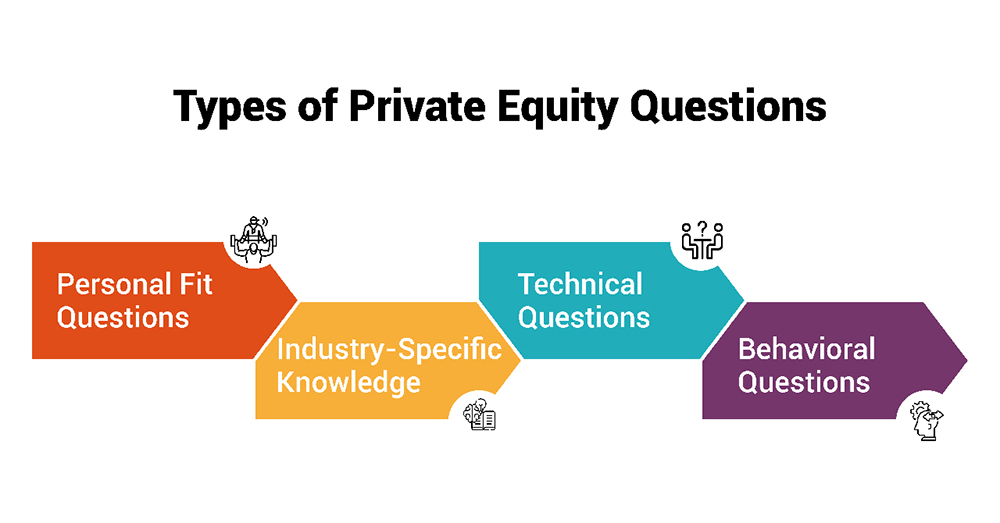
Let me walk through what typically comes up and what they are actually testing when they ask it. The most common category is valuation and returns. They will ask you to calculate IRR and equity multiple on a simple hold-and-refi scenario. This sounds basic but most candidates lose points on timing assumptions. They will put acquisition costs in month zero and property tax bumps at year one without being told. In practice, acquisition costs sit in month zero and your expense growth starts at closing. If the refinance happens at month twenty-five, they want to see the debt placed at that point, not at year three. Small timing errors compound into five to eight percent differences on final returns, which is exactly what separates an acceptable answer from a strong one. The second category is underwriting logic. They will give you a set of assumptions and ask what drives the return. This is where people wander. They start talking about market trends and supply pipelines before establishing the actual mathematical drivers. The answer is usually simple. It is almost always entry cap rate compression, lease-up velocity, or cost discipline. If you can point to the specific line item that moves the needle and quantify its impact, you demonstrate something most candidates cannot. You know how to read a model instead of just populating one. There is also the deal structure question. They will ask about waterfalls, promote splits, and preferred return mechanics. Here is the thing nobody tells you during preparation. Most interviewers do not care about your ability to draw the waterfall diagram perfectly. They care about whether you understand why the structure exists in the first place. A 7 percent preferred return with a 70-30 split after that hurdle is not arbitrary. It is designed to align sponsor skin in the game with limited partner cash flow expectations. When you explain the incentive alignment rather than just describing the tiers, you sound like someone who has sat in investor committee meetings instead of studying flashcards.
I ran into a situation last year where a candidate I was evaluating could build a full pro-forma from scratch but could not explain what happened to the debt service when a bridge loan converted to permanent financing. The model changed dramatically between months eighteen and twenty-four because the interest-only period ended and amortization kicked in. He had missed it entirely. We use that exact edge case sometimes because it reveals whether someone has actually wrestled with a construction-to-perm transition or if they have only modeled greenfield purchases with stable financing. The workaround is straightforward. You always stress test your debt schedule around refinancing events. I mark those cells in yellow in my own models so they never get overlooked during a walkthrough. Another common area is market and asset class knowledge. They will throw out a city and an asset type and ask for your opinion. Do not give them a generic answer about population growth and job numbers. Pick a specific submarket, reference a recent transaction or delivery, and connect it back to how it would affect your assumptions. Saying that Dallas is oversupplied with apartments tells them nothing. Saying that the Uptown submarket absorbed forty percent less Class B stock than the pro-forma assumed in a Q4 2024 deal you saw reported tells them you follow the market. The accounting and financial statement question always comes up in later rounds. They will ask you to walk through how a real estate investment flows through the three statements. Most people stumble on the cash flow statement because they forget that depreciation is a non-cash add-back while debt principal paydown is a cash outflow that does not appear on the income statement. If you can clearly separate the two and explain why one stays on the cash flow sheet and the other disappears, you have crossed a threshold that many analysts never clear.
Get the Full Details

Here is a counter-intuitive point that beginners routinely miss. They spend hours grinding through case studies involving complex value-add situations with mixed-use buildings and phased deliveries. Meanwhile, the interview actually hinges on your ability to cleanly model a core-plus stabilization scenario in twenty minutes flat. Strong funds know that if you cannot reliably handle the straightforward case, you will destroy yourself on the complicated one. Practice the simple stuff until it is automatic before you chase the fancy scenarios. Another thing worth noting is that many candidates over-index on financial modeling and completely ignore the behavioral and fit questions. They will ask why you want to work in real estate specifically rather than private equity more broadly. They want to hear that you understand the physical asset side matters to you. The spread between debt and equity returns in real estate is different from tech or healthcare. You are taking on illiquidity and operational risk, not just financial engineering risk. Frame your answer around that distinction and you will stand out from the hundred people who gave the same generic private equity motivation speech. Let me be clear about what this process does not do well. These interviews heavily favor candidates who have completed a relevant internship or have access to someone who can walk them through a live deal model. People coming from unrelated graduate programs or non-finance backgrounds face a structural disadvantage that no amount of study can fully overcome. There is also a bias toward certain schools and certain funds that creates an echo chamber of acceptable answers. If your thinking falls outside the standard playbook, you will sometimes be rated lower not because you are wrong but because you are unfamiliar with the template they are grading against.
If you are preparing on your own, here is the most efficient path. Take a recent public transaction from a source like CoStar or a REIT earnings call. Pull the actual cap rate, the NOI, and the sale price. Reconstruct the exit model backwards from the transaction. See what implied return the sponsor achieved. Then build a forward version with your own assumptions and compare the two. This exercise takes about two hours the first time and teaches you more than any case study prep book ever will. It forces you to confront the gap between textbook assumptions and what actually transpired in the market. I also recommend practicing your answers out loud with a timer. You would be surprised how many good candidates think clearly on paper and freeze when put on the spot. Record yourself explaining a full underwriting cycle from acquisition to disposition. Listen to it. You will catch rambling, filler words, and moments where your logic breaks down. Most people skip this step and then blame the interviewer for being unfair when they struggle to articulate something they understood perfectly in writing. The bottom line is that real estate private equity interview questions reward people who understand both the numbers and the operational reality behind them. Build clean models. Know your assumptions. Be able to defend every line item. And do not pretend you care about everything equally when they ask about asset class preferences. Pick one, back it up with specific evidence, and move on. The process is tedious but it is not opaque if you have actually spent time around a real deal.