What You Actually Need When Closing Deals
Most people think a cheat sheet is just a laminated card with a few formulas. It isn't. A proper one lives on your desk, your phone, and sometimes your clipboard during showings. I keep mine in three layers: one for quick numbers, one for process flow, and one for the edge cases that bite you at 4 PM on a Friday. Here's how I built mine and why it matters when there are thirty minutes left on a closing table and someone asks about prorated property taxes.
Real Estate Reference Guide Cheat Sheet
Start with the formulas that actually come up in practice, not the ones from a textbook chapter you'll never reference. The ones that matter daily are: Gross Rent Multiplier (GRM) — Property price divided by gross annual rental income. A $500,000 building collecting $50,000 in annual rent has an GRM of 10. Used for quick screening, not underwriting. If you rely on GRM alone to decide whether to write an offer, you'll miss operating expense differences between properties that eat returns alive. Cash-on-Cash Return — Annual pre-tax cash flow divided by total cash invested. Cash flow after debt service, vacancy, CapEx, and management taken out. Invested $80,000 in down payment and renovations, the property nets $9,600/year after all expenses. That's a 12% cash-on-cash. Beginners skip the vacancy and CapEx reserves and pretend the number is real.
Debt Service Coverage Ratio (DSCR) — Net operating income divided by annual debt service. Lenders want 1.25 or higher on investment properties. An NOI of $60,000 with $44,000 in annual debt payments gives a DSCR of 1.36. Below 1.0 and you're subsidizing the loan from your personal income. Most brokers don't mention this until the underwriter flags it two weeks before closing. Cap Rate — Net operating income divided by property value. It sounds simple and it is, until people compare cap rates across markets without adjusting for land value, age of systems, and lease structure. A 7% cap rate in Chicago isn't the same as a 7% cap rate in Nashville. One has slower appreciation and older HVAC. The other has newer inventory and different risk profiles. 1% Rule and 2% Rule — Monthly rent should equal at least 1% (or ideally 2%) of the purchase price. These are screening filters, not underwriting tools. They work fast for volume markets but fail in high-appreciation coastal areas where cap rates compress so far that no deal hits 1%. I learned this the hard way in 2019 when I passed on three properties in Phoenix because they ran 0.8%, then watched them refinance at 22% equity gains within eighteen months.
Get the Full Details
Proration Calculations — This is where deals actually stall. Property taxes, HOA fees, and rents get prorated daily using a 360-day year in most states, not 365. The seller owes for the day of closing if they occupy it. Some contracts say buyer pays; some say seller. Always check the purchase agreement line item. I've seen two separate transactions in the same suburb where the same proration was handled differently because the form version changed between counties. The cheat sheet should also have a section for closing cost ranges by state, a list of typical lender requirements for each loan type, and a quick-reference table for comparable sale adjustments. Adjustment ranges matter more than the comps themselves. A half-bath adds $4,000 to $8,000 in most mid-tier markets. Roof age can swing $10,000 to $25,000. You don't memorize these. You keep them visible so you're not guessing during negotiations.
Building the Document
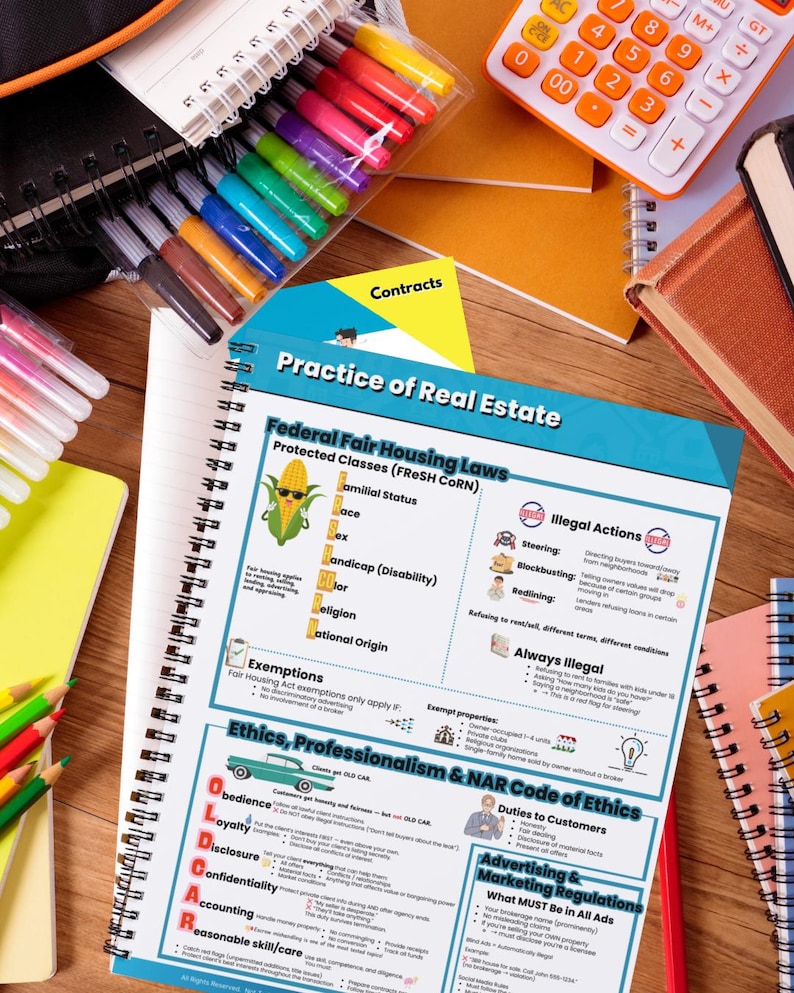
I use a single spreadsheet with three tabs: Formulas, Process Flow, and Common Pitfalls. The Formulas tab has every calculation with the variables clearly labeled. The Process Flow tab maps the timeline from contract to close with responsible parties next to each milestone. The Pitfalls tab is where the war stories live. Here's a specific example from my Pitfalls tab that took me six months to learn properly. In 2022 I was reviewing a commercial deal where the tenant's triple-net lease had a base year clause with a $2.50 per square foot operating expense stop. The property's actual OpEx came in at $4.80. The seller's pro forma showed the tenant covering the excess. It didn't account for the fact that the municipality had just reclassified part of the parking lot, triggering a $18,000 capital assessment that rolled into that year's OpEx. The lease language said tenants share capital assessments pro rata, but the attachment listing capital reserves was missing page three. I caught it during due diligence because my cheat sheet had a checklist item for "verify all lease exhibits match executed copy." Without that line, the buyer would have signed with an incomplete document and absorbed the assessment silently. The workaround was straightforward: every time a lease exhibit reference appears, I pull the full exhibit stack and cross-check page counts against the exhibited table of contents. It adds twelve minutes to my review. It saved me from a $18,000 surprise and a conversation with a client who wouldn't have understood where the number came from.
How It Works in Practice
You don't memorize the sheet. You train yourself to reach for it at the right moment. During a showing, the Formulas tab on your phone gives you a quick GRM check against the list price. At the offer stage, the Process Flow tab reminds you what contingency windows look like in your county. Before the closing table, the Pitfalls tab catches the stuff that doesn't have a formula. The hardest part is keeping it current. Market conditions shift quarterly. Interest rate environments change lender overlays. County recording fees adjust. I update mine every January and whenever a deal throws me something I can't immediately find on the sheet. If an item appears twice in six months, it belongs on the sheet permanently.
Where It Falls Short
A cheat sheet will not replace underwriting software, title searches, or a competent attorney. It will not help you navigate local zoning variances or predict how a new transit line affects a neighborhood three years out. It also becomes dangerous if you treat it as authoritative. The numbers on the sheet are averages and typical ranges, not guarantees. A DSCR of 1.25 that gets approved in one state may get rejected in another with the same numbers. Loan programs change faster than most people update their documents. If you're working on deals over $2 million or in multi-family assets with complex rent rolls, the cheat sheet should be a starting reference, not the final word. Bring in a broker or CPA for the structural pieces. The sheet keeps you from looking like a beginner on routine questions. It doesn't make you immune to the ones that require specialized knowledge. The version I share with new agents takes them about two weeks to internalize enough to stop pausing on basic calculations during negotiations. After that, they spend more time adding their own notes to the Pitfalls tab than reading the formulas. That's when it stops being a reference guide and starts being their actual playbook.