What You're Actually Dealing With
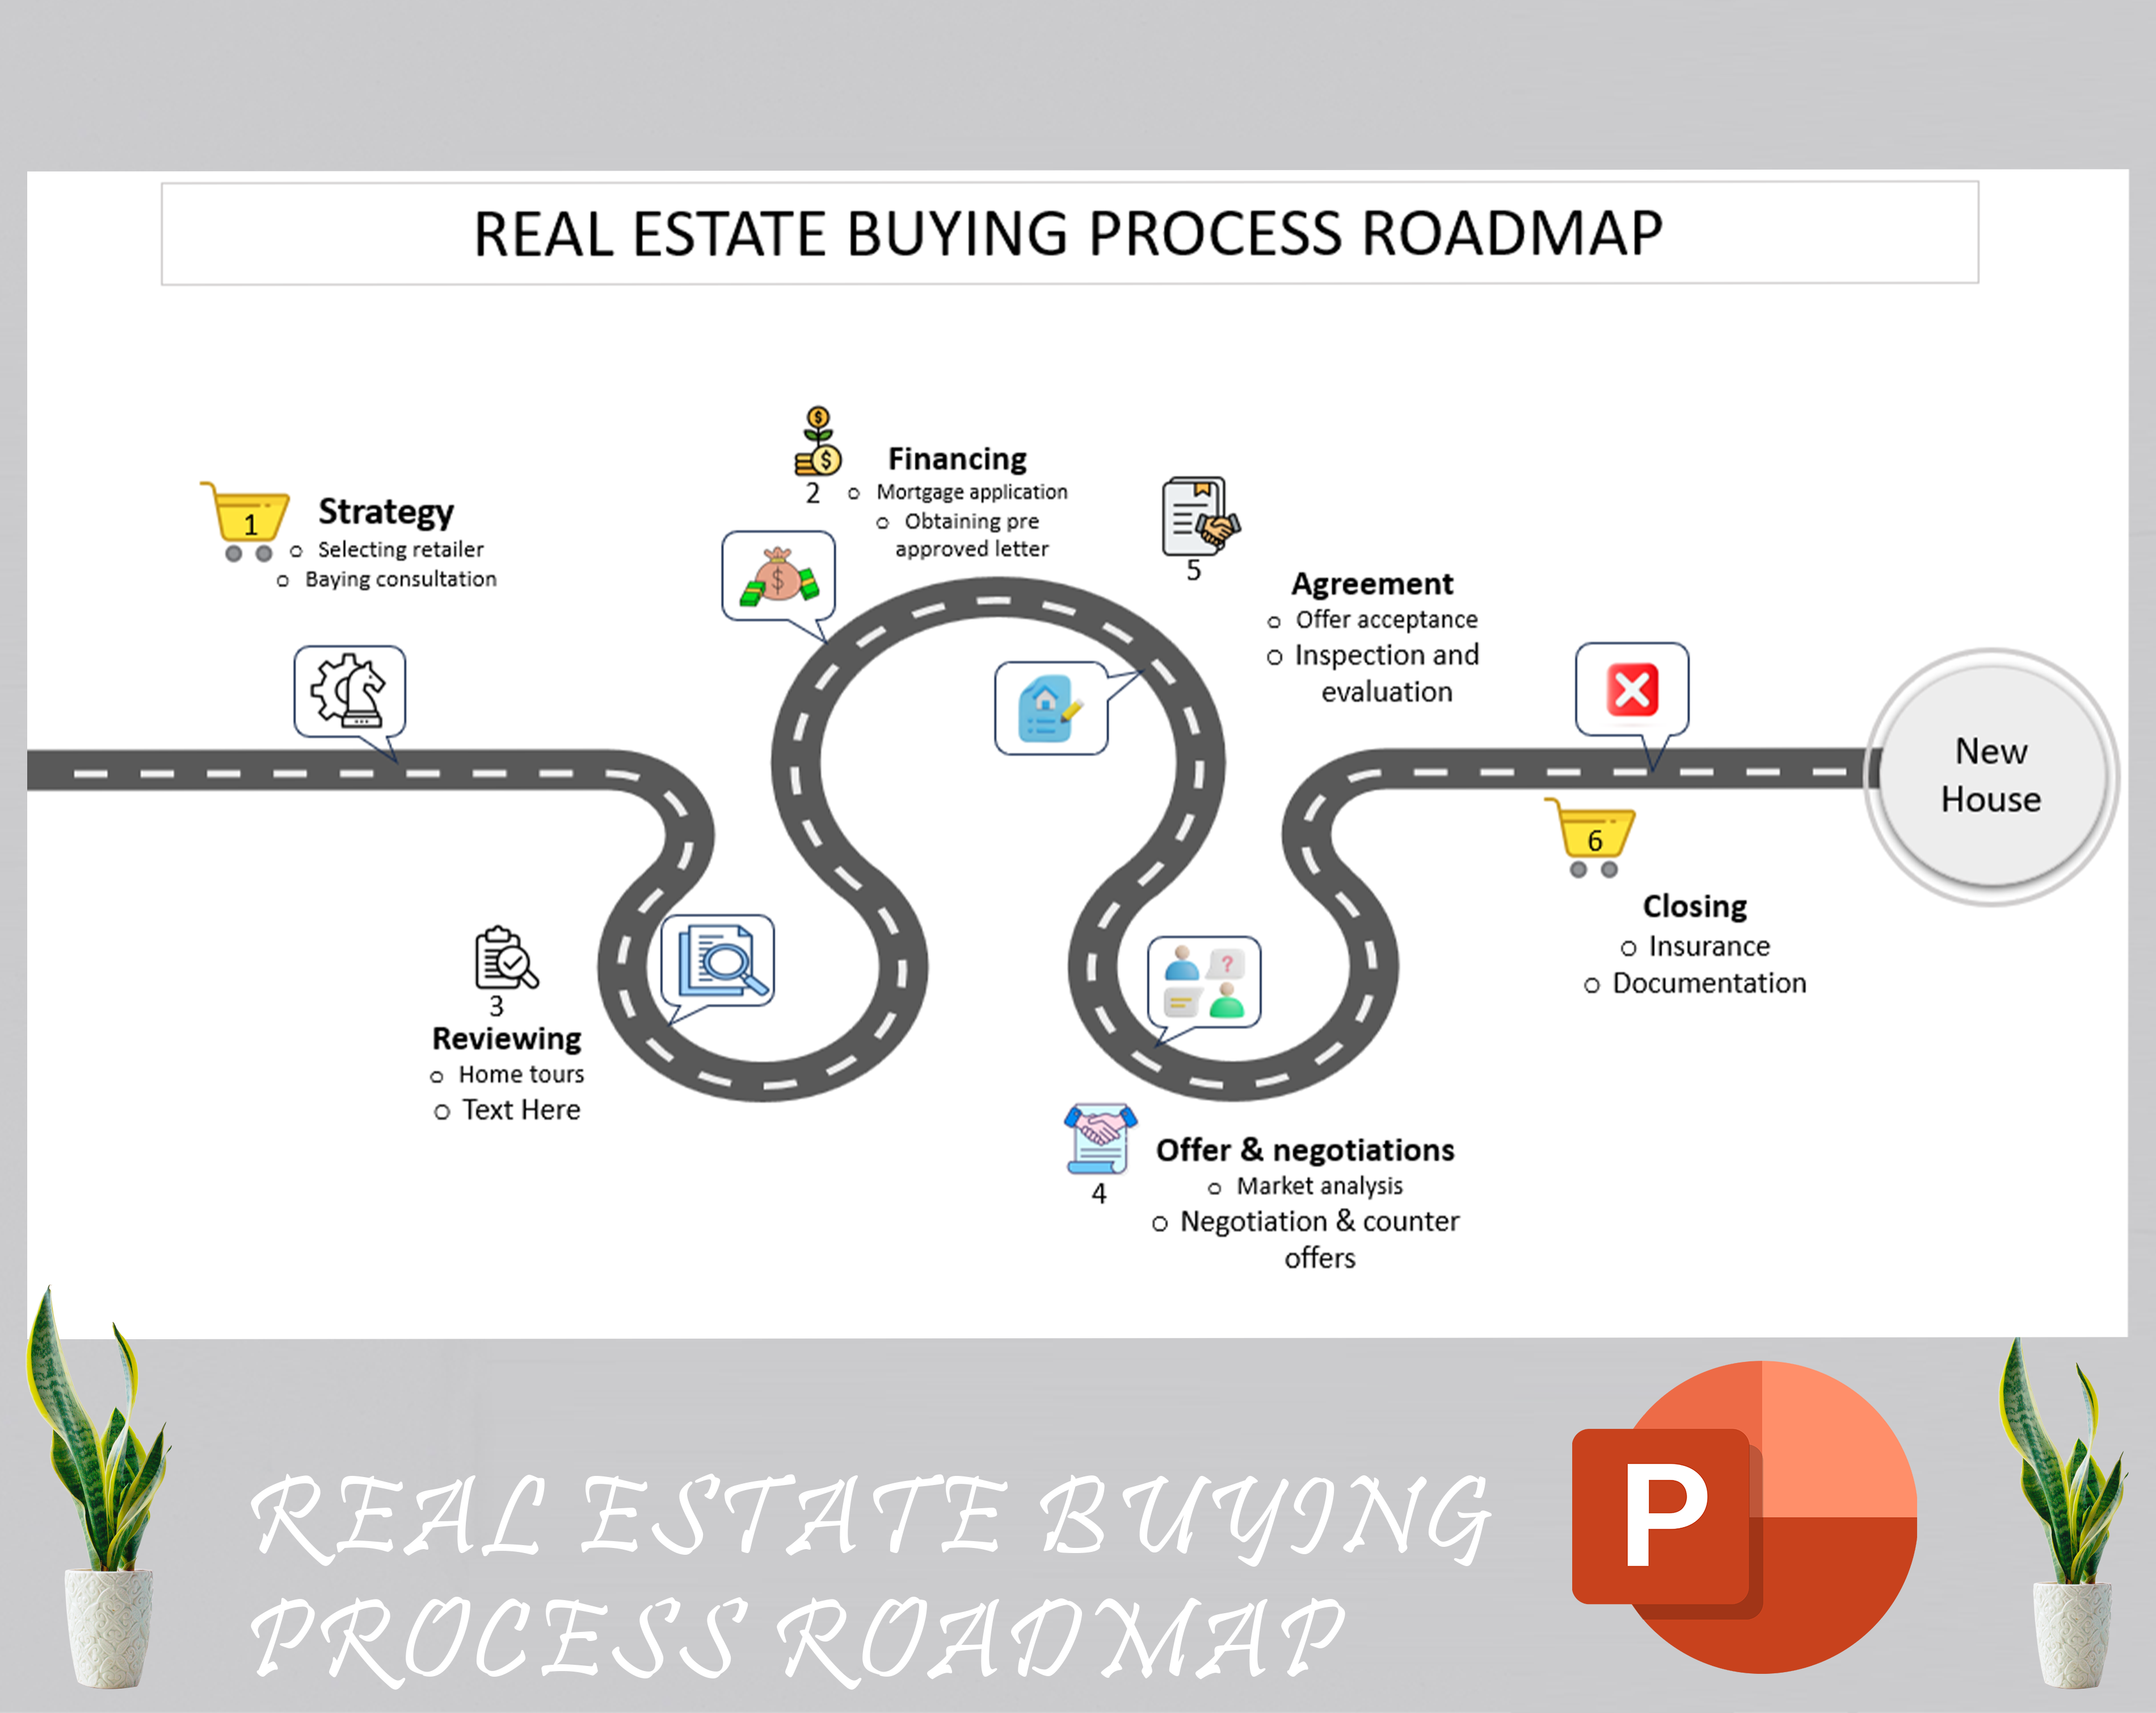
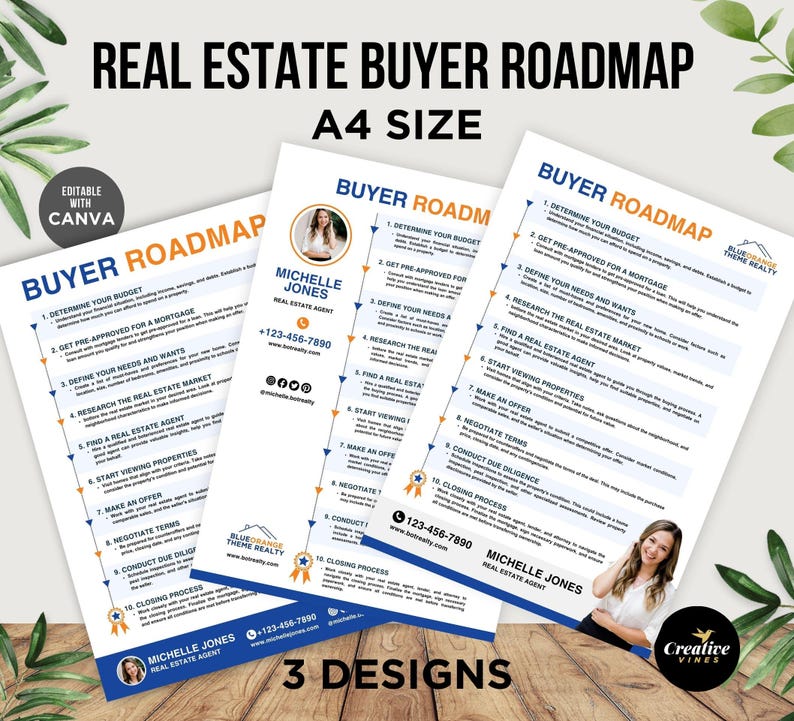
A Real Estate Strategy Guide Roadmap is not a single document you download and forget about. It's the structured path someone follows when they try to go from zero to a functioning real estate portfolio without spending three years learning everything the hard way. Most people stumble through acquisitions randomly, lose money on bad deals, and then look for a guide that would have saved them twelve months and roughly forty thousand dollars in mistakes. The first thing most guides gloss over is that your strategy has to match your actual cash flow, not some fantasy version of it. I watched a guy buy his first triplex with a 3% down loan and no reserve fund because the guide told him "start small." Two months later the toilet cracked, the water heater failed, and he was writing checks from his personal account to cover the shortfall. The guide never mentioned emergency reserves as a prerequisite step. Here is what actually works when you build this out:
Phase one is market selection. You need to understand where you are buying before you look at a single property. Job growth numbers, population trends, rent-to-price ratios in the zip codes you are targeting. I spent a weekend pulling census data and BLS employment statistics for three markets instead of driving around looking at listings. That decision alone saved me from buying in a market that dropped sixteen percent over the next eighteen months. The guide should force you to pick a market based on data, not intuition or a friend's recommendation. Phase two is capital strategy. This is where most roadmaps fail. They tell you to get pre-approved and start looking. They do not break down the difference between a 20 percent conventional loan, a house-hacking FHA situation, a DSCR loan for investment properties, or a BRRRR cycle that requires refinancing within eighteen months. Each path has different qualification thresholds and different risks. I learned this the hard way when I tried to use a standard investment property loan on a property I was planning to live in part of. The lender flagged it, delayed closing by eleven days, and the seller nearly walked. Switching to an owner-occupant product fixed it, but only because I understood the distinction before going under contract. Phase three is the deal criteria. You need written numbers before you look. Gross rent multiplier, cap rate floor, cash-on-cash return minimum. I use 8% minimum cash-on-cash and a negative cash flow tolerance of zero in my target markets. If a property does not clear those thresholds before I even schedule a showing, I move on. Saves about four hours per week on average by filtering out the noise early. Most people schedule showings first and run numbers later. That reverses the entire process and puts you in a reactive position instead of an analytical one.
Phase four is execution and scaling. Once you close your first deal, you need a repeatable process. Property management setup, tenant screening, maintenance vendor relationships, tax strategy for depreciation and cost segregation. The roadmap should include a timeline for when to self-manage versus when to hand it off. Self-managing works until you have three or four units and you are missing maintenance calls at work. Then your time becomes the bottleneck and your returns drop because you are too overwhelmed to evaluate new deals properly.
Get the Full Details
Where the Common Guides Fall Apart
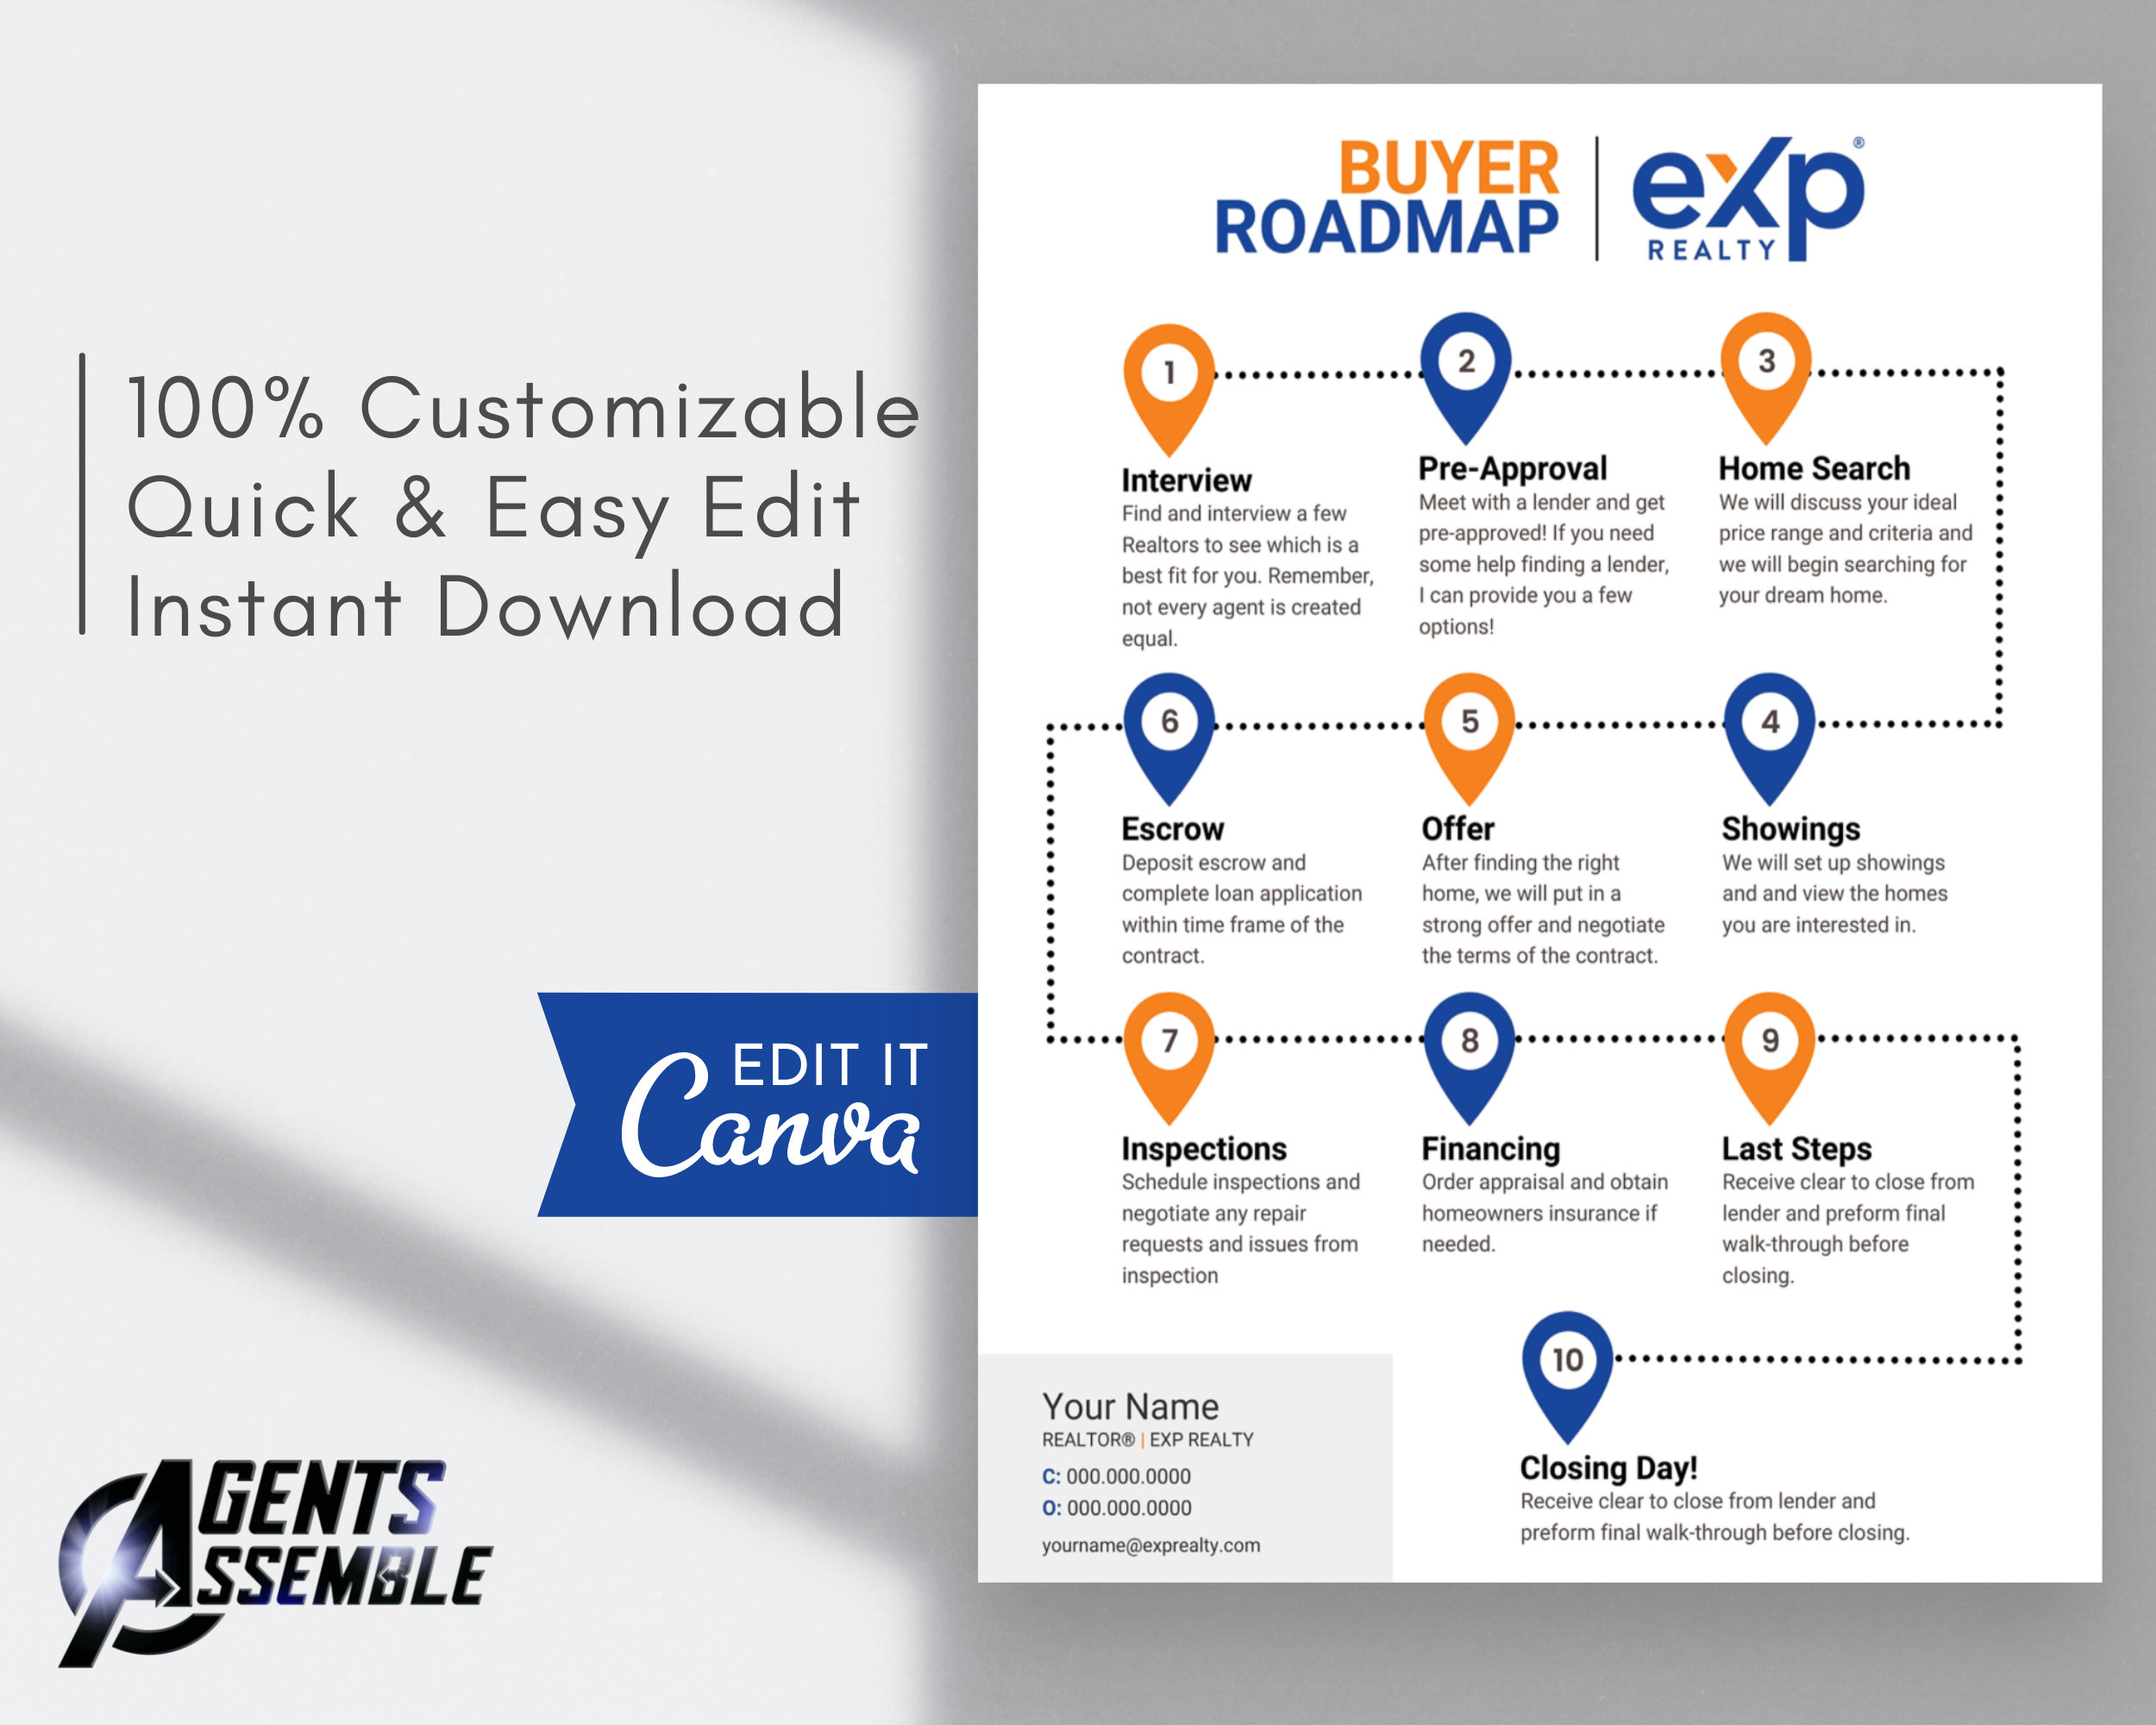
The biggest problem I see with free or cheap roadmaps is that they assume a linear progression. Buy one, manage it, refinance, buy another. Real life does not work that way. Markets change during your BRRRR cycle. Interest rates shift between acquisition and refinance. A major employer relocates out of your market between when you buy and when you plan to exit. I ran into this exact problem with a duplex I refinanced in 2022. By the time the appraisal came in, rates had jumped enough that my cash-out was twelve thousand dollars less than projected. The guide had assumed a static rate environment. It did not account for the Fed moving. Another blind spot in most roadmaps is the exit strategy. People plan how to enter but rarely plan how to leave. Are you holding for cash flow? Flipping in five years? Selling to a 1031 exchange buyer? Each exit path requires different holding period calculations and tax implications. Cost segregation studies only make sense if you are holding long enough to benefit from accelerated depreciation before selling. If you are flipping in three years, you are better off doing a quick cosmetic refresh and moving on. The roadmap needs to account for which scenario applies to your situation.
What I Would Add to Any Standard Roadmap
Most guides skip the legal and structural setup entirely or bury it in appendix material. Entity formation, umbrella insurance, tenancy structure, operating agreements for partnerships. I set up an LLC for each property after my second acquisition because the liability protection mattered once I had equity on the line. It took me about three hours and maybe six hundred dollars in legal fees across two states. The guide should tell you exactly when that threshold hits and give you a checklist for it. Another gap is the psychological component. Buying your first rental is terrifying. You are handling strangers' problems, unexpected expenses, and lease violations with no training. I ignored this entirely in my early attempts and burned out fast. Once I joined a local investor group and started talking to people who had been through the first two years, everything normalized. The roadmap should include community resources or support structures, not just numbers and processes. If you want a solid starting point, look for a roadmap that covers market analysis methodology, financing options side by side with their pros and cons, deal screening checklists with exact thresholds, and scaling decision trees. Anything shorter than that is basically inspirational content dressed up as a guide. The ones that actually help will make you do work before you ever look at a property listing.