Things That Actually Kill Deals Before They Start
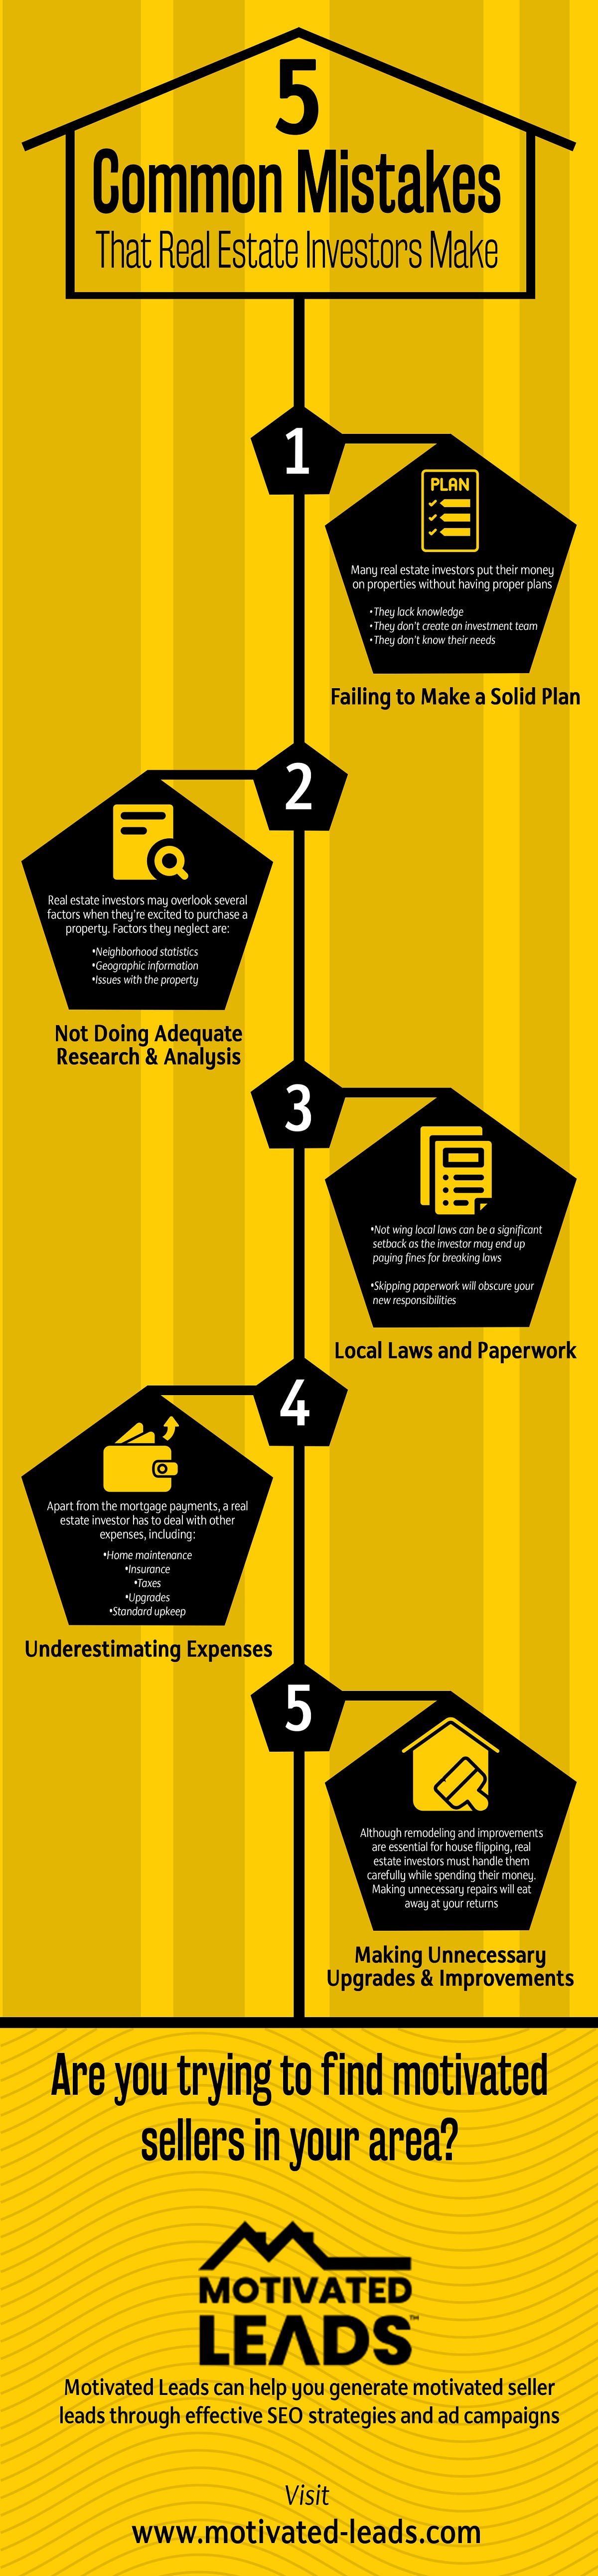
The biggest mistake most people make in real estate is assuming the spreadsheet matches reality. I watched a guy in Phoenix buy a fourplex in 2022 based on rent comps that were six months stale. By the time he closed, those units had re-priced. He was about $40,000 underwater on his pro forma before he even got the keys. This happens constantly. People pull comps, build a model, and treat it like gospel instead of a rough estimate that needs stress testing. You need to understand how vacancies actually compound. The standard rule of thumb says budget 5 to 10 percent for vacancy. That works fine when the market is balanced. But in a softening submarket, 10 percent looks generous and you end up eating two months of empty rent plus the cost of cleaning and re-listing. I had a tenant in Tampa walk three weeks before lease end during the 2024 rate spike. The unit sat for 47 days. That's not a 5 percent vacancy rate, that's a cash flow problem that went unnoticed because the numbers looked fine on paper. Another issue nobody talks about enough is the difference between gross and net operating income when you're underwriting. Beginners look at the top line and get excited. Then they discover property taxes jumped 22 percent in their county, insurance doubled because of coastal risk adjustments, and the HOA raised dues. The cap rate they thought they were getting? It was more like a third of what the listing claimed. I learned this the hard way on a small multi-family deal in Jacksonville. The seller showed me three years of receipts. The numbers were clean. What they didn't mention was a pending special assessment for a new roof on the shared building. Came to about $18,000. I walked away. The deal wasn't there once you factored in the real carry costs.
Financing Mistakes That Surprise People
Most buyers don't shop their financing the way they should. They pick the first lender who responds and lock in whatever rate comes out of their system. Rate spreads between lenders on the same product can easily be 0.375 to 0.75 percent. On a $500,000 loan over 30 years, that's roughly $11,000 to $22,000 in extra interest. That's money that could have covered three years of deferred maintenance or filled a vacancy gap. Then there's the assumption that pre-approval equals deal flow. It doesn't. Sellers and their agents care about proof of funds more than a pre-approval letter. I've seen offers rejected not because the price was wrong but because the buyer couldn't produce a bank letter showing liquid reserves equal to six months of payments after closing. In competitive markets, that documentation matters as much as the offer price itself. Get it sorted before you look at properties. You'll lose time if you don't.
The Inspection That Saves You Money
Skipping inspections to win a bid is a short-term win with long-term consequences. A proper inspection costs between $400 and $800 for a single-family home and maybe $1,200 for a small multi-unit. I spent $650 on a scope once that found a failing slab foundation with visible cracking and drainage issues that weren't apparent at first glance. The seller agreed to drop the price by $14,000. The inspection paid for itself 20 times over. Here's the thing most people miss: the standard home inspector is looking for obvious problems. They're not structural engineers, they're not pest specialists, and they certainly aren't roof certifiers. You need to know when to call in a specialist. Settling cracks in a 1970s build in the Southeast are almost always cosmetic. Hairline cracks in a poured concrete basement wall in the Midwest might mean nothing. But diagonal cracks running from a door frame to the corner of a window? That's worth a structural opinion before you sign anything. One deal in Raleigh fell apart because the foundation work done five years earlier was never permitted and the engineer found it was pushing the house out of plumb. Cost to fix: $31,000. The seller would have covered half if we'd asked sooner.
Get the Full Details
When the Numbers Lie
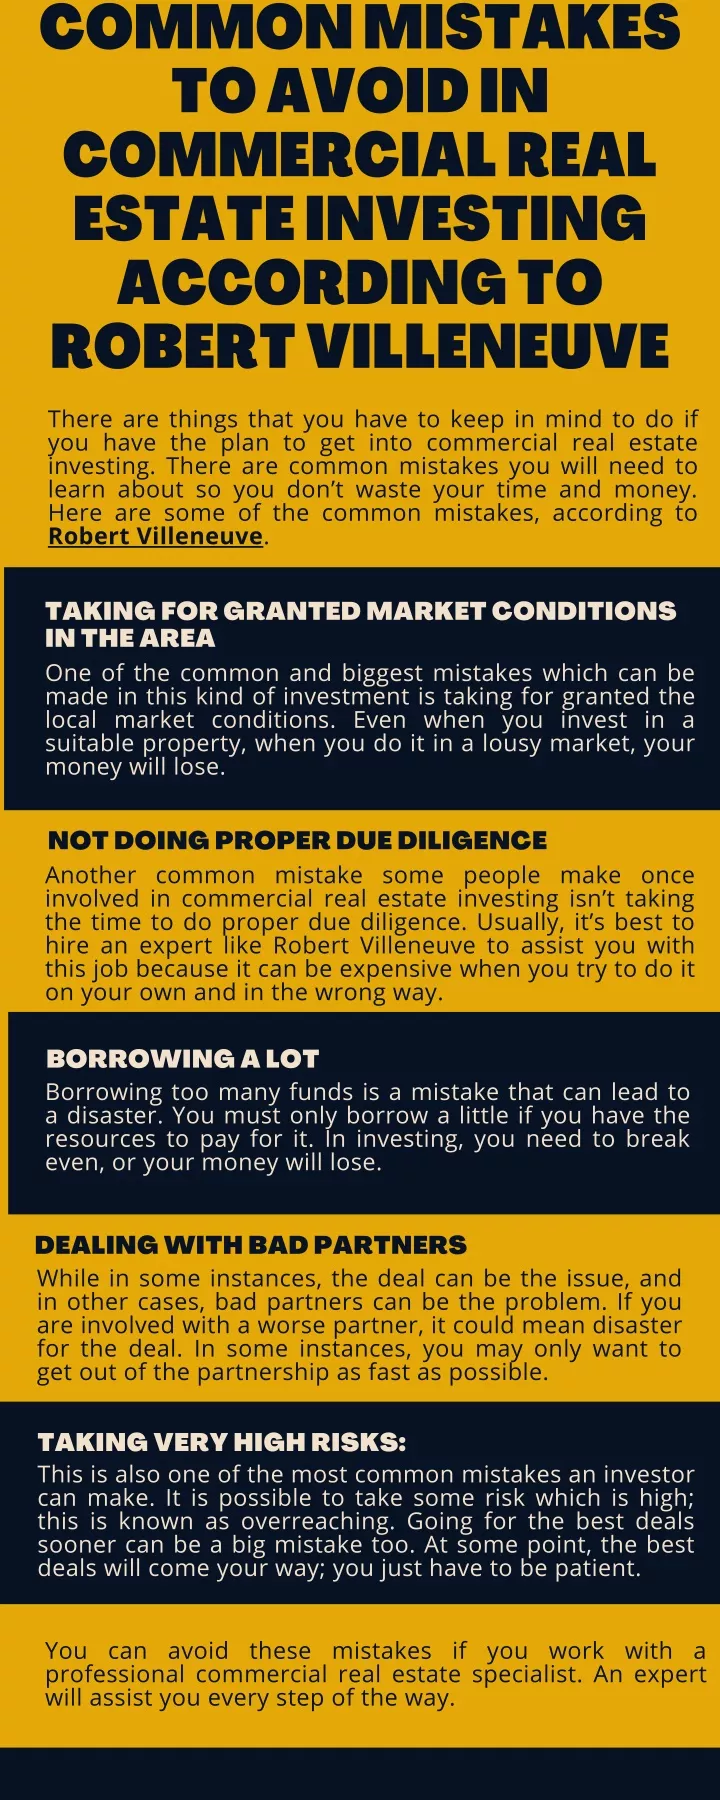
Cap rates are useful as a quick comparison tool but they hide a lot. Two properties can have the same cap rate and wildly different risk profiles. One might be in a stable neighborhood with long-term tenants and a fully functional roof. The other could be in a transitioning area with month-to-month leases and a water heater that's nine years old. The cap rate doesn't tell you which one will actually perform. Run your own sensitivity analysis. Take your pro forma and plug in worst-case scenarios: what if vacancy runs at 12 percent instead of 8 percent? What if the major system fails in year two instead of year four? What if property taxes increase by 15 percent? If the deal still works under those conditions, you've got a solid foundation. If it falls apart, you know exactly where the pressure points are and can negotiate accordingly or walk away. The other thing people overlook is the cost of capital. When rates are high, leverage that looked smart two years ago looks expensive now. A property that cash flowed $400 a month with a 4 percent rate might now cash flow negative at 7 percent. That doesn't mean the property is bad. It means your underwriting needs to reflect current borrowing costs, not the rate you saw when you started looking.
Exit Strategy Matters From Day One
Most buyers figure out how to buy. Fewer think about how to sell or refinance. If you're planning to hold, make sure the property can refinance at current rates and still show positive cash flow. If you're flipping, know your hold cost per day including carrying costs, insurance, utilities, and opportunity cost on your capital. A deal that looks profitable on paper can become a money loser if it sits for eight months instead of four. I once evaluated a fix-and-flip where the ARV looked strong based on recent sales. The problem was the neighborhood was shifting. Those comparable sales were 18 months old, and the area had seen a spike in vacant properties. By the time I finished the rehab and listed it, the comps had dropped and the days on market ran 62 days instead of the projected 30. The margin evaporated. Always check how long similar properties are actually sitting, not just what they sold for. The underlying principle here is that real estate rewards discipline and punishes assumptions. Write down every number you use and flag what you're guessing at. Go back and verify those guesses. The market will reward you for being thorough and punish you for being comfortable.