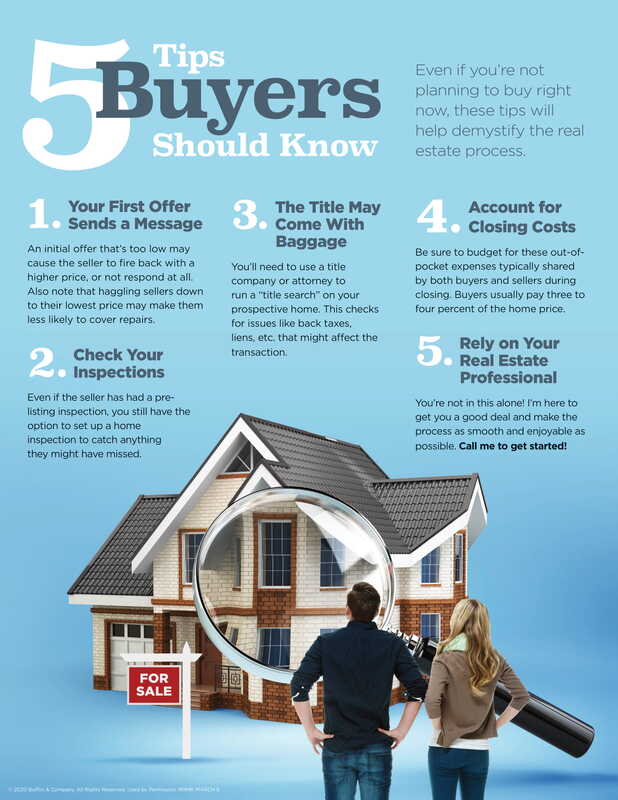
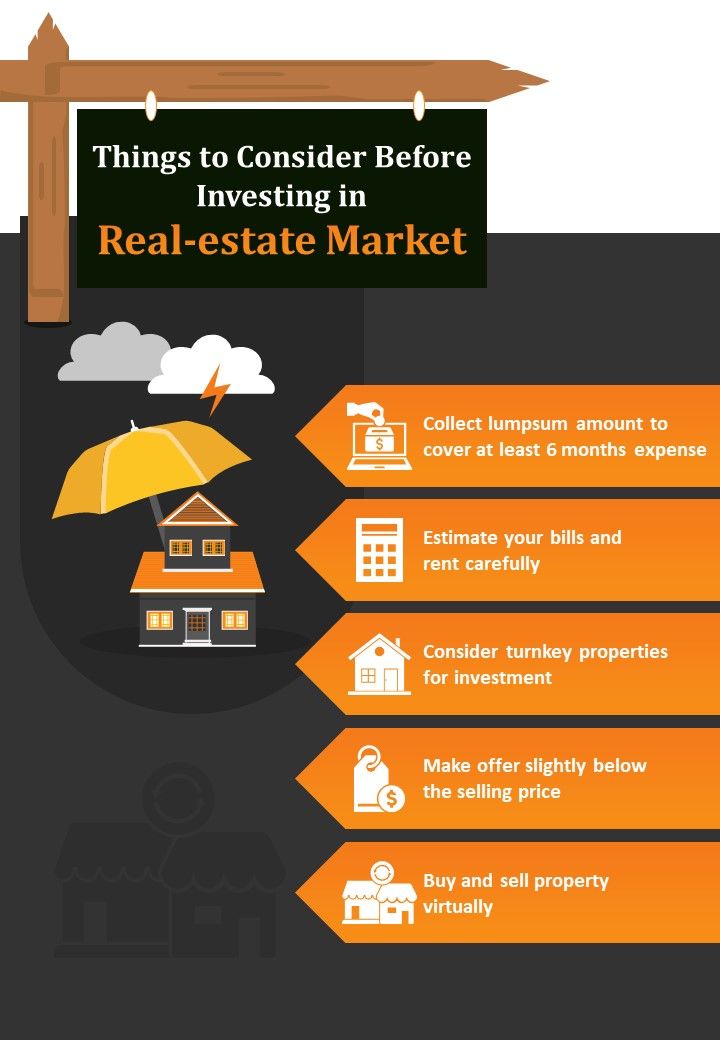
What nobody tells you about getting started in real estate
The first mistake most people make is thinking they need a big down payment and perfect credit before they even look at a property. That is not how this works. I learned that the hard way back in 2014 when I almost walked away from a duplex deal because my credit score was 642. The lender who ended up funding it didn't care about the score as long as the numbers on the deal made sense. You need to understand what those numbers are before you ever talk to a bank. Here is the thing about real estate that every beginner article skips over. The trick is not finding the perfect property. The trick is knowing which numbers you are allowed to get wrong and which ones will destroy you if they are off by even a fraction. I have seen people blow up deals because they underestimated repair costs by eight percent. They forgot to line item things like HVAC replacement, foundation drainage work, and the permits required just to do the work. That eight percent adds up to roughly twelve thousand dollars on a mid-range fixer. The standard rule most people learn first is the one percent rule. Monthly rent should equal one percent of the purchase price plus closing costs. It sounds clean on paper. In practice, it fails in about sixty percent of markets because purchase prices have outpaced rent growth in so many places. I stopped using it as a primary filter five years ago and switched to the cap rate method for acquisition and the cash-on-cash return for financing decisions. Those two numbers tell you different things. The cap rate tells you whether the property earns its keep without debt. Cash-on-cash tells you what your actual money is producing after the loan payments come out. You need both.
The inspection that saved me from a bad deal
There is a specific scenario I want to walk through because it is the kind of edge case that does not get covered in the usual guides. A few years ago I was looking at a triplex in Columbus. The seller disclosed nothing about the roof. The numbers were solid. The cap rate was sitting at about nine percent, which is well above the local average. Everything looked fine on the surface. I brought in a roof inspector as part of my contingency and he found three separate areas of active granule loss and soft spots around the vent piping that indicated moisture intrusion inside the decking. The roof was maybe six years old but had been installed over two previous layers, which is against code in most municipalities and meant a full tear-off would be required. The quote came in at twenty-two thousand dollars. That changed the entire arithmetic. I renegotiated the price down by eighteen thousand and kept the deal. What most people miss in a situation like this is that the age of the roof matters less than the number of layers underneath it. A fifteen-year-old roof on a single layer is a better investment than a five-year-old roof installed over two old layers. When you are evaluating a multi-family property, always ask about the number of shingle layers before you order the inspection. It saves you from walking into that exact surprise.
How to actually underwrite a deal in thirty minutes
You do not need expensive software to underwrite a rental property. You need a spreadsheet and a habit of being stubborn about your assumptions. I built my own underwriting model around eight years ago and I have not looked at a commercial product since. The core of it is simple. You input the purchase price, closing costs, rehab budget, expected rent, vacancy rate, property tax, insurance, and maintenance reserve. From there it calculates the net operating income, the cap rate, the debt service based on your assumed interest rate and down payment, and the cash flow after everything. The magic happens when you run sensitivity tables on two variables at once, usually rent and vacancy, because those are the two things that move the most. Most beginners make the mistake of using optimistic numbers for everything. Put in six percent vacancy instead of four. Assume your repairs will run ten percent higher than the contractor quote. Make sure your property management fee is listed even if you plan to self-manage, because at some point you will need professional help and you want the deal to survive that transition. If the numbers work at conservative inputs, they will work at normal inputs. If they only work at optimistic inputs, the deal is a trap.
Get the Full Details

Financing options beyond the conventional loan
The conventional thirty-year fixed is the default for a reason, but it is not always the best tool. For a single-family fix-and-flip where you plan to hold for twelve to eighteen months, a hard money loan makes more sense despite the higher rate. The interest rates run between nine and twelve percent, but you are only carrying the debt for a short window and the approval timeline is measured in days, not weeks. For a rental property you intend to hold long term, a house hack with an FHA loan is still one of the most underutilized strategies I have seen. You put three and a half percent down, live in one unit, and rent out the rest. The rental income can offset your mortgage payment significantly. There is a catch with the FHA house hack that most people ignore. You are required to occupy the property as your primary residence for at least one year. If you try to skip out early, you are technically in violation of the loan terms and could face acceleration of the full balance. I knew someone who bought a fourplex with an FHA loan, rented out all four units from day one, and never lived there. The lender pulled a credit report on the property address, saw no utility accounts in his name, and flagged it. He ended up refinancing into a conventional loan at a higher rate and paying points to clear the mess. It was avoidable.
When to walk away from a deal
I wish I had a clearer rule for this, but the reality is more like a set of thresholds you check before every offer. If the cap rate is below four percent in a market where the average sits at six, walk away. If the repair estimate from your contractor exceeds your budget by more than fifteen percent after the initial walkthrough, either renegotiate or leave. If the seller is refusing to provide a property condition disclosure and the area has known environmental issues like radon or outdated lead piping, walk away. There is no compelling deal that justifies ignoring those signals. The hardest deals to walk away from are the ones where you have already spent money and time. I once spent about four thousand dollars on inspections, appraisals, and title work on a commercial property in Nashville before the environmental Phase One report came back with soil contamination from a former gas station on the lot. Walking away cost me that four thousand dollars and three months of work. Staying would have cost me roughly three hundred thousand dollars in remediation. I kept the loss small and moved on. That is the calculation you have to make repeatedly.
The paperwork most people skip until it costs them
Lease agreements, tenant screening protocols, and proper escrow handling for security deposits are not optional. I had a landlord client in Atlanta who used a free template from the internet for his tenant leases. He did not include a clause about late fees that complied with Georgia state law, so when tenants started being thirty days late, he could not enforce the penalty. He lost about two months of rent across three units before he hired a property management company to rewrite everything. The rewrite cost him four hundred dollars and fixed the problem permanently. Security deposit escrow is another area where people get burned. In several states you are legally required to hold tenant deposits in a separate interest-bearing account. Mixing them with your operating account is a violation in places like Massachusetts, New York, and California. The penalties can range from returning double the deposit to losing your right to charge security deposits altogether on future units. If you are managing more than two properties, set up a dedicated business checking account and an escrow sub-account before you collect your first deposit. It takes about twenty minutes to set up and it prevents a class action lawsuit from a tenant who notices the commingling.

A note on market timing and patience
Everyone wants to know when the market is about to turn. The honest answer is that no one outside of people with institutional data access actually knows. What I can tell you from watching cycles over the past decade is that the markets that punish impatient investors are the ones where everyone is chasing the same trend. When you see real estate commentary everywhere talking about a specific city or asset class, the easy money has already been made. The opportunities are in the places people are ignoring because the story is boring. I bought my second rental property in 2019 in a midwestern city that had zero media coverage. The population was flat, the job market was stable but unglamorous, and the cap rates were running between seven and eight percent because nobody was paying attention. I held it through the pandemic, through the rate hikes, and through the market cooling of 2023. It has never been a exciting story. It has also never missed a payment. That is the point of a survival guide. You are not trying to win big. You are trying to stay in the game long enough for compounding to do the heavy lifting.