
What You Actually Need To Know Before The Exam
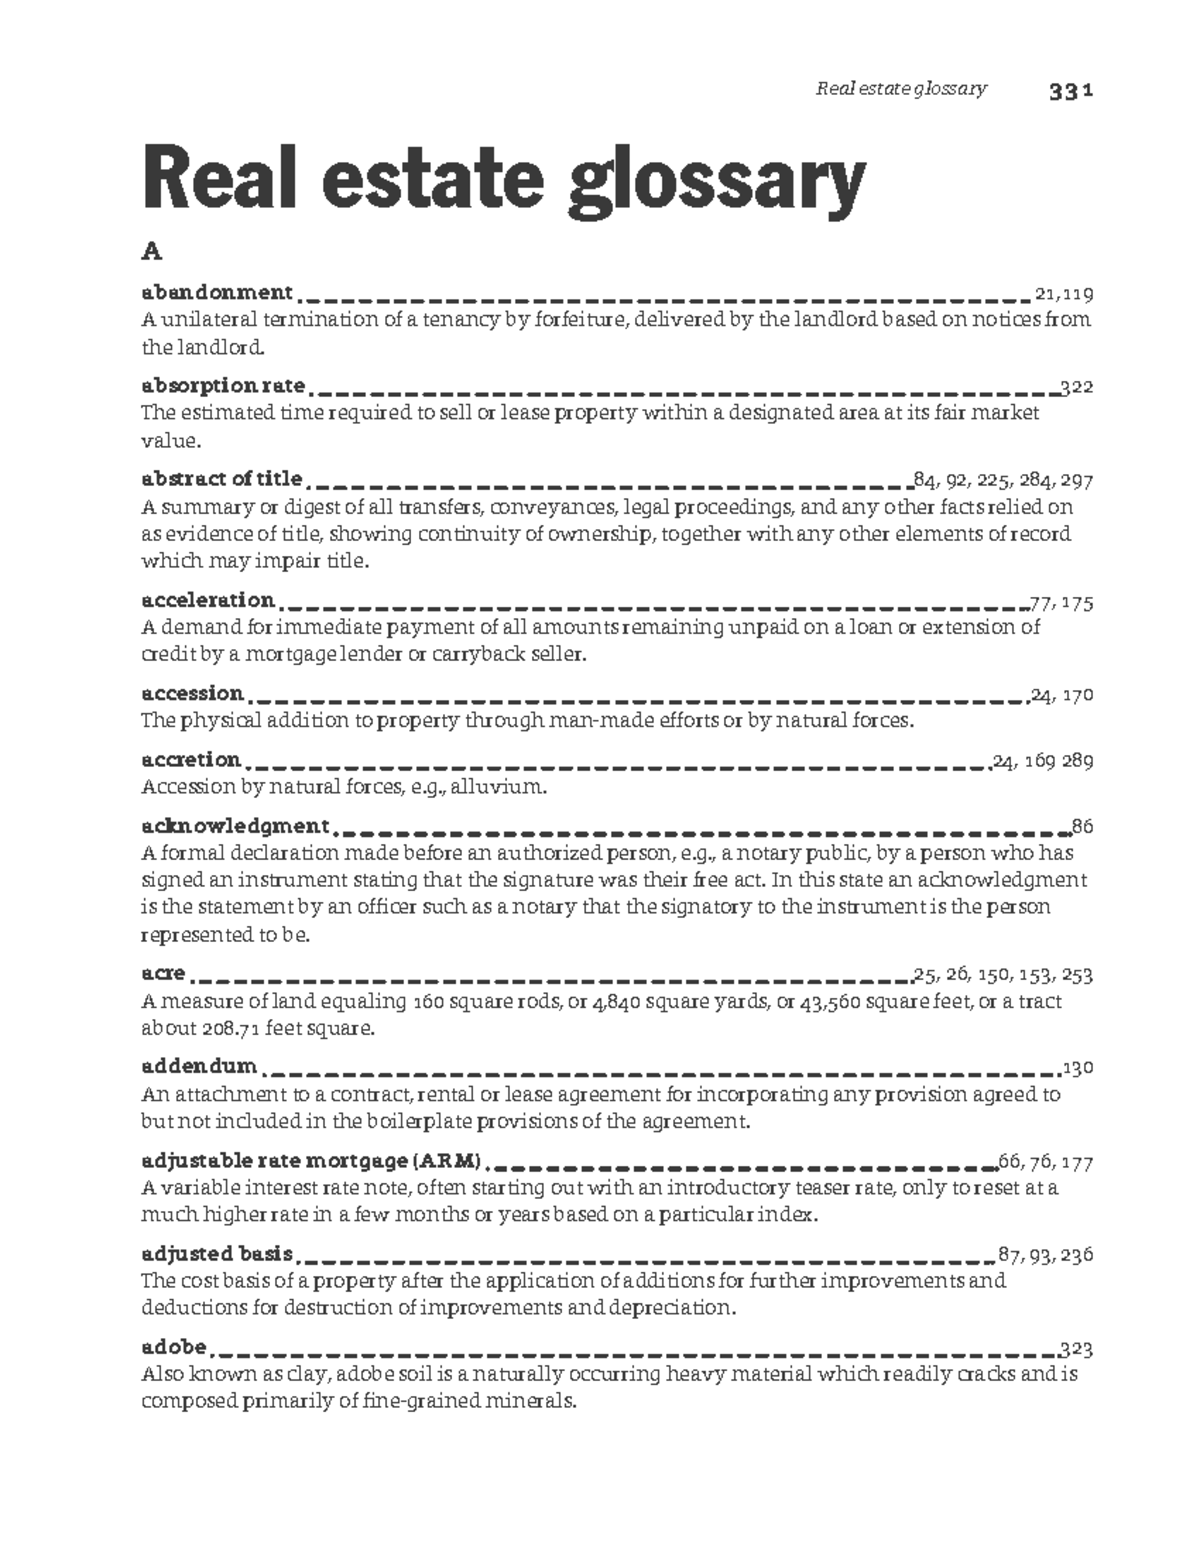
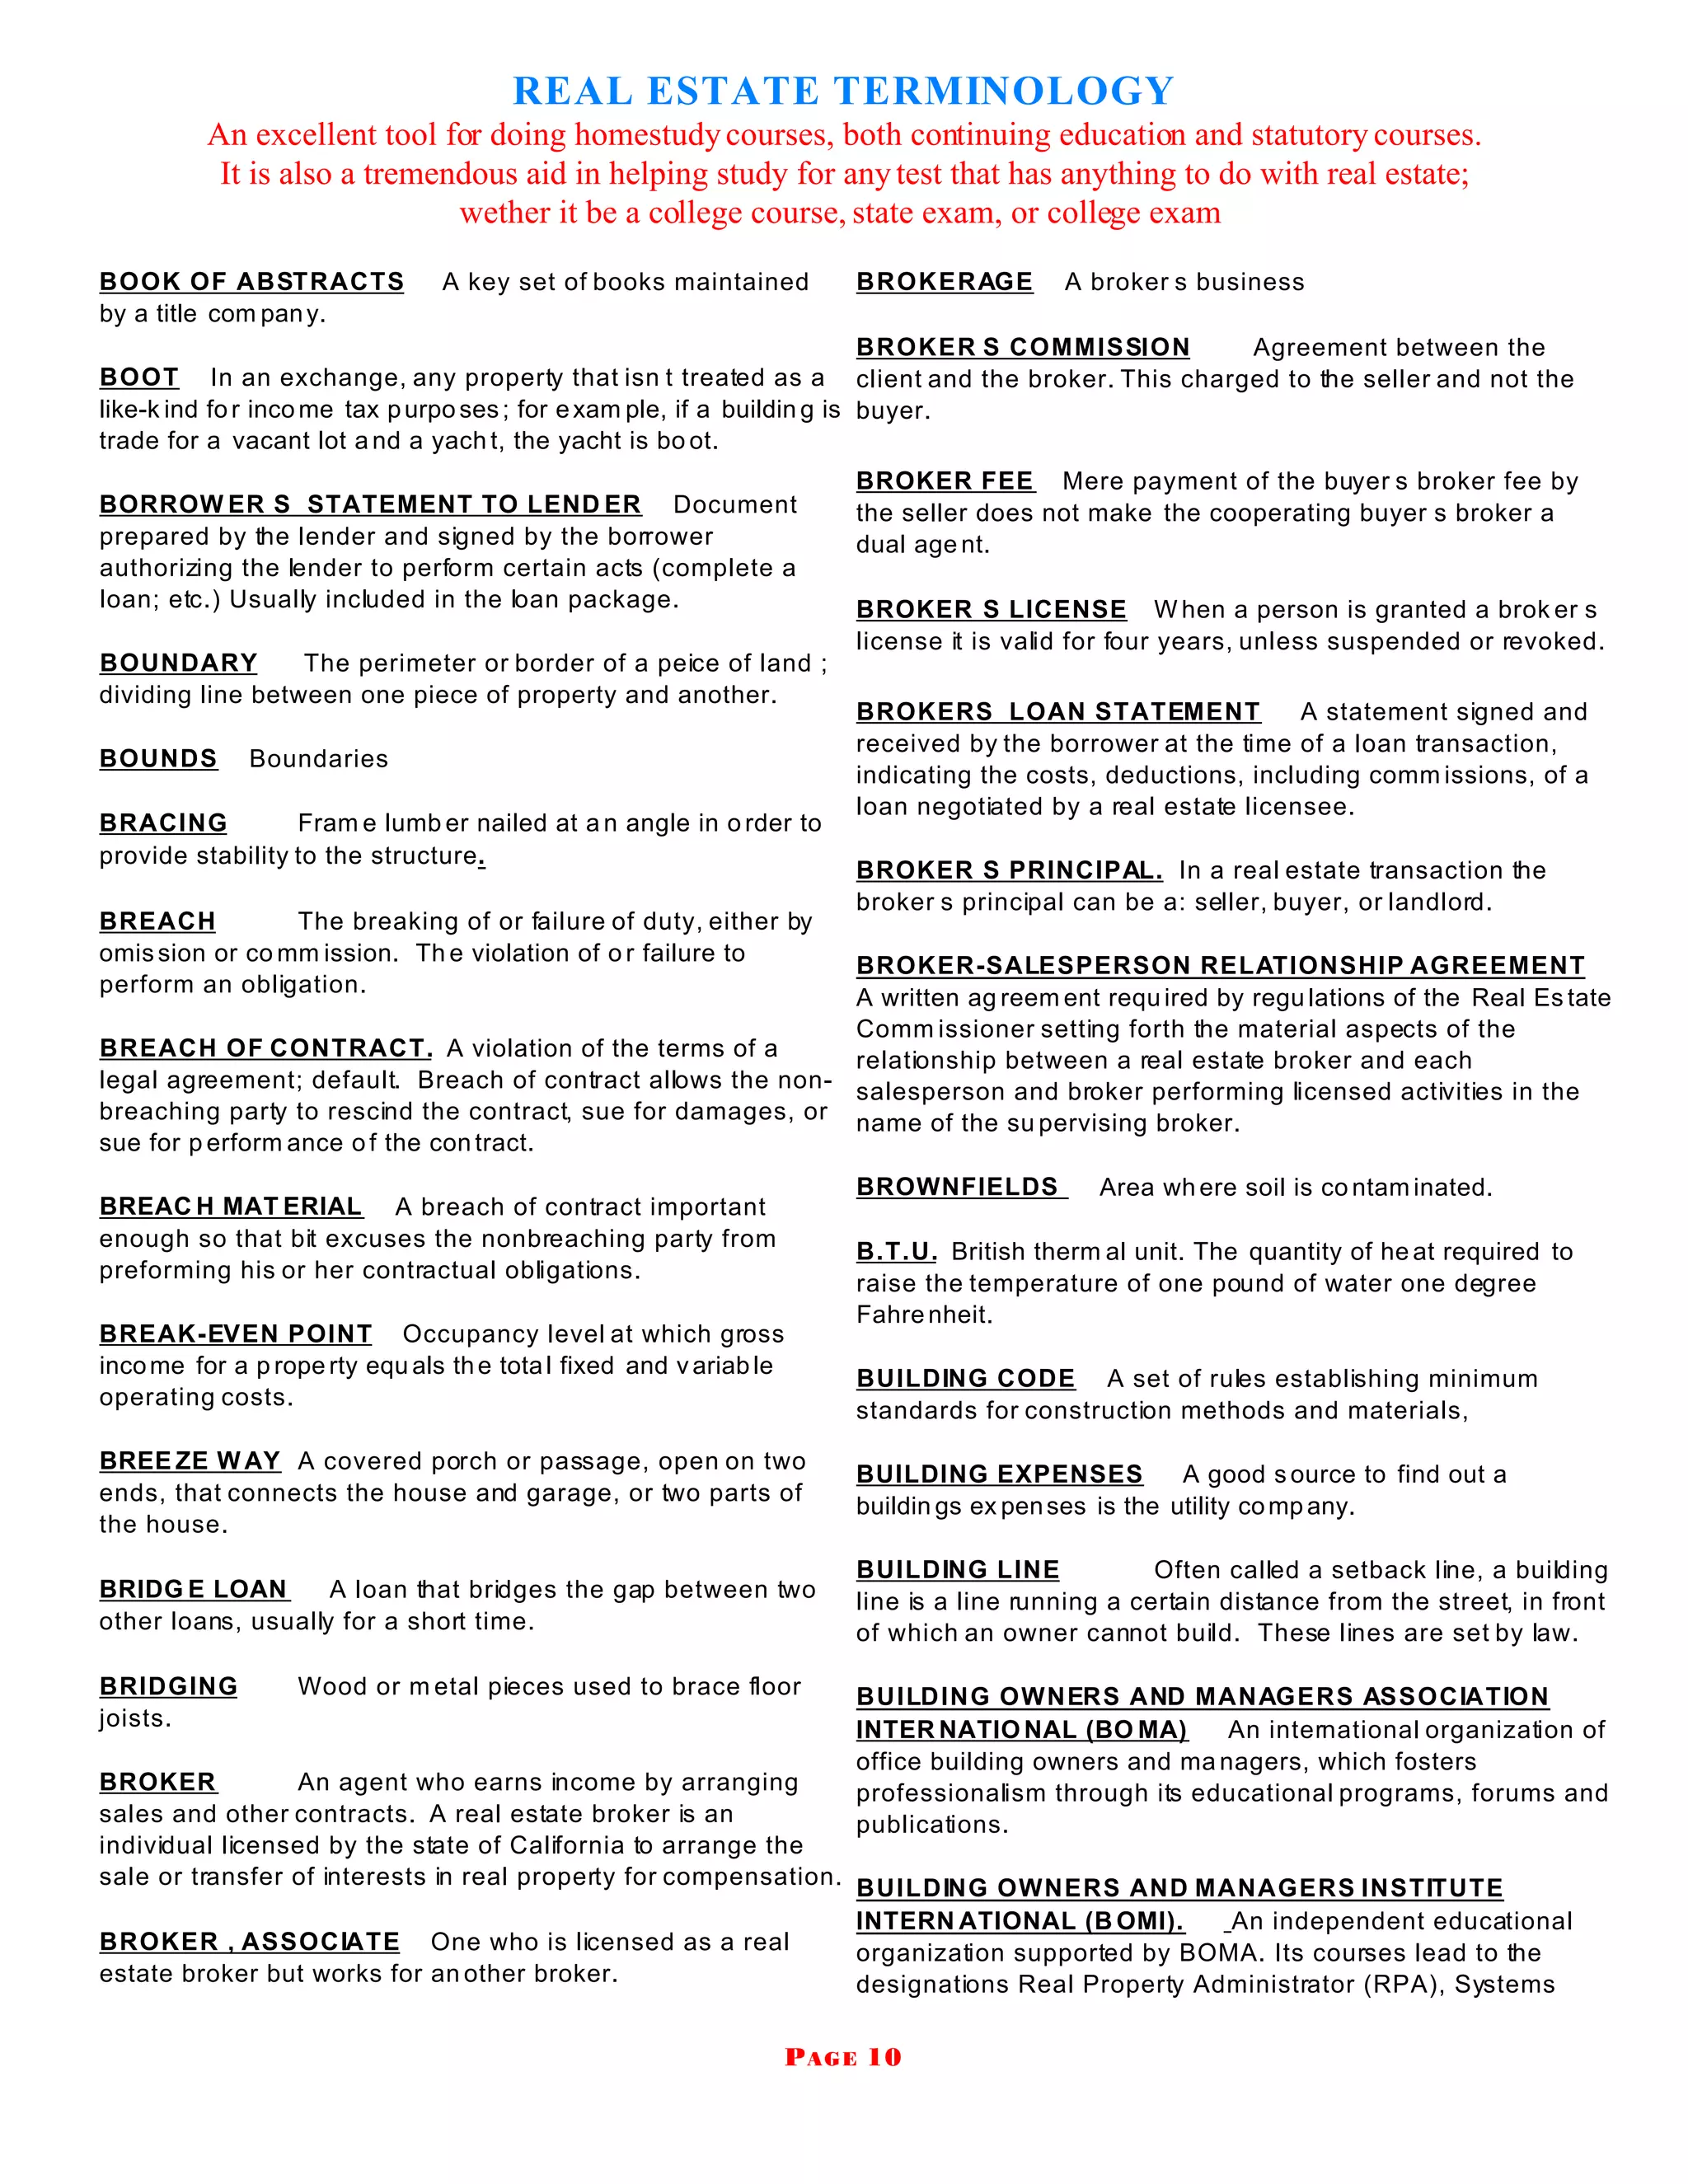
Most people prep for the real estate exam the wrong way. They memorize flashcards until they can recite definitions like robots, then walk into the testing center and realize every question is wrapped in a story you've never seen. The terms matter less than understanding how they behave in actual transactions. I've watched people fail because they knew what "escrow" meant but couldn't spot when an exam question was describing escrow without using the word. Let me break down the core terms and definitions you'll need for your Real Estate Terms And Definitions For Exam, but I'll explain them the way they actually show up on test questions. There's a difference between knowing a definition and being able to recognize it in context.
Proration and Closing Cost Allocation
This is where most people lose points, not because the math is hard, but because they don't understand who pays what and when. Proration splits expenses between buyer and seller based on the closing date. Property taxes, HOA fees, rent collected in advance — these all get divided. The key detail everyone forgets: the seller pays through the day of closing, and the buyer pays starting the next day. If closing is June 15th, the seller owes 15 days of expenses and the buyer takes the remaining 15 in a 30-day month. Simple enough until the question tries to trick you by switching to a leap year or asking about interest calculations on assumption loans. I once worked with a student who could do proration in her sleep. She took a practice test and got two proration questions wrong. Both were worded so that the closing date was stated indirectly — one said "closing occurs on the day after the fifteenth" and the other gave a rent-above-closing-date scenario that required figuring out which party held the escrow account. She had memorized the formula but hadn't trained herself to parse the language around it. That gap between formula and application is exactly what separates passing from failing.
Key Terms That Show Up On Every Exam
Easements
You need to know the four types cold: appurtenant, in gross, prescriptive, and easement by necessity. Appurtenant runs with the land and benefits two parcels — a dominant estate and a servient estate. In gross benefits a person or entity rather than a parcel, like a utility company's right to run power lines through your property. Prescriptive easements come from open, continuous, adverse use over a statutory period — basically adverse possession but for access rather than ownership. Easement by necessity applies when a parcel is landlocked and the law implies a right of way must exist for the property to be usable. The exam trap here is mixing up appurtenant and in gross. They'll describe a scenario where a homeowner has a right to use a neighbor's driveway and ask what type of easement this is. If both properties benefit, it's appurtenant. If only one party benefits personally, it's in gross. The distinction matters because appurtenant easements transfer automatically when the dominant estate is sold, while in gross easements may or may not be assignable depending on the jurisdiction and the nature of the easement.
Get the Full Details

Agency Relationships
This section alone accounts for a significant chunk of the exam. You need to understand the difference between disclosed dual agency, designated agency, and subagency. Disclosed dual agency means one agent represents both buyer and seller in the same transaction — and it's illegal in several states. Designated agency assigns two agents from the same brokerage to represent each party separately. Subagency means a listing agent's cooperation with a buyer's agent creates an agency relationship between the buyer's agent and the seller, which is an outdated concept that some exams still test on despite most states having abolished it. The fiduciary duties are universal: loyalty, obedience, disclosure, confidentiality, accounting, and reasonable care. But the exam will test whether you know which duty applies to which situation. Here's something most review courses don't emphasize enough: confidentiality and disclosure can conflict. If a seller tells their agent the property has a foundation crack, the agent must disclose that to the buyer (disclosure duty) but cannot tell the buyer that the seller privately confessed the crack existed before any inspection (confidentiality duty). The information itself must be disclosed, but the fact that the seller shared it confidentially does not have to be revealed. That distinction trips people up constantly.
Deeds and Title
General warranty deed, special warranty deed, quitclaim deed — you need to know the differences in protection level. General warranty provides the broadest protection with six covenants. Special warranty only covers the time the grantor owned the property. Quitclaim provides zero warranties and simply transfers whatever interest the grantor may have. The exam loves to describe a scenario and ask what type of deed was used based on the language in the deed or the level of protection offered. A counter-intuitive point: a quitclaim deed can still be recorded and effective. People assume quitclaim deeds are worthless. They're not — they're commonly used between family members, during divorces, or to clear title defects. The grantor isn't promising anything, but if they do own the property, the transfer is valid. The risk is entirely on the grantee.
Finance and Loan Calculations
The math section is manageable if you understand the relationships between the variables. Points, loan-to-value ratios, debt-to-income ratios, and monthly payment calculations are fair game. One thing I wish someone had told me clearly: the exam does not expect you to calculate a full amortization schedule. You need to know how to compute monthly payments using the standard formula, calculate total interest paid over the loan term, and determine how much principal remains after a certain number of payments. Memorize the payment factor table if your exam provides one, or practice the formula until it's automatic. Here's the nuance most study guides skip: interest is always calculated on the outstanding principal balance, not the original loan amount. When questions ask about payoff amounts or early payoff scenarios, you need to understand that prepaid interest accrues daily from the closing date to the end of the month, and the first payment is often partly interest and partly principal. The amortization doesn't truly begin until after that first payment is applied.
Property Valuation Methods
Three approaches to value: sales comparison, cost, and income capitalization. Sales comparison applies to residential properties where recent comparable sales exist. Cost approach is used for new construction or unique properties where comparables are scarce — you take the land value plus replacement cost minus depreciation. Income approach applies to investment properties and commercial real estate, using net operating income divided by a capitalization rate. The formula for the income approach is straightforward — value equals NOI divided by cap rate — but the exam tests whether you can identify which approach to use in a given scenario. A single-family home? Sales comparison. A specialized industrial building with no comparable sales? Cost approach. A multi-unit apartment complex with steady rental income? Income approach. The question will describe the property type and market conditions, and you have to pick the right method. This seems simple but people second-guess themselves because they confuse the methods or miss a detail in the description.
A Problem I Saw Too Many Times
During my time reviewing exam prep materials and coaching candidates, the most consistent failure pattern involved contract law. Specifically, the distinction between a listing agreement and a purchase agreement, and who the parties to each contract are. Students would read a question about a seller breaching a contract and assume it was about the purchase agreement, when the question was actually describing a breach of the listing agreement. The terminology overlap between "broker," "agent," "seller," and "principal" creates genuine confusion under test pressure. My workaround was simple but effective: for every practice question, I had my students underline every party mentioned and label them immediately. Is this person the principal? The agent? The third party? Who signed which document? Once you map the relationships on paper, the answer usually becomes obvious even if the question is deliberately confusing. This took about thirty seconds per question but prevented countless errors from misreading.
What the Exams Actually Test vs. What You Think They Test
Here's an uncomfortable truth: most exam questions are reading comprehension tests disguised as knowledge questions. The terminology is the vehicle, but what they're really measuring is whether you can follow a complex scenario and apply the right rule. A typical question might describe a twenty-line fact pattern involving multiple parties, a dispute, and several legal concepts, then ask a narrow question at the end. The correct answer is usually the one that is most precisely correct, not the one that sounds impressive or covers the broadest principle. Two answers will often both be partially right. Pick the one that is completely right. This is the single most important test-taking strategy for the real estate exam, and it's something almost no study guide mentions because it feels too vague to teach. But it's accurate. When you see two answers that seem correct, eliminate the one that makes an assumption not stated in the question, or the one that states a general principle when a more specific rule applies to the facts presented.

Leases and Landlord-Tenant Law
Residential tenancies, commercial tenancies, leasehold estates, and security deposit regulations vary significantly by state, but there are federal and common-law principles that appear on nearly every exam. Tenancy at will, tenancy for years, periodic tenancy, and tenancy at sufferance — know the differences and the termination procedures for each. A periodic tenancy automatically renews until proper notice is given. A tenancy at will has no fixed duration and can be terminated by either party at any time. A tenancy at sufferance occurs when a tenant holds over after the lease expires without the landlord's consent. The security deposit section is another area where exams drill into specifics. Most states cap security deposits at one to two months' rent, require them to be held in a separate account, and mandate interest payments to tenants in certain jurisdictions. The exam won't ask you to memorize every state's statute, but it will test whether you know the general obligations of a landlord regarding security deposits and whether a tenant can withhold rent or break a lease due to constructive eviction from unaddressed habitability issues.
Taxes and Assessments
Ad valorem taxes are based on assessed value, not market value, though some jurisdictions use market value as the assessment base. The millage rate determines the tax owed per thousand dollars of assessed value. If you see a question with a property assessed at $180,000 and a tax rate of 45 mills, the calculation is straightforward: $180,000 times 0.045 equals $8,100 in annual taxes. But the question might ask for the monthly portion, or the seller's share if closing happens mid-year, or the tax impact of a reassessment. Read the full question before calculating. Special assessments are different from ad valorem taxes. They fund specific improvements like sidewalks, sewer lines, or street lighting that benefit particular properties. The key distinction: special assessments are voluntary in the sense that they attach to properties within a defined improvement district, and they can be forced through upon a majority vote of property owners in that district. Non-compliance can result in a lien against the property. This comes up on exams because candidates confuse special assessments with general property taxes.
Zoning and Land Use Controls
Zoning ordinances, variances, nonconforming uses, and conditional use permits form the backbone of land use regulation questions. A variance grants relief from strict zoning requirements when hardship can be demonstrated. A special use permit allows a use that is conditionally permitted within a zoning district. A nonconforming use is a legal inconsistency that existed before the zoning change and is allowed to continue under grandfather provisions. The examination commonly tests whether you understand that nonconforming uses are not illegal but carry restrictions on expansion or modification. Eminent domain and inverse condemnation are constitutional law topics that appear regularly. Eminent domain is the government's right to take private property for public use with just compensation. Inverse condemnation is when a property owner sues the government claiming a taking has occurred without formal proceedings. The Fifth Amendment's takings clause is the source of both concepts. Exams frequently test the difference between a regulatory taking (where government regulation effectively destroys property value) and a physical taking (where the government directly appropriates property).

Fair Housing and Civil Rights Law
The Fair Housing Act protects seven classes: race, color, religion, sex, national origin, familial status, and disability. The Housing for Older Persons Act provides exceptions for housing designed for older persons. State and local laws may add additional protected classes such as sexual orientation, gender identity, source of income, and marital status. The exam will test both federal minimums and your ability to recognize when a practice violates the law. A frequently tested scenario involves the "Mrs. Murphy" exemption, which allows owner-occupied buildings with four or fewer units to potentially discriminate, though this exemption does not apply to advertising or to discrimination based on race. Another common trap: steering. Directing prospective buyers toward or away from certain neighborhoods based on protected characteristics is illegal regardless of intent. Even well-meaning recommendations about "the best schools" or "safer neighborhoods" can violate fair housing law if they correlate with protected classes. The exam expects you to know that intent is irrelevant — the effect is what matters.
Disclosure Requirements
Seller disclosure obligations vary by state, but nearly every jurisdiction requires disclosure of known material defects. Lead-based paint disclosure is federal and applies to all residential properties built before 1978. Natural hazard zone disclosures, mortality statement requirements, and Megan's Law registry disclosures are common additions. The exam will test whether you understand that failure to disclose known defects can result in rescission of the contract, damages, and disciplinary action against the license holder. Agent disclosure obligations are separate from seller obligations. Agents must disclose material facts they become aware of, even if the seller hasn't disclosed them. This creates an ethical tension in dual agency situations where the agent knows information about one party that could benefit the other. The duty to disclose generally overrides the duty of confidentiality in cases of latent material defects that affect value or habitability, though the specific legal requirements depend on state law.
A Practical Study Recommendation
Practice questions are more valuable than flashcards for exam preparation, but only if you use them correctly. Reading the answer and moving on gives you a false sense of competence. After each practice question, write down why the correct answer is right and why each wrong answer is wrong. This takes longer but builds the analytical habit the exam actually tests. Most candidates spend hundreds of hours reviewing content and only tens of hours doing practice questions. Flip that ratio. If you're looking for a comprehensive resource, the National Association of Realtors publishes study guides, and state-specific exam prep courses from companies like Real Estate Exam Scholar or PrepScholar tend to align closely with actual exam content. Some candidates also find value in the state association's own materials, which sometimes mirror the exact framing and difficulty level of the licensing exam.
Common Pitfalls That Cause Failure
The three most common reasons people fail the real estate exam are time pressure, misreading questions, and overthinking. Time pressure is real — the exam is longer and more dense than most people expect. If you're spending more than ninety seconds per question on the first pass, you're going to run out of time. Misreading is the second cause, and it's directly connected to the point I made earlier about mapping parties and relationships before answering. Overthinking is the third — selecting the second most correct answer instead of the most correct one because you're looking for a trick that isn't there. There's also a structural issue with many study programs: they teach you what things are rather than how to identify them in context. Knowing the definition of an escrow account is useful. Recognizing that a question about a neutral third party holding funds during a transaction is describing escrow — even though the word escrow never appears — is what actually helps you pass. Train yourself to translate the exam's language into the concepts you've studied, not the other way around.
State-Specific Variations
This is worth emphasizing because it's where many candidates get tripped up. The real estate exam is administered at the state level, and while the national portion covers general principles, the state-specific portion tests your knowledge of local law. Some states include additional topics like community property, water rights, or mineral rights that are irrelevant in most other states. Your study materials must be current and state-specific. An older edition of any prep book may contain outdated information, particularly around fair housing amendments and state licensing requirements that have changed in the last few years. If you're unsure whether your materials are current, check the state real estate commission website directly. They usually publish the exam content outline and sometimes even sample questions. This is more reliable than any commercial prep course for understanding exactly what will and won't be tested.
Final Thoughts on Preparation
The real estate exam is passable with disciplined preparation. It's not designed to be impossible, but it is designed to filter out people who haven't put in the work. The candidates who pass consistently are the ones who treat it like a professional competency test rather than a trivia challenge. They understand the concepts, they can apply them to unfamiliar scenarios, and they've practiced enough to recognize the patterns in the questions. Focus on application over memorization. Write out your own summaries of each topic in your own words. Teach the material to someone else. Take practice exams under timed conditions and review every mistake thoroughly. The gap between knowing and understanding is where exam failures happen, and bridging that gap is entirely within your control if you spend the time doing it right.
