The Real Estate Transaction Management Checklist
Real Estate Transaction Management Checklist
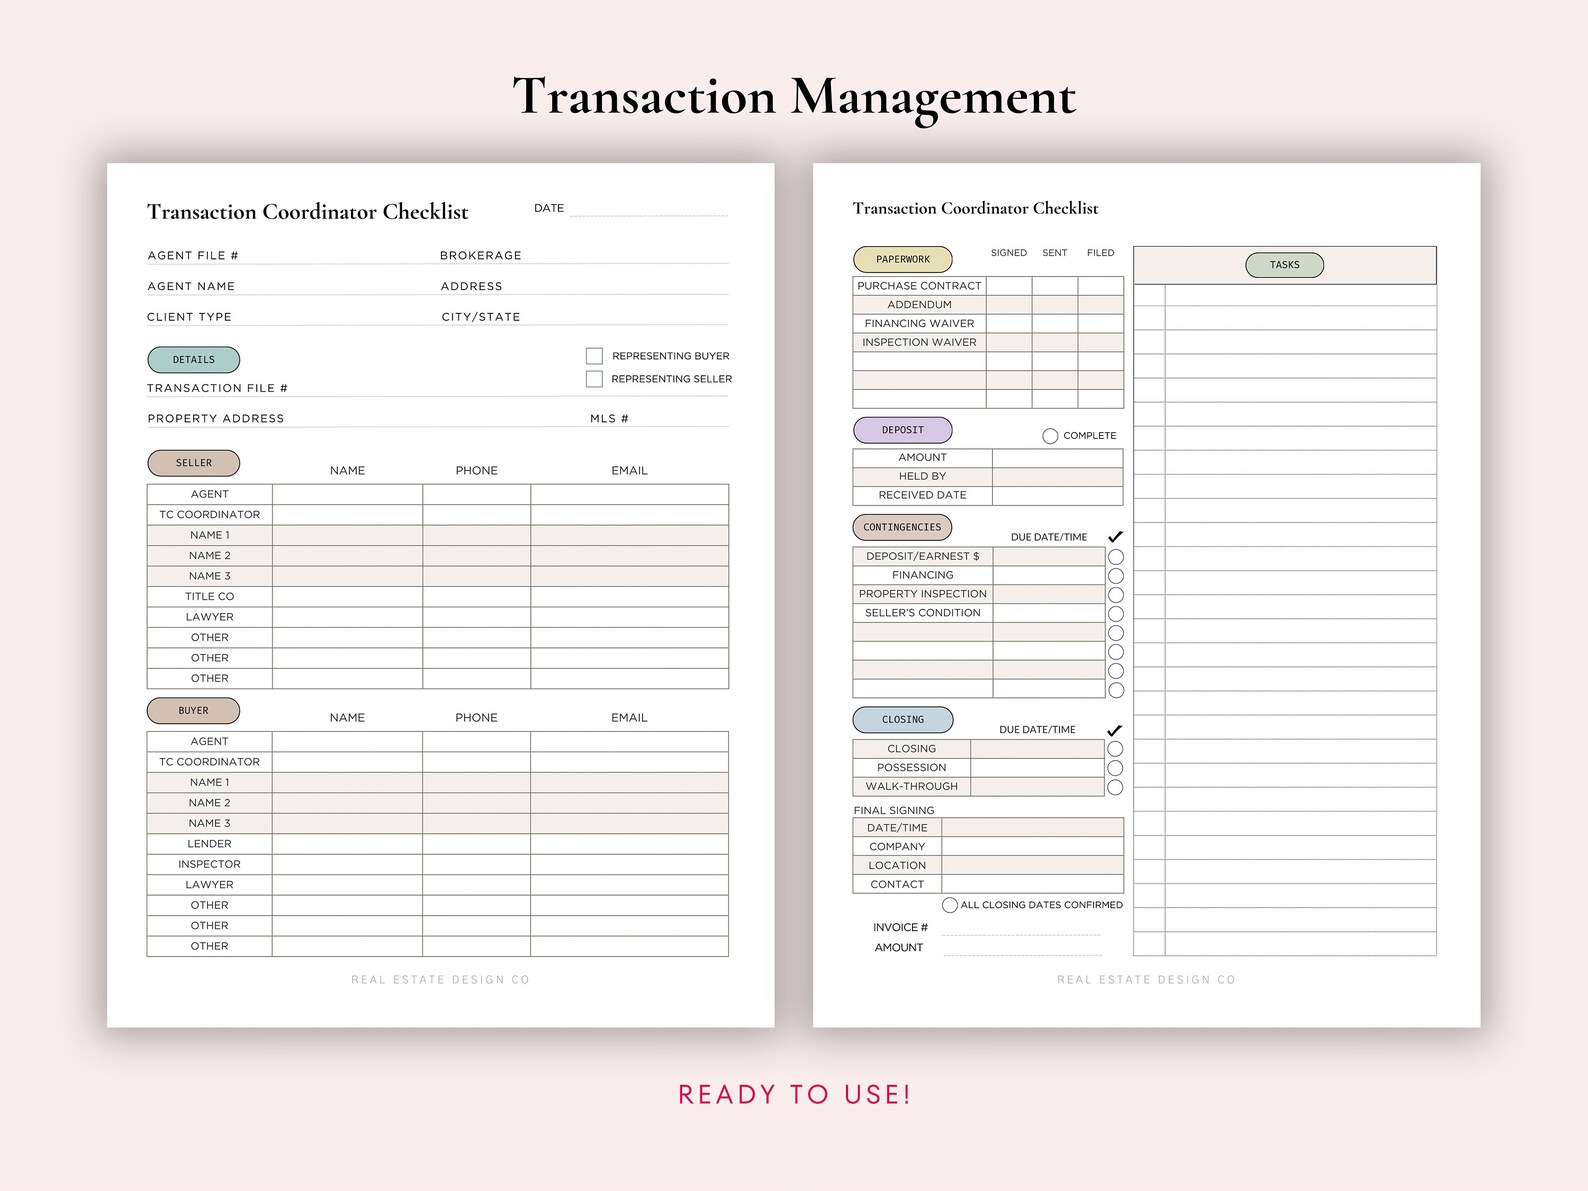
A transaction management checklist is a sequential document that tracks every deliverable, deadline, and sign-off between contract execution and recording. It is not the same thing as a standard closing timeline found in most buyer or seller guides. A closing timeline tells you when things happen. A transaction management checklist tells you who is responsible for each item and what proof you need to move it forward. I keep mine in a shared spreadsheet so both the listing agent and the buyer's agent can update status in real time, rather than emailing back and forth and pretending they are aligned. The most expensive mistakes I see don't come from missed inspections. They come from gaps between the contract signing and the actual delivery of documents. A buyer's agent will file the earnest money check on time but never follow up on whether the title company confirmed receipt. A listing agent will submit all disclosures by the statutory deadline but forget that one of the required addendums needs separate notarization in their county. I have personally spent two weekend mornings tracking down a missing HOA estoppel certificate because the checklist had "request from seller" checked off before anyone actually asked the association. The workaround I use now is adding a hard confirmation field to every item—proof of receipt, not just action taken. That single change eliminated about half the post-contract fires I was putting out.How to build a working checklist
Start with the contract itself. Every transaction is different, but most residential deals in the US share a core skeleton. Pull your state's standard purchase agreement form and work backward from the key dates: inspection deadline, appraisal contingency window, financing commitment date, and closing date. Every item on your list should tie directly to one of those dates or to a mandatory document. I organize mine into four phases with sub-deadlines inside each one. Phase one covers execution through intake. Phase two is due diligence. Phase three is loan processing and clearing conditions. Phase four is closing and post-closing documentation. Within each phase, I separate items into three buckets: seller responsibilities, buyer responsibilities, and agent responsibilities. That last bucket is where most people fail. Agent responsibilities include ordering the preliminary title report, confirming the escrow account is funded, scheduling the final walk-through, and submitting the closing package to the title company before their cutoff time. Here is what a complete checklist actually looks like in practice:Pre-Contract Phase
Verification of property information: Parcel number, legal description, zoning classification, confirmed square footage, and any recorded easements. I always pull the current deed and tax record before writing an offer so I am not surprised by a boundary dispute or an unpermitted addition later. Preliminary financial screening: Buyer pre-approval letter on the lender's letterhead, not just a pre-qualification. I had a deal fall apart at appraisal because the buyer's pre-approval was from a mortgage broker who did not verify income, and the underwriter rejected the loan three weeks into escrow. The checklist item now reads "pre-approval with complete documentation reviewed by underwriter," not just "pre-approval obtained." Engagement agreement execution: Brokerage representation agreement signed and dated by all parties before any substantive negotiations begin. This is a non-negotiable step that I used to treat as administrative and often scheduled second. Now it is the very first item because everything downstream depends on it for authority to act.
Disclosure and Due Diligence Phase
Seller disclosures: Property condition disclosure, lead-based paint (for homes built before 1978), Megan's Law notification, natural hazard zone disclosure if applicable, and any state-specific supplemental forms. In California this list alone is fourteen pages long. In Texas it is six. Do not assume you know the requirements from a previous transaction in another state. I once missed a radon disclosure requirement for a property near a uranium mining area because I was operating from a generic checklist built for suburban deals elsewhere in the same state. HOA and condominium documents: CC&R's, current bylaws, meeting minutes for the last two years, reserve study, estoppel certificate, and monthly dues breakdown. The estoppel certificate is the critical one. It is the only document the title company will accept as a final confirmation of what the seller owes the association. Everything else can be superseded by the estoppel. I require this within five business days of contract execution, not at closing, because association turnaround times vary wildly and some will not respond until the last week of escrow, which is when you cannot afford to wait. Inspection scheduling and completion: General home inspection, pest and WD, sewer scope, roof certification, foundation inspection where relevant, and radon testing if the contract requires it or if the area has known radon concerns. The standard mistake here is booking all inspections on the same day to save time. That creates a bottleneck where you cannot negotiate repairs until every report is in. I stagger them: pest and sewer first, general inspection second, specialized inspections third. The first two usually come back within forty-eight hours. The rest take longer but are less likely to kill the deal outright.
Loan and Title Phase
Application and documentation: Complete loan application submitted within forty-eight hours of contract acceptance. Required documents include W-2s for the last two years, twelve months of pay stubs, bank statements for the last sixty days, and gift letter if any portion of the down payment is a gift. I have seen buyers drag their feet on this because they assume the agent will handle it. The agent handles the transaction. The lender handles the loan. They are separate tracks that must move in parallel. Appraisal: Ordered by the lender but coordinated by the agent. Provide the appraiser with comparable sales that are actually comparable, not just nearby. I had a property appraise for twelve percent below contract price because the appraiser pulled three comps that were two miles away on a different school district boundary. My workaround is submitting a contemporaneous comparable sales analysis with the appraisal request, even though the lender is not required to consider it. It usually does not change the outcome, but when it does, it saves a week of renegotiation. Title search and commitment: Preliminary title report ordered within seventy-two hours of contract acceptance. Review for liens, judgments, unpaid taxes, and restrictive covenants. The standard review takes me about twenty minutes. If I see anything unusual, I spend an additional hour researching it. The most common hidden issue I find is an old mechanic's lien from a previous renovation that was never formally released. The seller thought it was resolved. The title company missed it. The buyer's lender caught it three days before closing and demanded a one-day extension. If you do not review the preliminary title report yourself, you are relying on someone else's attention to detail.
Get the Full Details
Survey requirements: Most transactions do not require a new survey unless the lender mandates it or there are visible boundary issues. I include a survey contingency item on the checklist regardless, with a note to remove it only in writing if the lender confirms it is not needed. This sounds paranoid. It prevented me from losing a deal on a property with a fence that encroached three feet onto the neighbor's lot. The survey came back clean, the inspector flagged the encroachment, and we had a ten-day window to get a boundary line agreement signed. Without that checklist item, I would not have noticed until after closing.
Closing and Post-Closing Phase
Closing disclosure review: The Closing Disclosure must be delivered to the buyer at least three business days before closing. I mark this on the checklist as a verification step, not just a scheduled event. You need to confirm the numbers match the Loan Estimate within the permitted tolerance levels. If they do not, you have a legitimate basis to delay closing rather than signing blindly. I saw a lender change the title insurance premium without notice on a refinance, pushing the closing costs beyond the buyer's cash-to-close amount. The buyer did not catch it until the three-day window was almost over. Had they reviewed the CD during the window, they would have had time to resolve it. Final walk-through: Scheduled no more than twenty-four hours before closing. Checklist items here are specific: confirmed repairs completed, all agreed-upon items removed from the property, utilities in working order, and no new damage. The standard mistake is doing the walk-through three or four days early. Conditions change. A roof leak can develop overnight. A seller can accidentally leave behind an included appliance or remove one they agreed to leave. Twenty-four hours is close enough that nothing new can develop and far enough that the buyer can still call the deal if something is wrong. Recording and possession transfer: The checklist must include a post-closing verification that the deed was actually recorded, not just signed. I have had sellers hand over keys on closing day, celebrate, and then discover three days later that the county recorder's office had a processing backlog and the transfer was not official until the following Friday. During that gap, the seller's homeowners insurance technically still covered the property, but the buyer's insurance did not. A single uninsured pipe burst in that window cost the buyer four thousand dollars out of pocket. The fix is straightforward: confirm recording via the county website before celebrating, and ensure the purchase agreement specifies exact possession transfer timing in writing.