Working with Real GDP Numbers in Practice
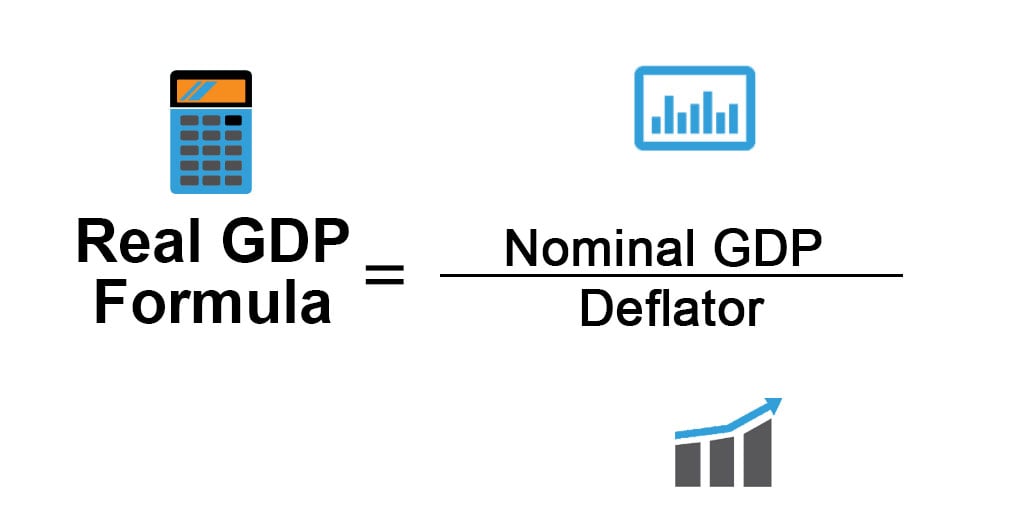
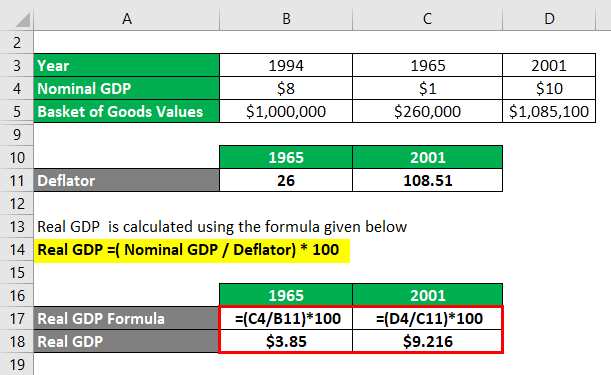
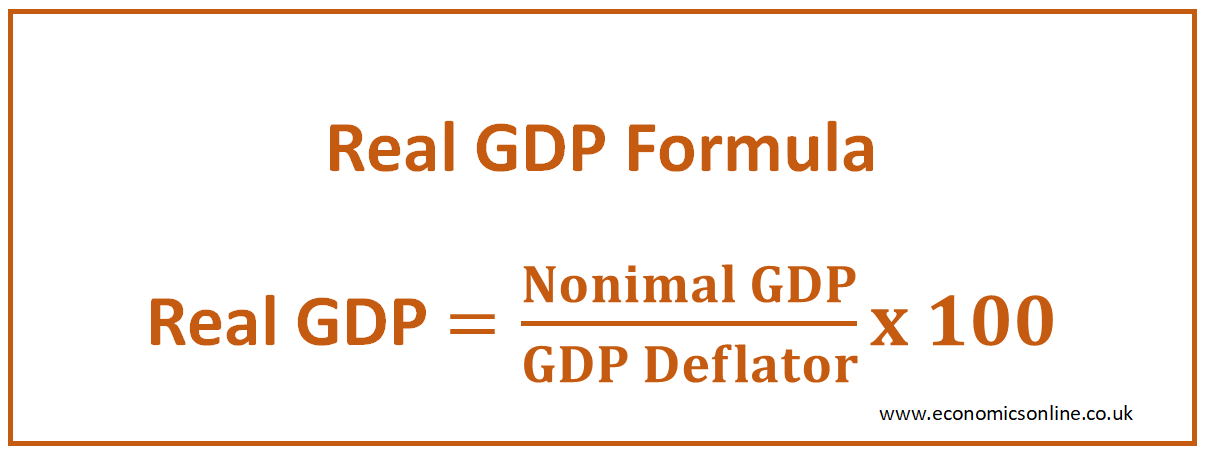
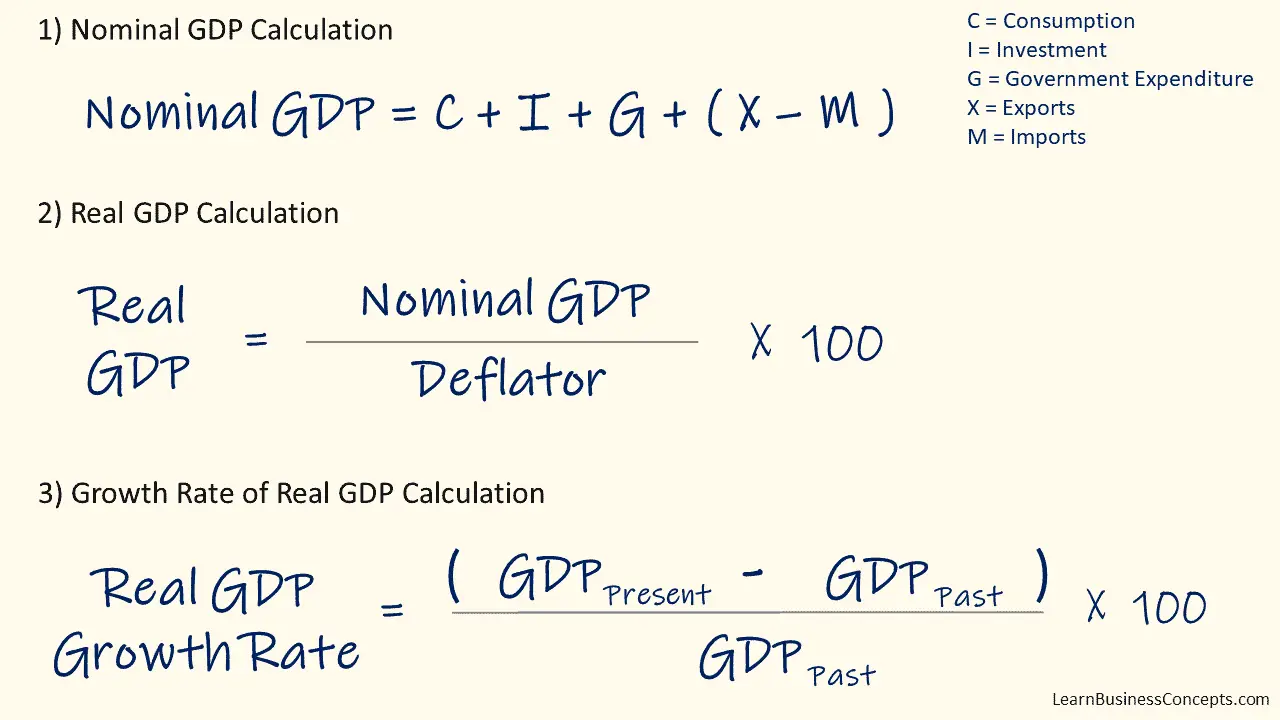
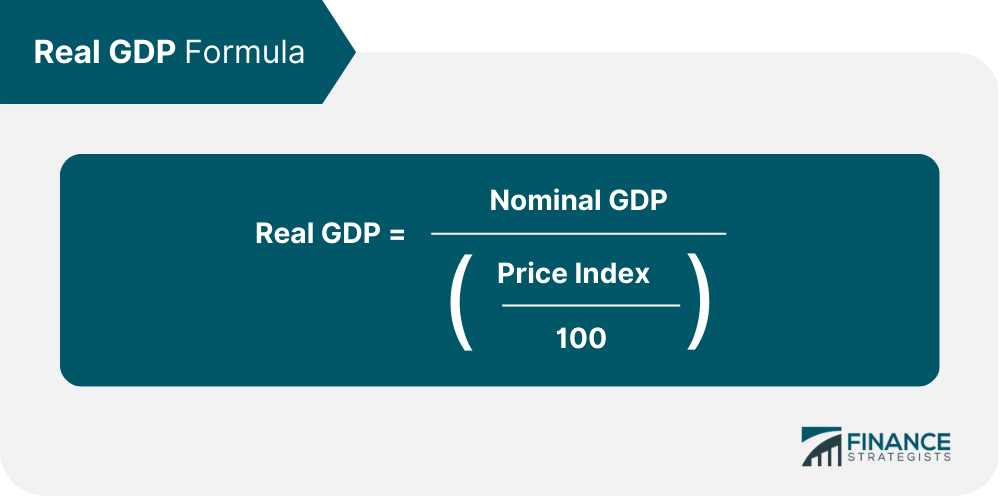
The real GDP calculation formula adjusts nominal output for price changes so you can see what actually grew versus what just got more expensive. It sounds straightforward until you open the dataset and find the base year has shifted again. I have spent years working with national accounts data, mostly for Southeast Asian economies, and the first time I tried to reconcile a government's published real GDP growth figure against their own price indices, I ended up spending three days tracking down why the numbers refused to line up. The standard approach chains volume indices from a reference year forward. You take the current year's prices divided by the base year prices, multiply by the base year quantities, and sum across all sectors. The formula looks like this: Real GDP = (Current Year Prices / Base Year Prices) × Base Year Quantities. Simple enough on paper. Messy in practice because governments rarely publish clean price deflators for every sector every year. I keep a quick reference sheet for the most common adjustments. When inflation runs above five percent annually, chain-weighting becomes essential rather than optional. Fixed base year methods start drifting significantly within three to five years in those environments. You get growth figures that look impressive but actually reflect price changes more than volume changes.
How I Actually Calculate These Numbers
My process starts with the expenditure approach. GDP equals consumption plus investment plus government spending plus net exports. For each component, I locate the price index published by the statistics bureau. Sometimes it is in the main report, sometimes buried in an appendix labeled "supplementary tables." Always check the methodology notes before trusting any number. Take the Philippines as an example. They switched to a 2018-based price system in 2020. Every analyst had to rework their models because the old chain-linked series no longer aligned cleanly. The adjustment was not trivial. Some sectors got revised upward, others downward, and the cumulative effect changed the interpretation of several years of growth data. I typically verify the consistency check by comparing quarterly growth rates derived from the GDP deflator against the official release. If they diverge by more than two percentage points, something went wrong with the volume estimates or the price indices are covering a different scope. I traced this issue once with a South Asian country where the agricultural deflator used retail prices while the GDP calculation assumed farm-gate prices. The gap produced roughly one percentage point of artificial growth per quarter.
Common Pitfalls That Waste Time
The biggest mistake I see analysts make is assuming nominal GDP divided by the GDP deflator gives you the right answer without checking coverage. The deflator often covers only certain sectors. If your economy has a large informal sector not captured in price surveys, the deflator will understate inflation and overstate real growth. I learned this the hard way working with a West African economy where informal trade accounted for nearly forty percent of economic activity. Another issue involves base year rot. Every time the statistical office updates their base year, previous real GDP series become less comparable. The revision can shift historical growth by one to three percentage points annually depending on how much relative prices changed during the old base period. Analysts should always flag these breaks in their notes rather than pretending the data is continuous. I also watch for seasonal adjustment errors. Unadjusted quarterly real GDP growth can swing wildly during harvest months for agricultural economies. The fix is to use chain-linked seasonally adjusted indices from the central bank rather than raw quarter-over-quarter calculations. This usually stabilizes the volatility enough to make sense of the underlying trend without smoothing away genuine cycles.
Get the Full Details
When This Approach Breaks Down
Real GDP calculation does not work well in hyperinflationary environments above fifty percent annually. Price indices become unreliable because markets clear in foreign currencies or barter. The official deflator lags actual price changes by several months, producing real growth figures that look positive while the economy shrinks in purchasing power terms. I encountered this with Venezuela around 2018-2019 where the published deflator showed moderate inflation but parallel market rates suggested something closer to four hundred percent annually. The alternative is to use physical volume indicators directly. Freight traffic, electricity consumption, night-time satellite imagery. These proxy measures avoid the price distortion problem entirely. They are rough but more reliable than deflated nominal values when inflation destroys the price signal. Digital economies present another challenge. Many services now have zero marginal cost. Free digital services generate enormous welfare but contribute little to measured GDP. I discussed this repeatedly with IMF staff during the pandemic when e-commerce and remote work expanded rapidly. The contribution to official GDP barely moved while household surplus increased substantially. No formula adjustment captured this cleanly in the national accounts framework.
Practical Tips That Actually Help
I always cross-check with the income approach as a sanity test. If the expenditure-side real GDP growth differs from income-side growth by more than two percentage points after adjusting for the statistical discrepancy, I dig into the component breakdowns. This catches errors in the investment deflator or misclassification of government transfers that would otherwise go unnoticed. When working with emerging markets, budget two to three times longer than you expect. The data revisions cycle is usually six to twelve months, and preliminary estimates get rewritten frequently. I recommend using the final revised series for any analysis rather than the initial release if your timeline allows. The difference between preliminary and final can change the interpretation of whether an economy is accelerating or decelerating meaningfully. One tool I find indispensable is the chained dollar series from the World Bank's WDI database. It provides consistent cross-country comparisons without the base year drift problem. The coverage is not complete for all developing economies but it covers enough to anchor your analysis when bilateral data conflicts arise.
I also keep a running log of methodology changes for each country I track. Base year updates, definitional shifts, coverage expansions. These changes accumulate quickly and cause confusion when analysts assume continuity where none exists. A simple spreadsheet noting the date of each revision saved me weeks of reconciling work during a project comparing ASEAN growth performance across multiple decades.