What Actually Happens When You Start Looking for a Home
The first thing most people get wrong is thinking the process starts with house hunting. It doesn't. It starts with understanding what you're actually buying and who's going to be involved once you put in an offer. I've been watching this cycle go down for over a decade, and the pattern never really changes. People fall in love with a kitchen and then spend six weeks discovering they can't afford the property taxes. A proper Realtor Home Buyer Guide should cover that gap between falling for a property and closing a deal. Most of the cheap ones online are just repackaged Zillow articles. They'll tell you to get pre-approved and then wander aimlessly through listings. That's not a guide. That's a checklist someone copy-pasted from a real estate blog in 2018.
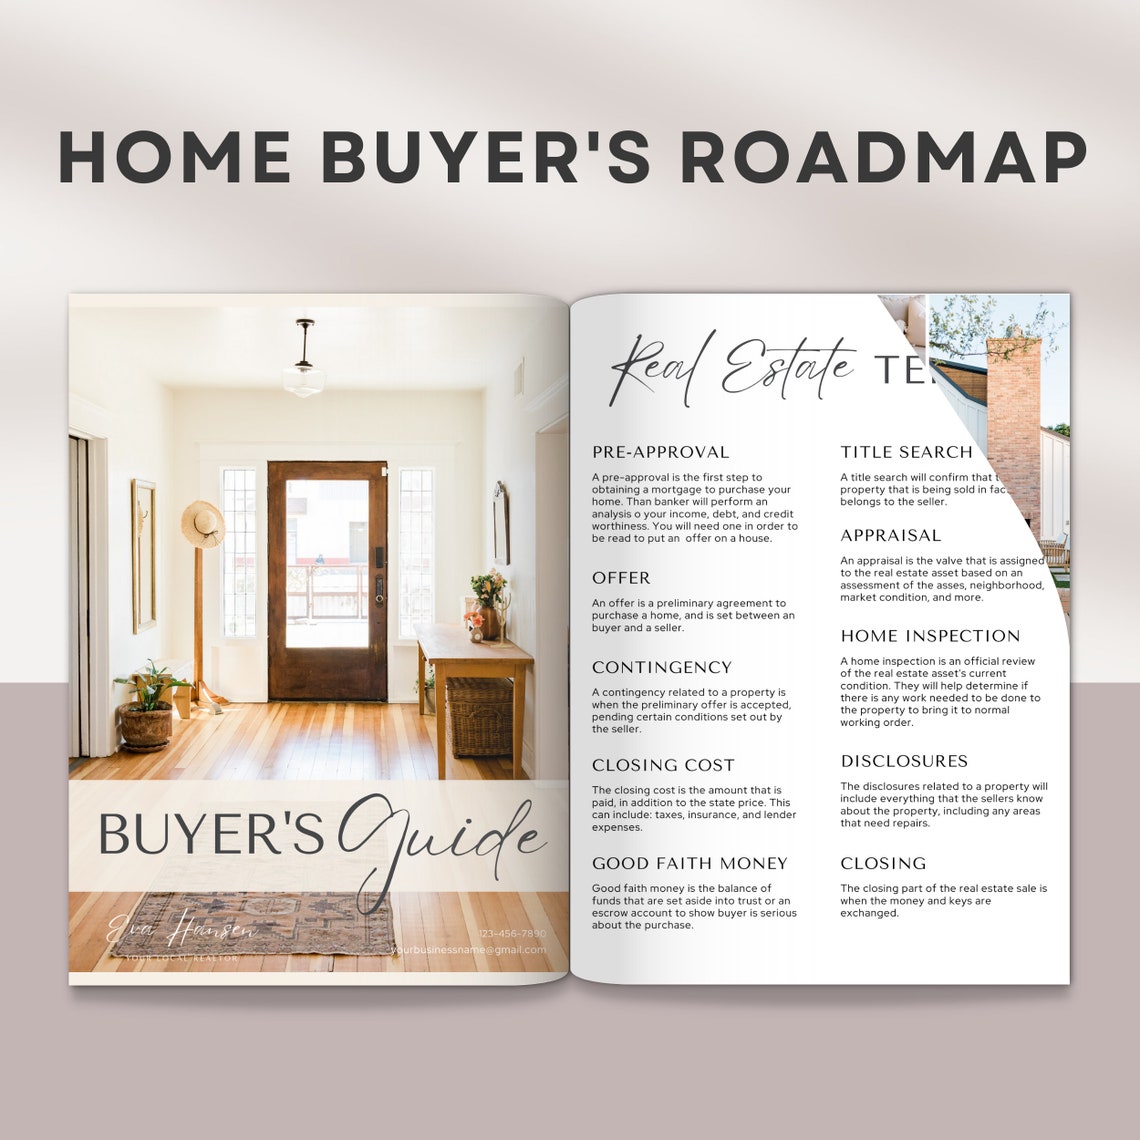
Realtor Home Buyer Guide
Here's what actually matters. The pre-approval letter you get from a lender isn't the same as pre-qualification. Pre-qualification is based on what you tell them. Pre-approval means they've checked your credit, verified your income, and run debt-to-income ratios. Sellers take pre-approval letters seriously. They will reject a higher offer from someone with just a pre-qualification because they know it might fall apart during underwriting. I had a client lose a bidding war last year on a house that was listed at $425,000. The other offer was $410,000 but came with a solid pre-approval from a local credit union. Ours was stronger on paper but the seller's agent flagged it as weaker because the lender hadn't pulled a full document review yet. Lesson: don't skip the pre-approval paperwork. Most first-time buyers also don't realize that the real estate purchase contract is where everything gets locked in. The listing price is just a starting point. The actual deal terms — inspection contingencies, financing timelines, earnest money amount — those are negotiable. A good guide will walk you through each clause. A lazy one will just link you to a form and hope you figure it out. Inspection contingencies are non-negotiable, regardless of how beautiful the staging looks. I once watched a buyer waive the inspection clause because the seller pushed hard and the house looked brand new inside. The foundation had a hairline crack that wasn't visible during a walk-through. Repair estimate came to $18,000. That buyer learned the hard way that "looks good" and "is sound" are two different things.
The Numbers Most Guides Skip
Beyond the purchase price, there are closing costs that typically run between 2% and 5% of the home price. On a $350,000 house, that's $7,000 to $17,500 you need to have available on top of your down payment. Title insurance, escrow fees, recording fees, transfer taxes — these aren't optional. Some states are heavier on transfer taxes than others. If you're buying in a high-fee state and your guide doesn't break this out, it's not giving you useful information. Then there's the appraisal gap problem. Lenders require the house to appraise for at least the purchase price. If it comes in low, you either make up the difference in cash or renegotiate. This happens more often than you'd think, especially in competitive markets where bidding wars push prices above comparable sales. A solid Realtor Home Buyer Guide should explain this scenario and how to prepare for it. Too many agents gloss over it because it sounds complicated and they'd rather keep things simple for the buyer. HOA fees are another trap. I've seen $400 monthly HOA fees turn into $600 after the buyer moved in, because the association had a special assessment for roof repairs on the condo buildings. The HOA documents should be reviewed before you make an offer, not after. Your agent should provide the HOA packet during the due diligence period. Read it. Look for pending special assessments, unhappy owners voting to replace the board, and reserve fund deficiencies. A weak reserve fund means a special assessment is coming.
Get the Full Details
Working With Your Agent
The agent relationship is where things get messy. Most buyer's agents work on commission, which means they get paid when the deal closes. That's not inherently bad — it aligns their interest with yours — but it does create a subtle pressure to close quickly rather than negotiate aggressively. I've seen agents push clients toward accepting a seller's counter-offer within 24 hours because they wanted the commission hit before month-end. Was it a bad deal? Not necessarily. But the urgency was manufactured, not organic. A good agent will push back on your behalf. They should be the one negotiating repair credits after inspections, requesting seller concessions on closing costs, and advising you on whether to walk away from a deal that's becoming too expensive. If your agent is agreeing with everything you say and never pushing back, that's a red flag. You're paying for their judgment, not their agreement. Commission structure has shifted recently. The National Association of Realtors settlement in 2024 changed how buyer agent commissions are structured and disclosed. In many markets, the seller still pays the buyer's agent commission, but it's no longer guaranteed or automatically baked into the listing. Some sellers are now offering lower buy-side commissions, which means your agent might get less than the traditional 2.5% to 3%. This doesn't necessarily hurt you, but it does mean your agent's incentive structure has changed slightly. It's worth asking your agent directly about how the commission works in your specific market.
Practical Steps That Actually Matter
Get your credit report before you start looking. Pull it from AnnualCreditReport.com — it's free, and you can get all three bureau reports staggered throughout the year. Check for errors. Dispute anything that looks wrong. A single late payment flagged incorrectly can drop your score by 50 points, and that difference might push you from a better mortgage rate to a worse one. On a $300,000 loan, a half-point rate difference is roughly $18,000 over the life of the loan. Shop multiple lenders. Don't just take the first pre-approval you get. Get quotes from at least three sources — a local credit union, a regional bank, and an online lender. The rates and fees vary significantly. I've seen the same borrower get quoted 6.75% by one lender and 6.375% by another for identical financial profiles. That's not a rounding error. That's real money over 30 years. Understand the difference between fixed-rate and adjustable-rate mortgages if you're considering an ARM. An ARM might start at 5.5% when a 30-year fixed is at 7%, but it adjusts after a set period — usually 5, 7, or 10 years. If you plan to sell or refinance before the adjustment kicks in, an ARM can save you significant money. If you stay in the house long-term and rates climb, you could end up paying more. There's no universal right answer. It depends on your timeline and your risk tolerance.
Save for the surprise expenses. Beyond closing costs and your down payment, budget for immediate repairs, furniture, appliances, and moving costs. The average first-time buyer underestimates post-closing expenses by about $8,000 to $12,000. Keep a buffer. When the water heater leaks three months after you move in, you'll be glad you have it.
When the Guide Falls Short
Most online Realtor Home Buyer Guides fail because they're written by people who haven't actually closed deals in the current market. They reference rules and timelines that were relevant three years ago. Interest rates have moved. Inventory levels have shifted. Seller expectations have changed. A guide that doesn't account for these variables is giving you outdated advice. Some guides also push buyers toward buyer's agent representation without explaining that not all agents operate the same way. Two agents in the same brokerage can have very different communication styles, negotiation approaches, and availability. Checking reviews on Google and asking for references from recent clients is worth the fifteen minutes it takes. Don't just pick the first agent you meet. The biggest limitation of any written guide is that it can't account for your specific situation. Every transaction has unique elements — the seller's motivation, the condition of the property, local market dynamics, your financing path. A guide can give you framework and warning signs, but it can't replace a competent professional who's working through your actual deal in real time. The best guides acknowledge that. The ones that pretend otherwise are selling something they can't deliver.
If you're looking for something more structured, search for guides from established local real estate organizations or brokerages in your specific market. National guides tend to be generic. Local ones reflect the actual conditions you'll face — the inspection norms, the typical negotiation patterns, the closing cost variations by county. That granularity matters more than you'd expect.