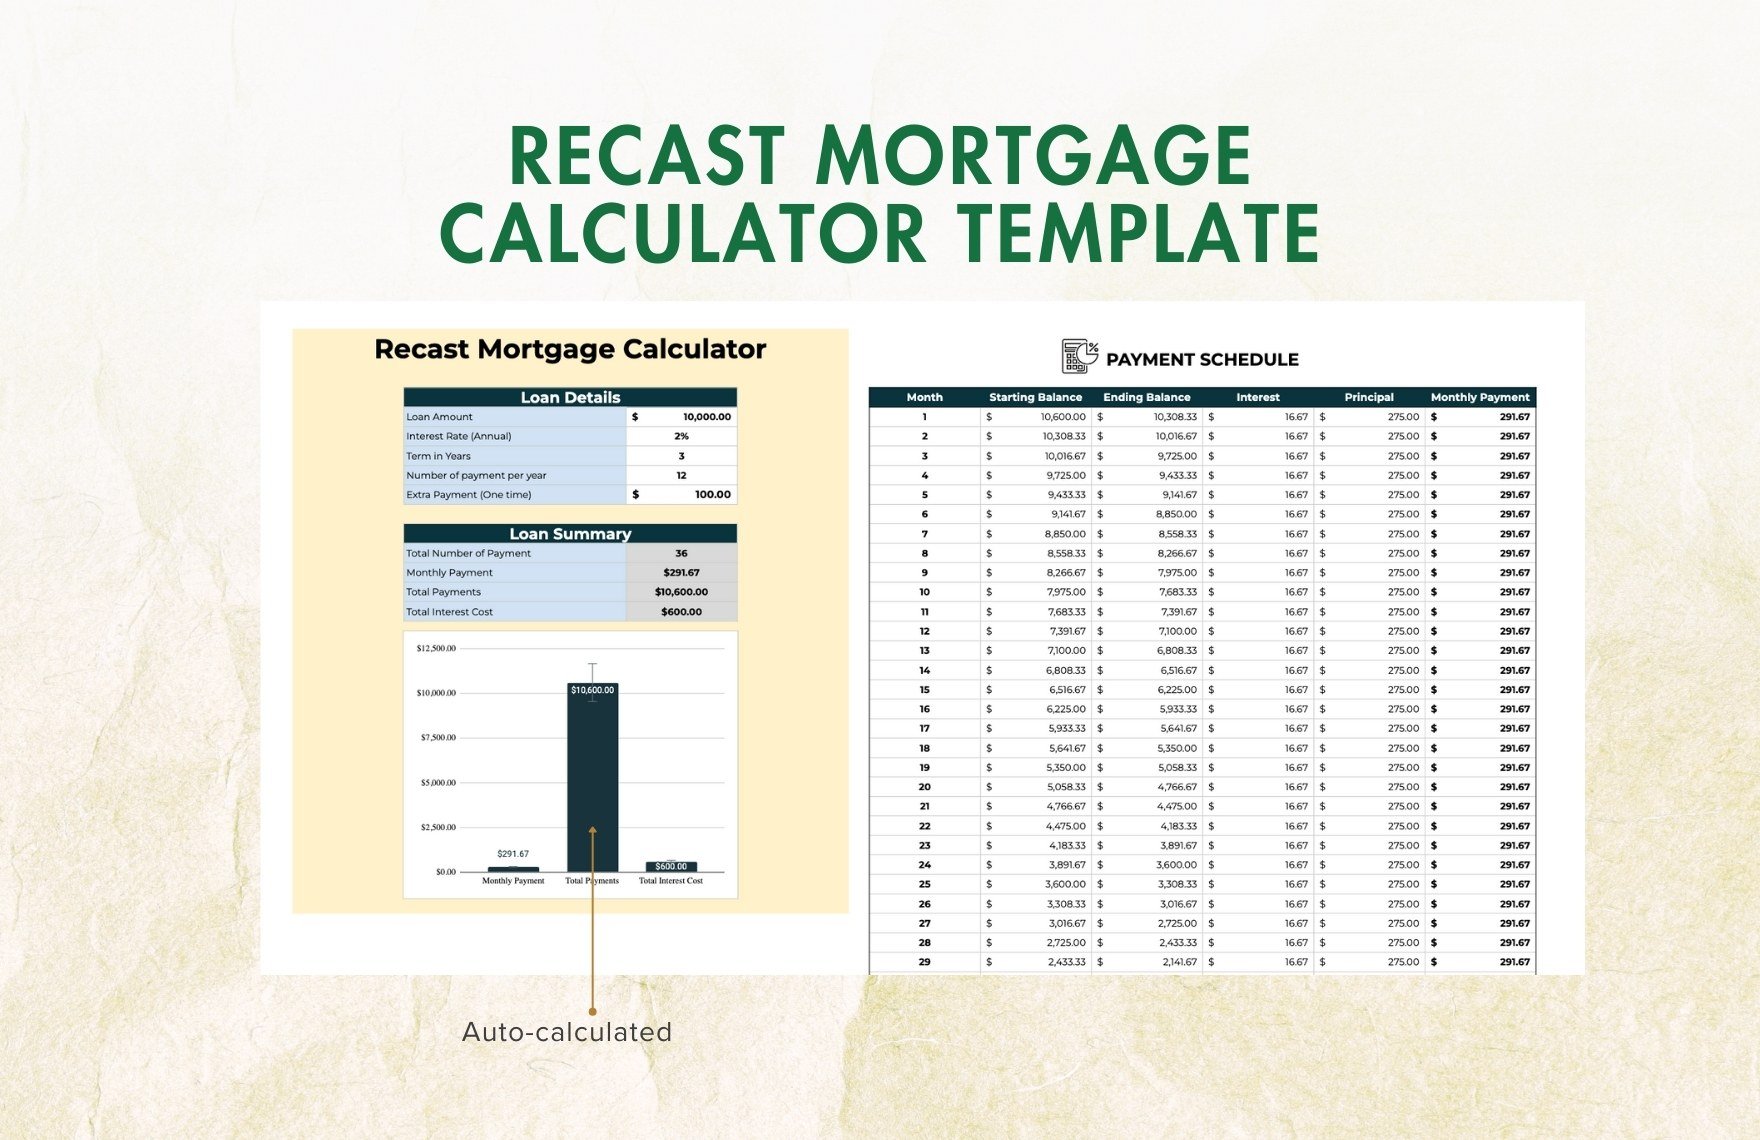
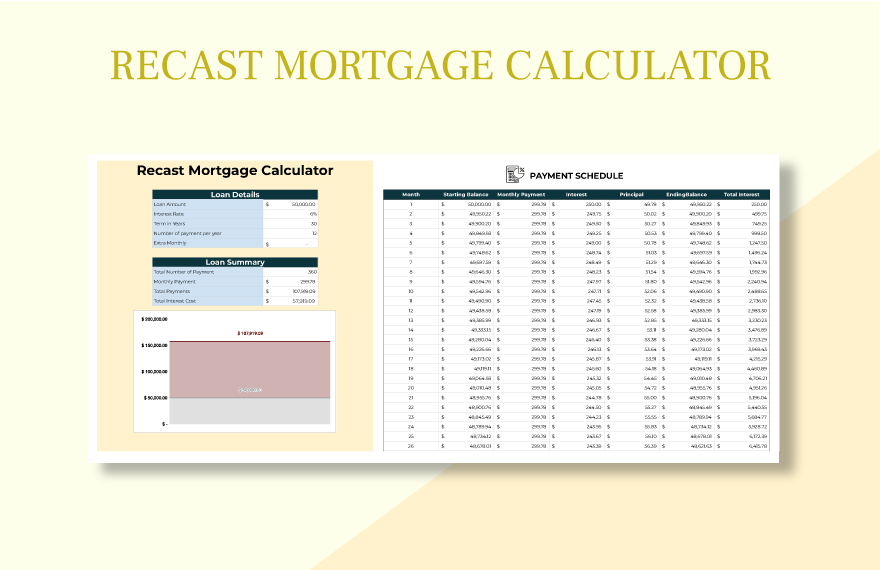
What Recasting Actually Is
A recast happens when you make a large lump-sum payment toward your mortgage principal and the lender recalculates your remaining monthly payment based on that lower balance. Your interest rate stays exactly the same. Your loan term stays the same. Only the monthly number changes. This is different from refinancing, which involves a new application, new rate, new closing costs, and a completely new note. I've seen people confuse the two constantly. It's easy to do. A recast is essentially just a payment of principal with a paperwork recalculation attached to it. That's it. The math is straightforward, which is why having a reliable
Recasting Mortgage Calculator
before you call your servicer is useful. You want to know what you're working with before you have a conversation where someone might try to sell you something else.How to Calculate It
The core formula is not complicated, but most online calculators get it wrong because they skip a few real-world details. Here's how it actually works. First, you need your current outstanding principal balance. Not your original loan amount. The balance you actually owe right now. Then you subtract the lump sum you're planning to pay. That gives you the new principal. From there, you take the number of months remaining on your loan and plug both numbers into a standard amortization formula to get the new monthly payment. The formula itself looks like this:
M = P × [r(1+r)^n] / [(1+r)^n - 1] P is your new principal after the lump sum. r is your monthly interest rate, which is your annual rate divided by 12. n is the number of remaining payments. If your rate is 6.5%, your monthly rate is 0.0054167. If you have 28 years left, that's 336 months. Here's where people mess up. They use the original loan term instead of the remaining term. I watched someone calculate a recast for a loan that was seven years into a 30-year mortgage and use 360 months instead of 276. Their estimated savings were completely wrong. Use the remaining balance and remaining months, not the original numbers.
Get the Full Details

Another detail that trips people up is whether your payment includes escrow. Recasting only affects the principal and interest portion. Your escrow payment for taxes and insurance stays separate and usually doesn't change. Make sure your calculator separates those two pieces. If it doesn't, you'll think your total monthly outlay drops more than it actually does.
Specific Problem I Ran Into
Working with a client last year, I hit an edge case that most calculators don't handle. The borrower had an FHA loan with a monthly MIP (mortgage insurance premium) that was locked in for the life of the loan because they put less than 10% down. They wanted to recast after paying down a significant chunk of principal. The standard recasting calculation showed a nice reduction in their P&I payment, but the MIP was calculated as a percentage of the original loan amount, not the current balance. So their total payment dropped, but not nearly as much as the basic formula suggested. The servicer kept the MIP based on the original financed amount. The workaround was simple once I knew what to look for. I pulled the actual FHA guidelines, found that the annual MIP is 0.55% of the original base loan amount for loans beyond 11 years, and manually subtracted the correct MIP from the recalculated payment instead of letting the online tool apply a generic insurance figure. It cut the estimated monthly savings by about $47. That $47 difference mattered because it changed whether the recast made financial sense compared to just keeping the cash and investing it. Most free calculators online would have told that borrower they were saving over $200 a month. The real number was closer to $150. That kind of gap is enough to make someone commit to a recast that actually isn't worth it.
Counter-Intuitive Things to Know
One thing nobody tells you: recasting doesn't always save you money in the long run compared to other strategies. If your mortgage rate is 3.2% and you could invest that same lump sum at 7% in a diversified portfolio, you'd come out ahead financially by investing instead of recasting. The interest savings from a recast are essentially the value of eliminating debt at your mortgage rate. If your mortgage rate is low, that elimination is cheap. Higher-rate mortgages, say above 6%, are where recasting starts to make genuine mathematical sense. Another thing that surprises people is the minimum payment requirement. Most lenders require a minimum recast amount, usually between $5,000 and $10,000. Some go as high as $25,000. A few won't do recasts at all. You need to check your servicer's policy before you do any math. I once calculated a recast for a borrower who only had $3,000 in extra principal available. The servicer rejected it outright because it didn't meet their $5,000 floor. All that work for nothing. There's also the fee structure. Some lenders charge a flat fee, typically between $250 and $500. Others don't charge anything. A handful will roll the fee into the loan balance, which technically means you're not really making a pure principal payment. Check how the fee is handled. If it's rolled into the loan, your new principal is higher than you think, and your savings are smaller.
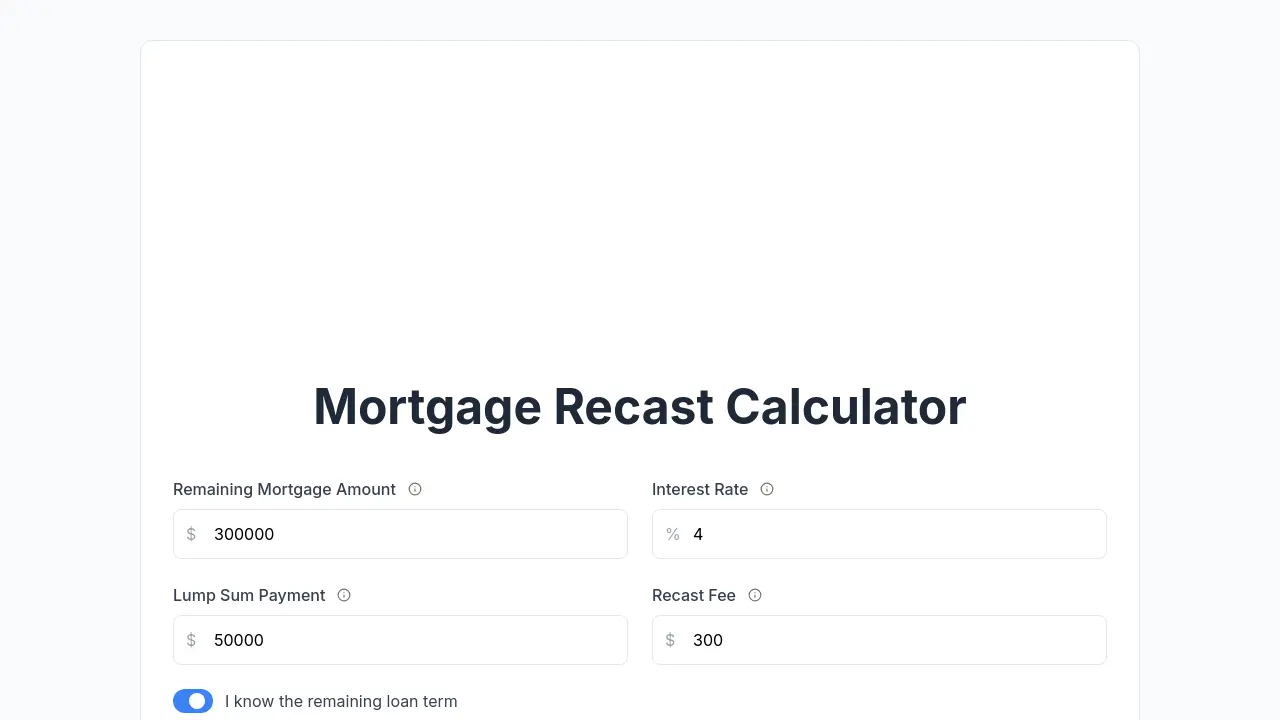
What a Proper Calculation Looks Like Step by Step
Let me walk through a concrete example with real numbers so you can see the mechanics. Current principal balance: $340,000. Annual interest rate: 5.75%. Remaining term: 22 years, 4 months, or 268 months. You have $40,000 to put toward the loan. Step one: New principal is $300,000. Step two: monthly rate is 0.0575 divided by 12, which equals 0.0047917. Step three: plug into the formula. The new payment comes out to approximately $1,753.58 per month. The old payment on the $340,000 balance was about $1,987.84. That's a reduction of roughly $234.26 per month.
Now factor in the recast fee. If the lender charges $350 and you pay it upfront, your total cost is $40,350. At $234.26 in monthly savings, you'd recoup the fee in about 1.7 months. If the fee gets rolled into the loan, your new principal becomes $300,350 and your payment is $1,755.69 instead. The difference is negligible here but matters more with smaller lump sums. Here's the important part that people ignore. How long you plan to stay in the house matters enormously. If you're moving in three years, the total savings from that $234 monthly reduction is about $8,430. If you stay for ten years, it's closer to $28,000. Compare that against the opportunity cost of locking up $40,000 in home equity that you can't touch without selling or refinancing again.
When Recasting Is a Bad Idea
I want to be blunt about this because a lot of content online treats recasting like a universal win. It's not. If you have a mortgage rate below 4%, recasting is almost certainly the wrong move unless you have a deep psychological need to be debt-free. The math doesn't favor it. If you're near retirement and considering draining your savings to recast, pause. Illiquid home equity is not a safety net. An emergency fund that covers six months of expenses is far more valuable than a slightly lower payment. I've seen people recast their mortgages, drain their savings to make the payment, and then face a medical bill or car repair that forces them into high-interest credit card debt. That's a terrible trade. Also, if your loan has a prepayment penalty, verify it before you do anything. Some loans charge penalties for large principal payments. A 1% penalty on a $40,000 recast is $400 that vanishes. It's rare these days but still exists on certain jumbo loans and a few state-specific programs.
There's another scenario worth mentioning. If you're close to paying off your loan anyway, recasting has diminishing returns. I had a borrower with nine months left on their mortgage who wanted to recast with a $15,000 payment. The monthly savings were maybe $90. They'd be debt-free in less than a year regardless. The lump sum would have been better used elsewhere, even just sitting in a high-yield account earning interest while they waited to own the house outright.
Where to Find a Calculator That Actually Works
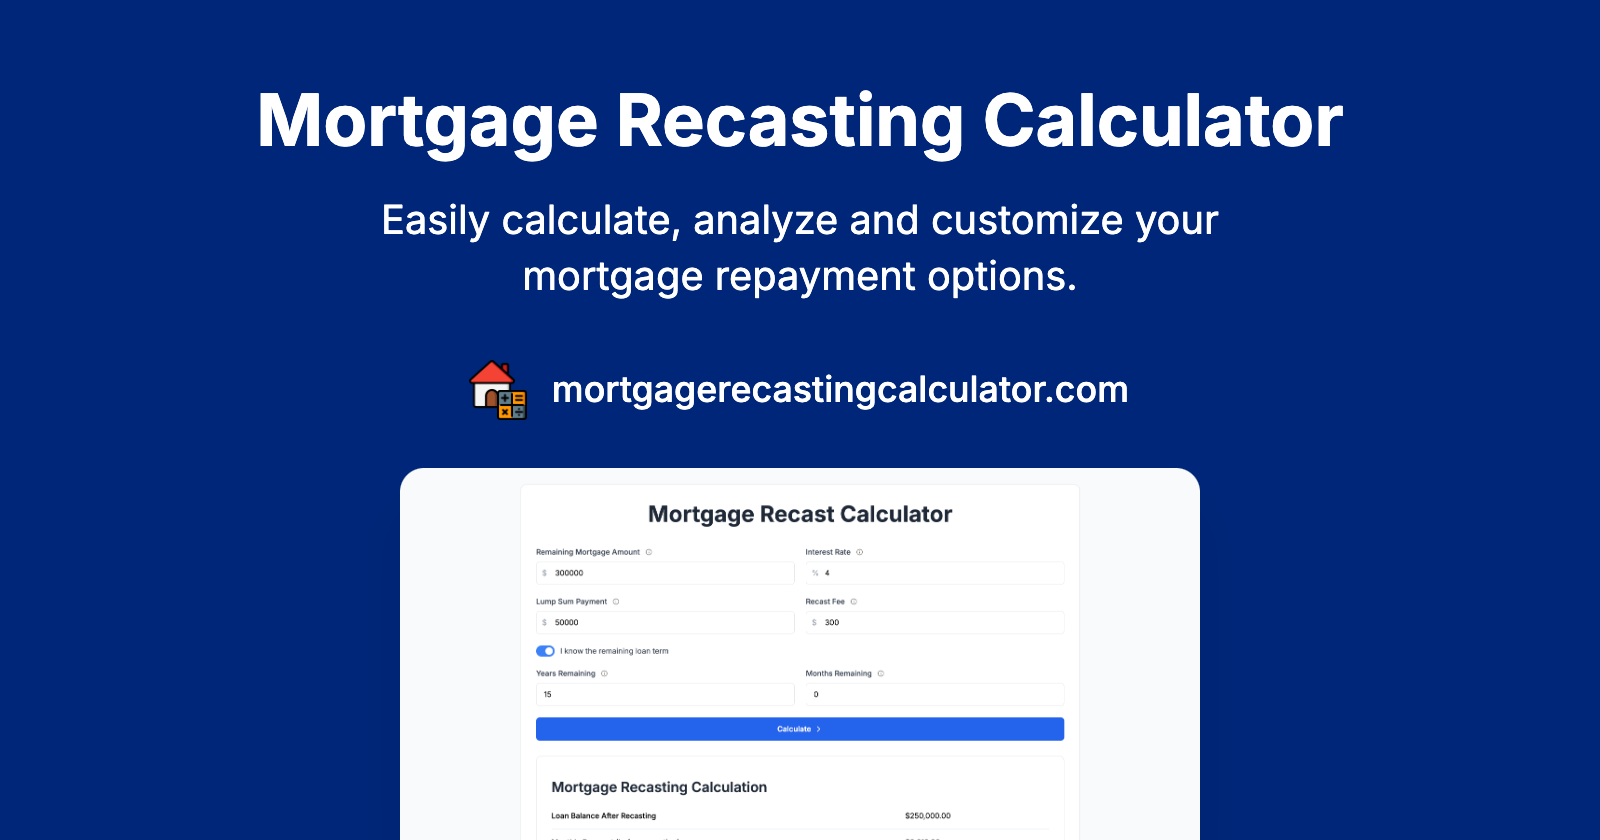
There are plenty of free Recasting Mortgage Calculator tools online, but quality varies wildly. The ones built by major mortgage lenders tend to be the most accurate because they're tied to actual underwriting systems. Independent financial sites often use generic formulas that ignore escrow, insurance, and servicer-specific quirks. My recommendation is to start with your lender's own tool if they have one. If they don't, use a calculator from a reputable mortgage industry source like Mortgage Research Center or a major bank's educational portal. Cross-check the numbers manually using the formula I laid out above. If the calculator's result is more than 2% off your manual calculation, it's probably rounding something incorrectly or using the wrong remaining term. I don't link specific third-party tools because they change frequently and I can't guarantee current accuracy. But the manual calculation method I described will always work. It requires no download, no account, and no faith in anyone's software. You just need a calculator app and about five minutes.
The Bottom Line Without a Conclusion
Recasting is a straightforward tool that gets oversimplified in most explanations. The actual outcome depends on your rate, your remaining term, your servicer's policies, and what else you could do with that money. Do the manual math. Check the minimums. Know your rate relative to alternative returns. Then decide.