What the Recovery Startup Business Gross Receipts Test Actually Does
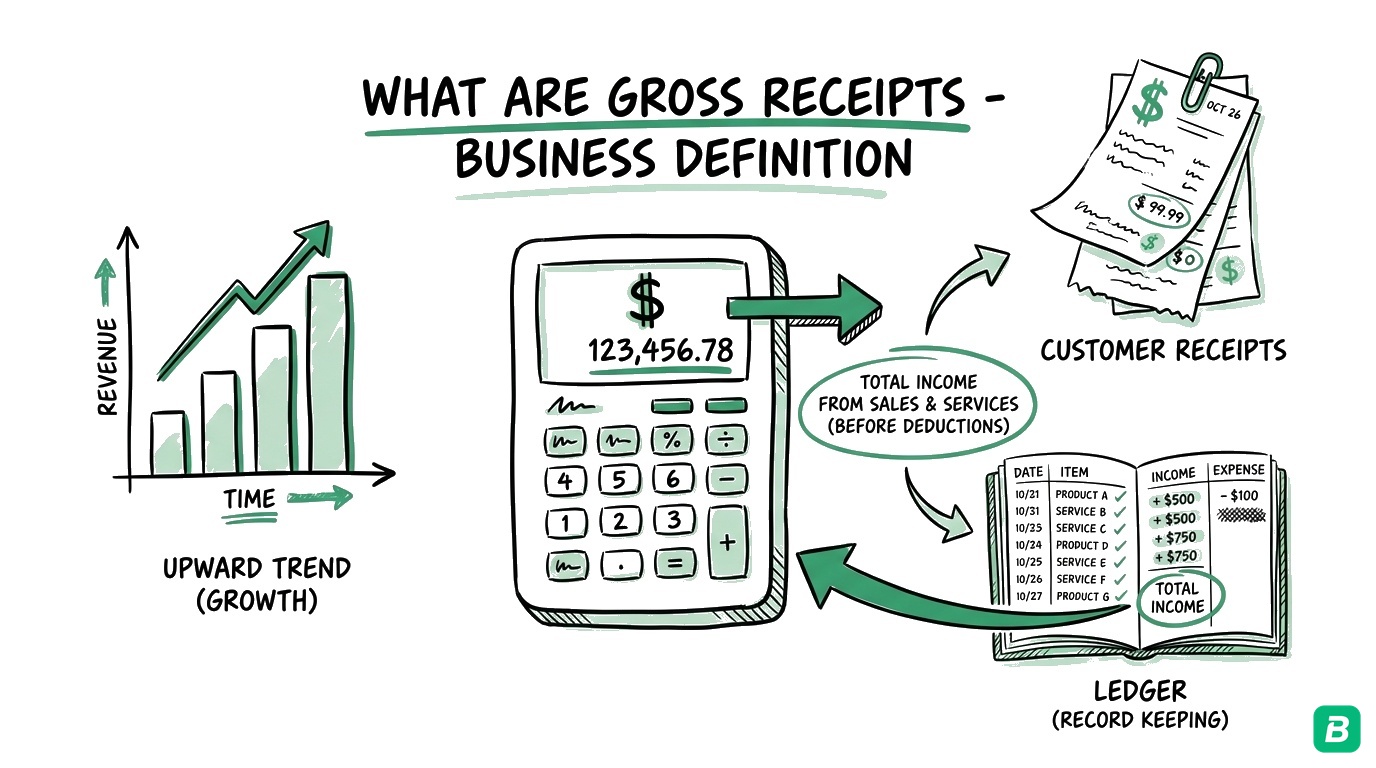
The recovery startup business gross receipts test is a UK provision that lets companies claim startup losses against other income, but only if they haven't crossed a certain revenue threshold. It sits inside the startup loss relief rules (section 77A of ITA 2007) and applies specifically to companies that are in some form of financial difficulty or recovery scenario. The basic mechanism is straightforward: you can carry back or set against total profits a qualifying company's trading losses from its first four tax years, provided it passes the gross receipts test at the relevant time. Here is how I actually work through it when a client brings me a file. First, confirm the company qualifies as a startup business. That means it is a close company, not under 51% control by another body corporate, and its gross receipts for the relevant accounting period do not exceed the threshold. The current threshold is £1 million. Simple enough on paper. The tricky part is defining what counts as gross receipts. It is not the same as turnover on your accounts. Gross receipts means all incoming credit arising from the ordinary activities of the trade, whether or not it is revenue for accounting purposes. That includes things you might not immediately think of: grants received, VAT reclaimable on sales (yes, really, the VAT element counts), intercompany payments that look like trading receipts, and even some capital receipts that have a revenue character. I once spent three days arguing with a colleague about whether a grant receivable under a local authority business rates relief scheme counted. The answer was yes, and it pushed the company just over the limit.
Once you have worked out gross receipts, you need to check the timing. The test applies to each accounting period within the first four years of trading. You look at the gross receipts for that period and compare them to £1 million. If they stay under, the relief is available. If they exceed it, the relief is lost for that period and any subsequent periods in the four-year window. It is not a rolling test. It is annual, and it is unforgiving. Another practical step most people miss: you need to check whether the company is in financial difficulty or recovery. The qualification requires that the company is either insolvent, or its liabilities exceed its assets, or it is carrying on a trade in reconstruction or recovery. This is where things get murky. I have seen cases where a company technically qualifies as being in recovery because its directors passed a resolution for voluntary arrangement, but its trading had barely dipped. HMRC have pushed back hard on artificial constructions here, so document the actual financial state of the company, not just the legal paperwork. After you confirm eligibility, the claim itself is filed through the self-assessment computation. For companies, this goes through the CT600 with the appropriate boxes for startup loss relief. The loss is set against total profits of the current and preceding accounting periods, up to four years back. There is no requirement to use the earliest loss first, which catches people out. You can choose which periods to offset against, and strategic selection matters if you have fluctuating profits across the four years.
I should note the one area where this breaks down completely: if the company has side income that is not trading in nature but still counts as a gross receipt, it can distort the test. A property rental business running alongside the trading business will have its rental income folded into gross receipts. A friend of mine had a client with a trading loss claim that was blocked because the company owned a small holiday let that generated £40,000 in gross receipts in the relevant year. The property business was entirely separate and perfectly legitimate, but it tanked the startup loss relief. The workaround was to have the property business carried by a different company altogether, but that required restructuring before the end of the accounting period, which was tight. There is also a nuance about group companies. If the startup business is part of a group, you must consider whether the parent or sister companies' transactions with the startup count as gross receipts. Intercompany invoices, management fees charged back to the parent, license fees paid to affiliates. All of it counts. I learned this the hard way when a group structure meant that every internal service charge inflated the subsidiary's gross receipts above the threshold without anyone in finance noticing until the CT return was submitted. The final practical point is that the test uses gross receipts, not net receipts. VAT-inclusive figures matter. Making sure your accounts team knows to look at the VAT-exclusive figure is not enough. You need the gross figure, which means including the output tax element on taxable supplies. This alone causes misreads in roughly a quarter of the cases I review.
Get the Full Details
When This Provision Fails You
The gross receipts test is blunt. It does not distinguish between healthy growth and wasteful inflows. A company that receives a large one-off grant, or has a spike in receipts because it switched to invoicing earlier in the cycle, fails the test the same way a company running out of control would. There is no materiality threshold. There is no de minimis allowance. £1,000 over and the relief disappears for the entire period. If the company is already past the four-year window, this relief is irrelevant. The startup loss relief expires four years from the start of trading. After that, normal loss relief rules apply, which are far less generous for early-stage companies. Planning around this deadline is something I wish more founders understood earlier.