What an RV Loan Calculator Actually Does For You
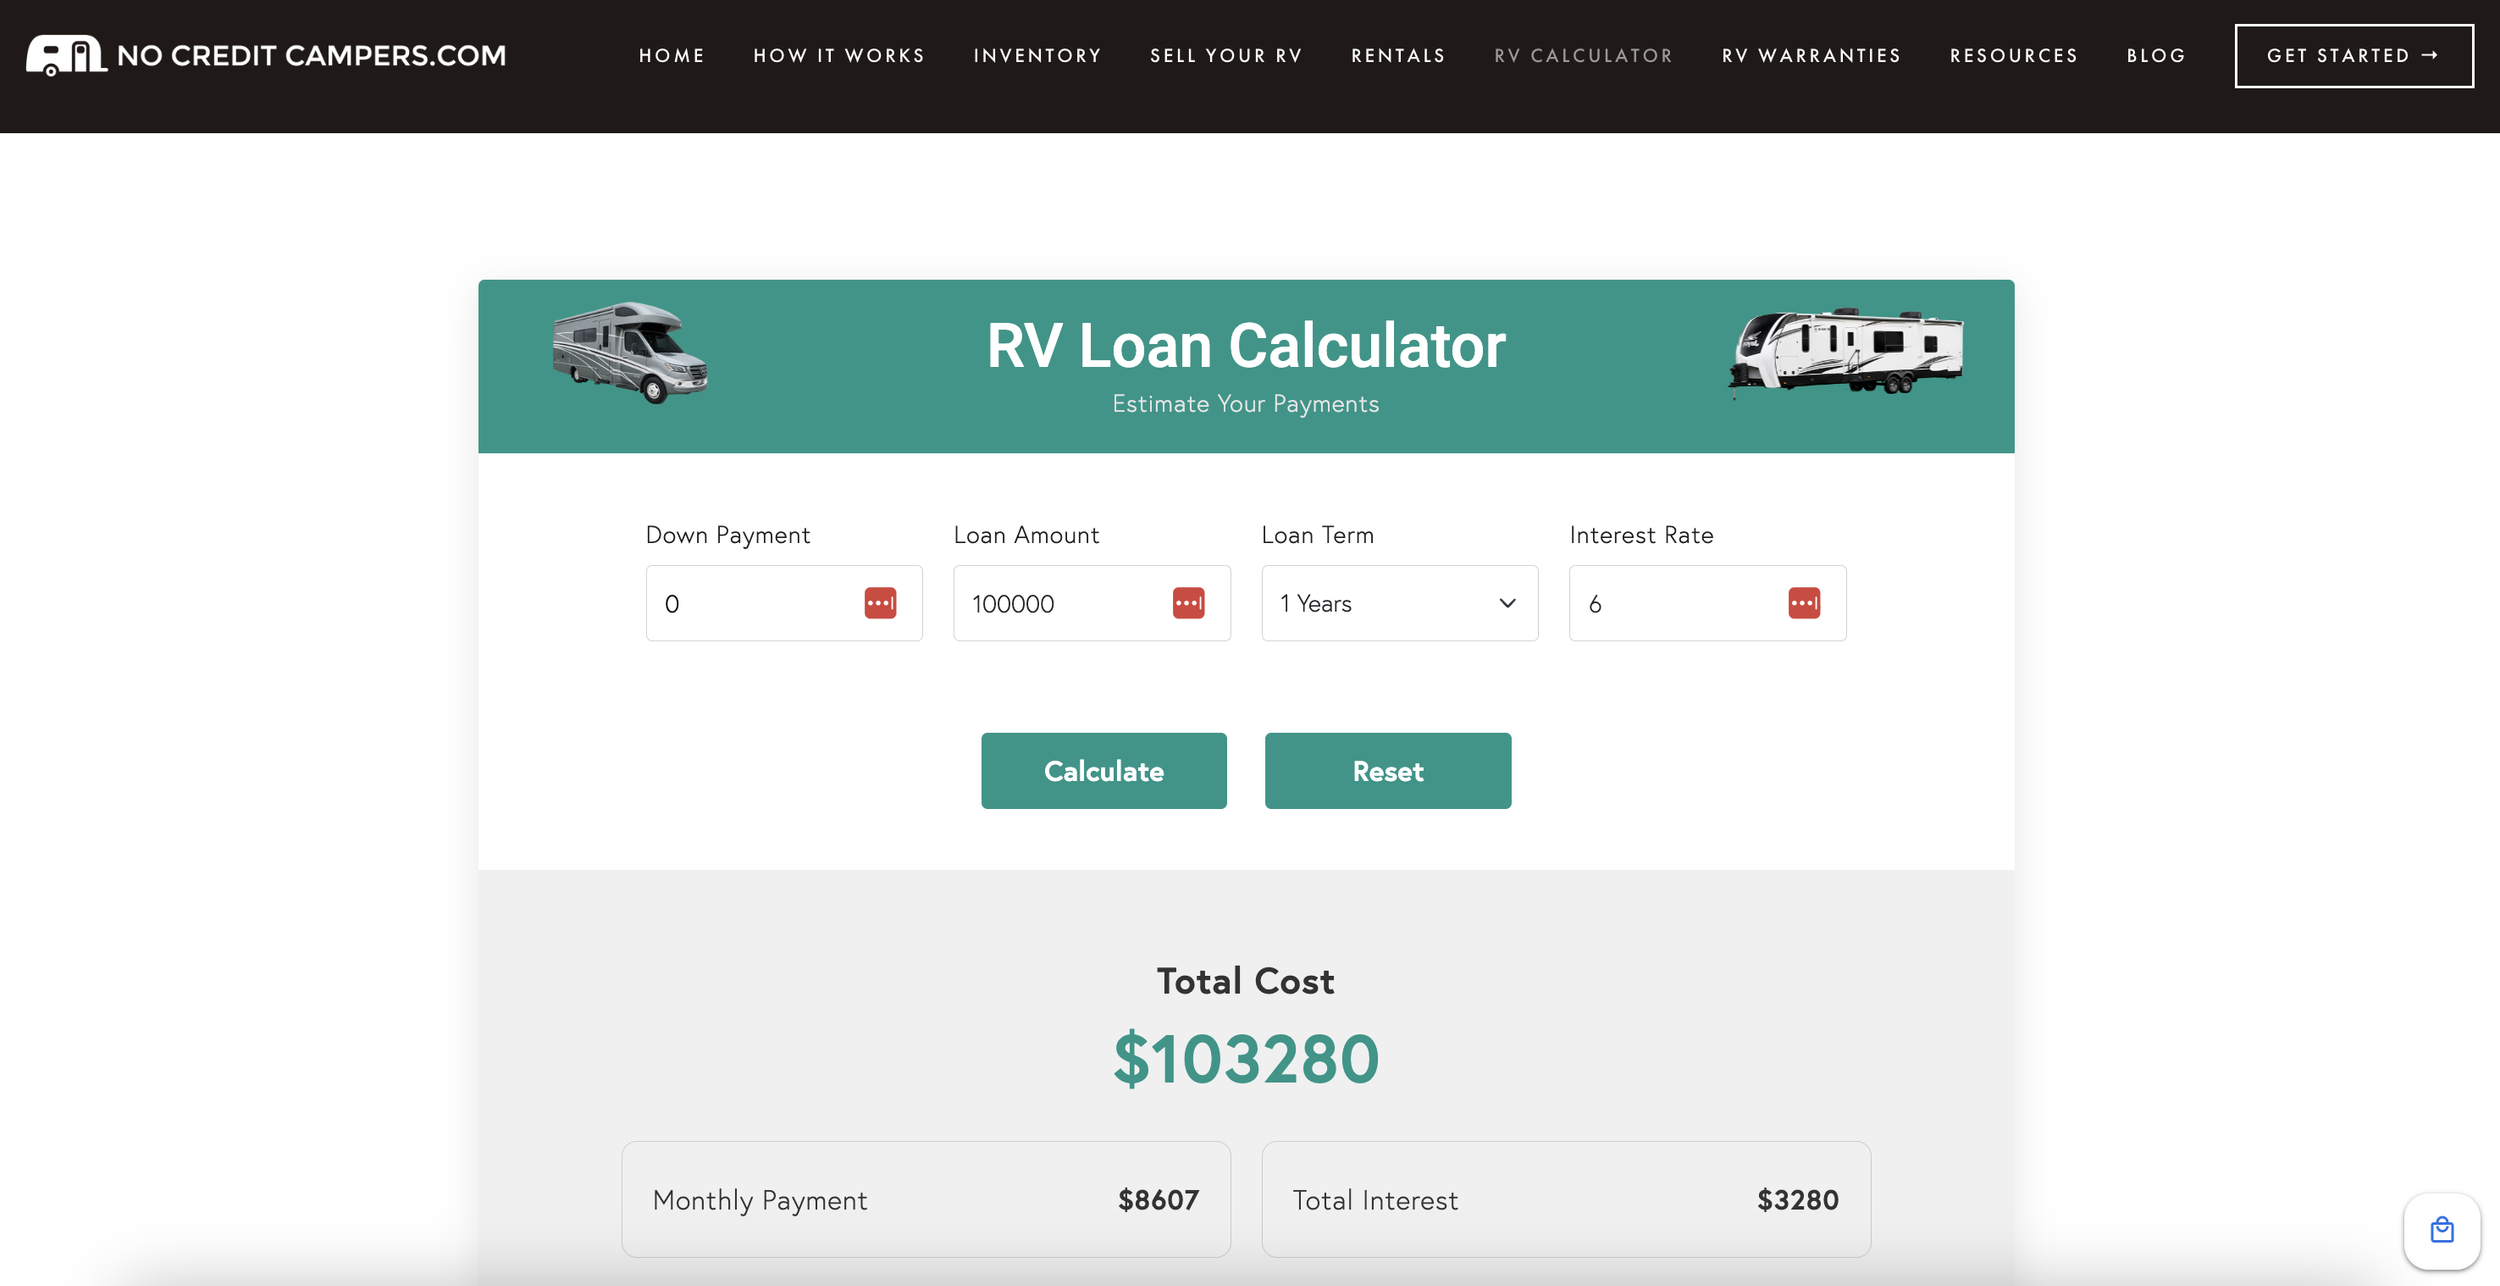
A Recreational Vehicle Loan Calculator is a tool that takes your down payment, loan term, interest rate, and the vehicle price, then works out what your monthly payment will look like before you sit down at a dealership. Most people use it to avoid walking into a sales office with no idea what they can afford. That's useful, but the standard output only tells you about one thing. It does not tell you the total cost of the loan, the breakdown between principal and interest, or how much you'd save by shortening the term by two years. Most free calculators online use the same amortization formula that lenders use. It compounds your interest monthly based on the remaining principal balance. The basic output gives you a monthly payment number. A more complete calculator will also show you the total interest paid over the life of the loan, the amortization schedule for each payment, and comparison charts between different terms. The math itself is straightforward. The value comes from adjusting variables quickly to see how small changes affect your total cost. I spent three years working loan comparisons for an RV dealership before moving into finance consulting. One thing I learned early is that most customers fixate on the monthly payment and ignore the annual percentage rate, which includes points, origination fees, and sometimes dealer-added products bundled into the loan. A calculator that only shows payment without the APR is basically decorative. Look for one that breaks out the full rate and lets you input any dealer fees or documentation charges separately.
The Edge Case That Made Me Build My Own Spreadsheet
About four years ago, I ran into a situation where a customer was quoted a 6.5 percent rate on a Class C motorhome for a 120-month term, and the monthly payment looked fine on paper. But when I pulled the actual contract, the dealer had rolled a $2,400 extended warranty and a $1,200 gap insurance package into the financed amount without adjusting the rate. The calculator showed a payment based on the vehicle price alone. The real payment was higher by about eighty dollars a month, and the customer ended up paying roughly six thousand dollars more in interest because the loan balance was inflated from the start. The workaround I used was to add a field in my spreadsheet for added product costs and finance charges, then run two scenarios side by side. One with the base vehicle price only. One with everything rolled in. The difference between those two scenarios is usually where dealers make their margin on the back end. If your calculator does not let you separate those costs, you are flying blind.
Common Mistakes People Make With RV Loan Calculators
The first mistake is assuming the calculator output is a quote. It is not. Lenders use credit-based pricing, and your actual rate may be higher or lower depending on your score, debt-to-income ratio, and whether you are buying new or used. A second mistake is ignoring prepayment penalties. Some RV loans have them, especially on shorter terms or from certain credit unions. A calculator that does not let you model early payoff will give you a best-case number that does not match reality if you plan to sell or trade within three years. A third mistake is using the calculator for a trailer or fifth wheel without accounting for the fact that these are often classified differently. Lenders frequently treat travel trailers as personal property rather than recreational vehicles, which means higher rates and shorter maximum terms. Make sure your calculator distinguishes between motorhomes, travel trailers, and fifth wheels, because the numbers shift significantly depending on the category.
Get the Full Details

What to Look for in a Good Calculator
The tools worth using will let you input the purchase price, your down payment, the loan term in months, the annual interest rate, and any additional fees or taxes. They should show you the monthly payment, total interest, total cost of the loan, and ideally an amortization schedule. Some will also let you model prepayments or compare two loan scenarios at once. The ones that only show a single payment number are incomplete at best. If you want something reliable and free, there are a few solid options. NerdWallet has a clean RV loan calculator that lets you adjust term length and see the interest breakdown. Bankrate's version includes a comparison table for different rates and terms. For a more hands-on approach, I built a spreadsheet that tracks every variable I mentioned plus the added-cost scenario. It takes about ten minutes to set up once, and then you can run unlimited comparisons without entering your information into a form field.
Why the Monthly Payment Is Almost the Wrong Number
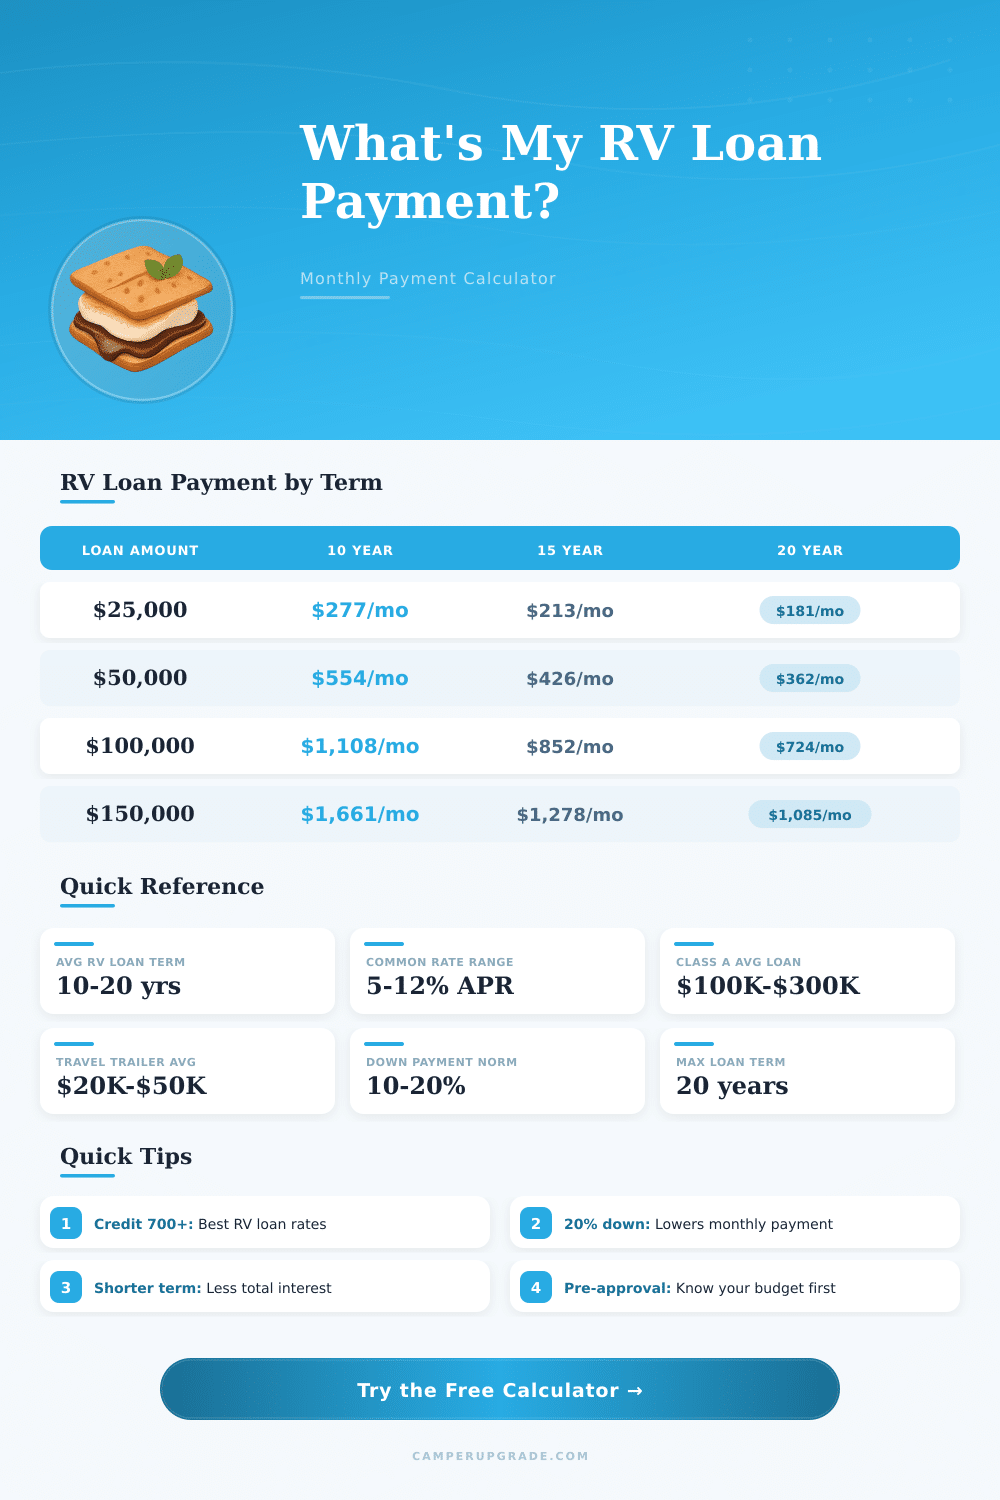
When you focus on the monthly payment, you are optimizing for cash flow, not total cost. A sixty-month loan at seven percent and a one hundred twenty-month loan at the same rate will produce very different total interest amounts, even if the monthly payment feels manageable on the longer term. Shortening a loan from five years to three years on a forty thousand dollar RV might raise your payment by roughly two hundred fifty dollars a month, but it can cut your total interest by nearly four thousand dollars over the life of the loan. That is a real number, not a theoretical one. The flip side is that stretching to one hundred twenty months or longer can look attractive on paper while quietly inflating your total cost. On a typical RV purchase, extending from sixty months to one hundred twenty months at current rates will often double the interest you pay, even though the monthly payment stays under the threshold that makes it feel comfortable. This is why dealers push longer terms. It keeps the payment low and the approval odds high, but it costs you significantly more in the end.
When a Calculator Will Mislead You
Online calculators assume a fixed-rate, fully amortizing loan. They do not account for variable-rate adjustments, balloon payments, or the way some lenders handle prepayment penalties. If you are looking at a dealer-arranged loan with a balloon clause, the calculator will give you a payment that does not reflect the final lump sum due at the end. A balloon payment on an RV loan might range from ten to twenty percent of the original loan amount, and that number will not show up in any standard calculator output unless you add it manually. Another scenario where calculators fail is with older RVs. Lenders often refuse to finance units over fifteen or twenty years old, or they require larger down payments and charge higher rates. A calculator will happily produce a number for a twenty-year-old fifth wheel, but no lender in their right mind would fund it on the terms the calculator assumes. Always check lender age requirements before you trust the output.

Practical Steps Before You Take Your Numbers to a Dealer
Run at least two scenarios using your calculator. One with the lowest rate you qualify for based on your credit score. One with a rate that is two percentage points higher, just to see how sensitive your payment is to rate changes. Then take those numbers to a credit union before you visit the dealership. Credit unions typically offer RV loans at rates one to two points below what most dealers can arrange, and they are more likely to finance older units if you have a solid relationship with the branch. Bring your amortization schedule with you. Dealers respect customers who understand how the loan actually works. It signals that you are not going to accept the first rate they throw at you. The entire process from running the calculator to getting pre-approved should take less than an hour if you have your credit score, down payment amount, and target vehicle price ready. If it takes longer than that, you are probably entering too much information into too many different tools instead of focusing on the variables that actually move the numbers.