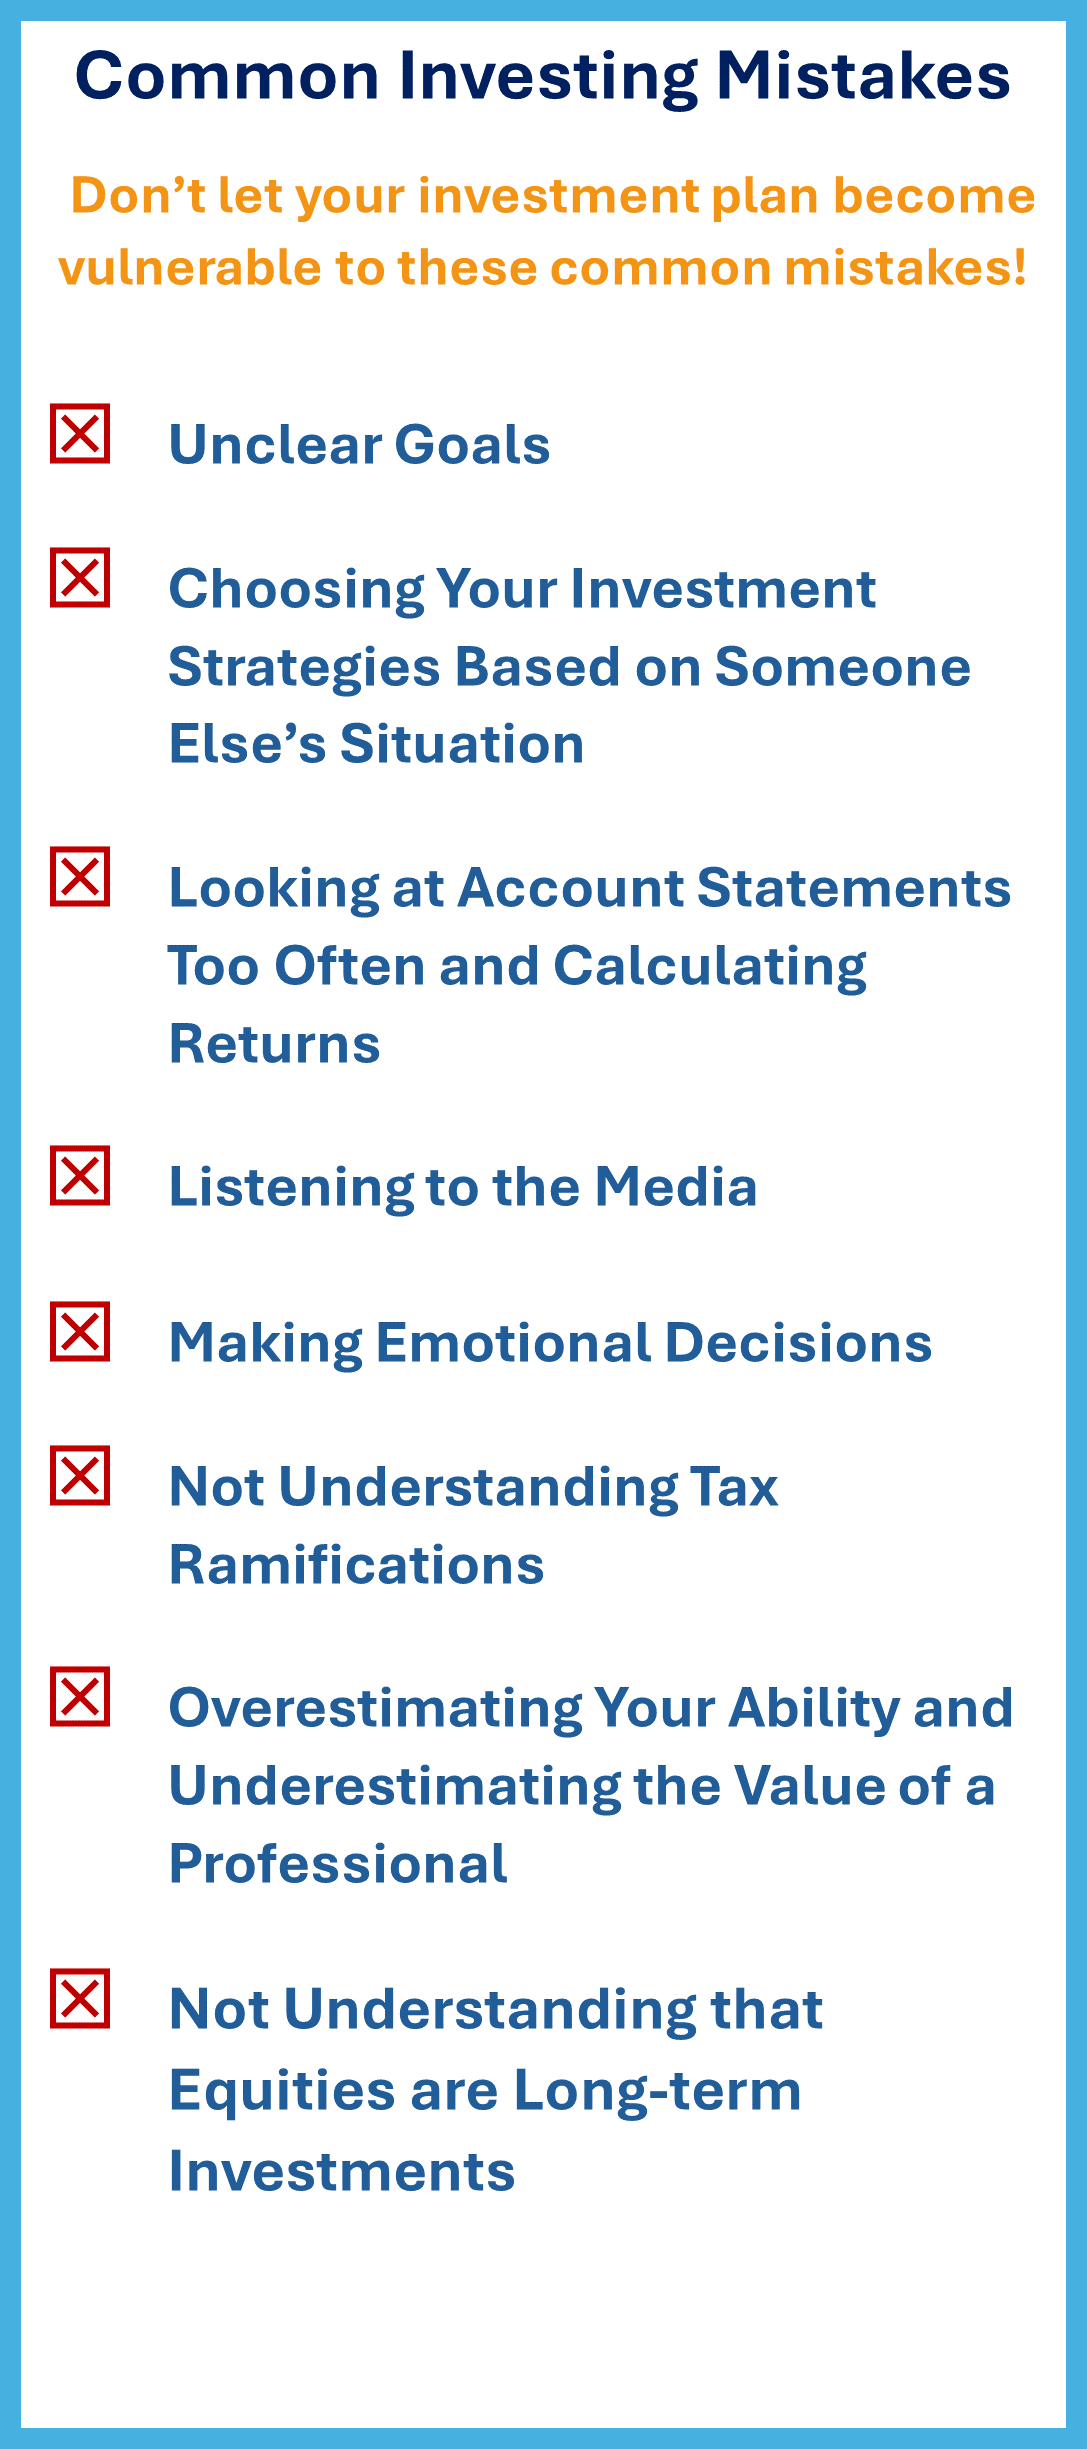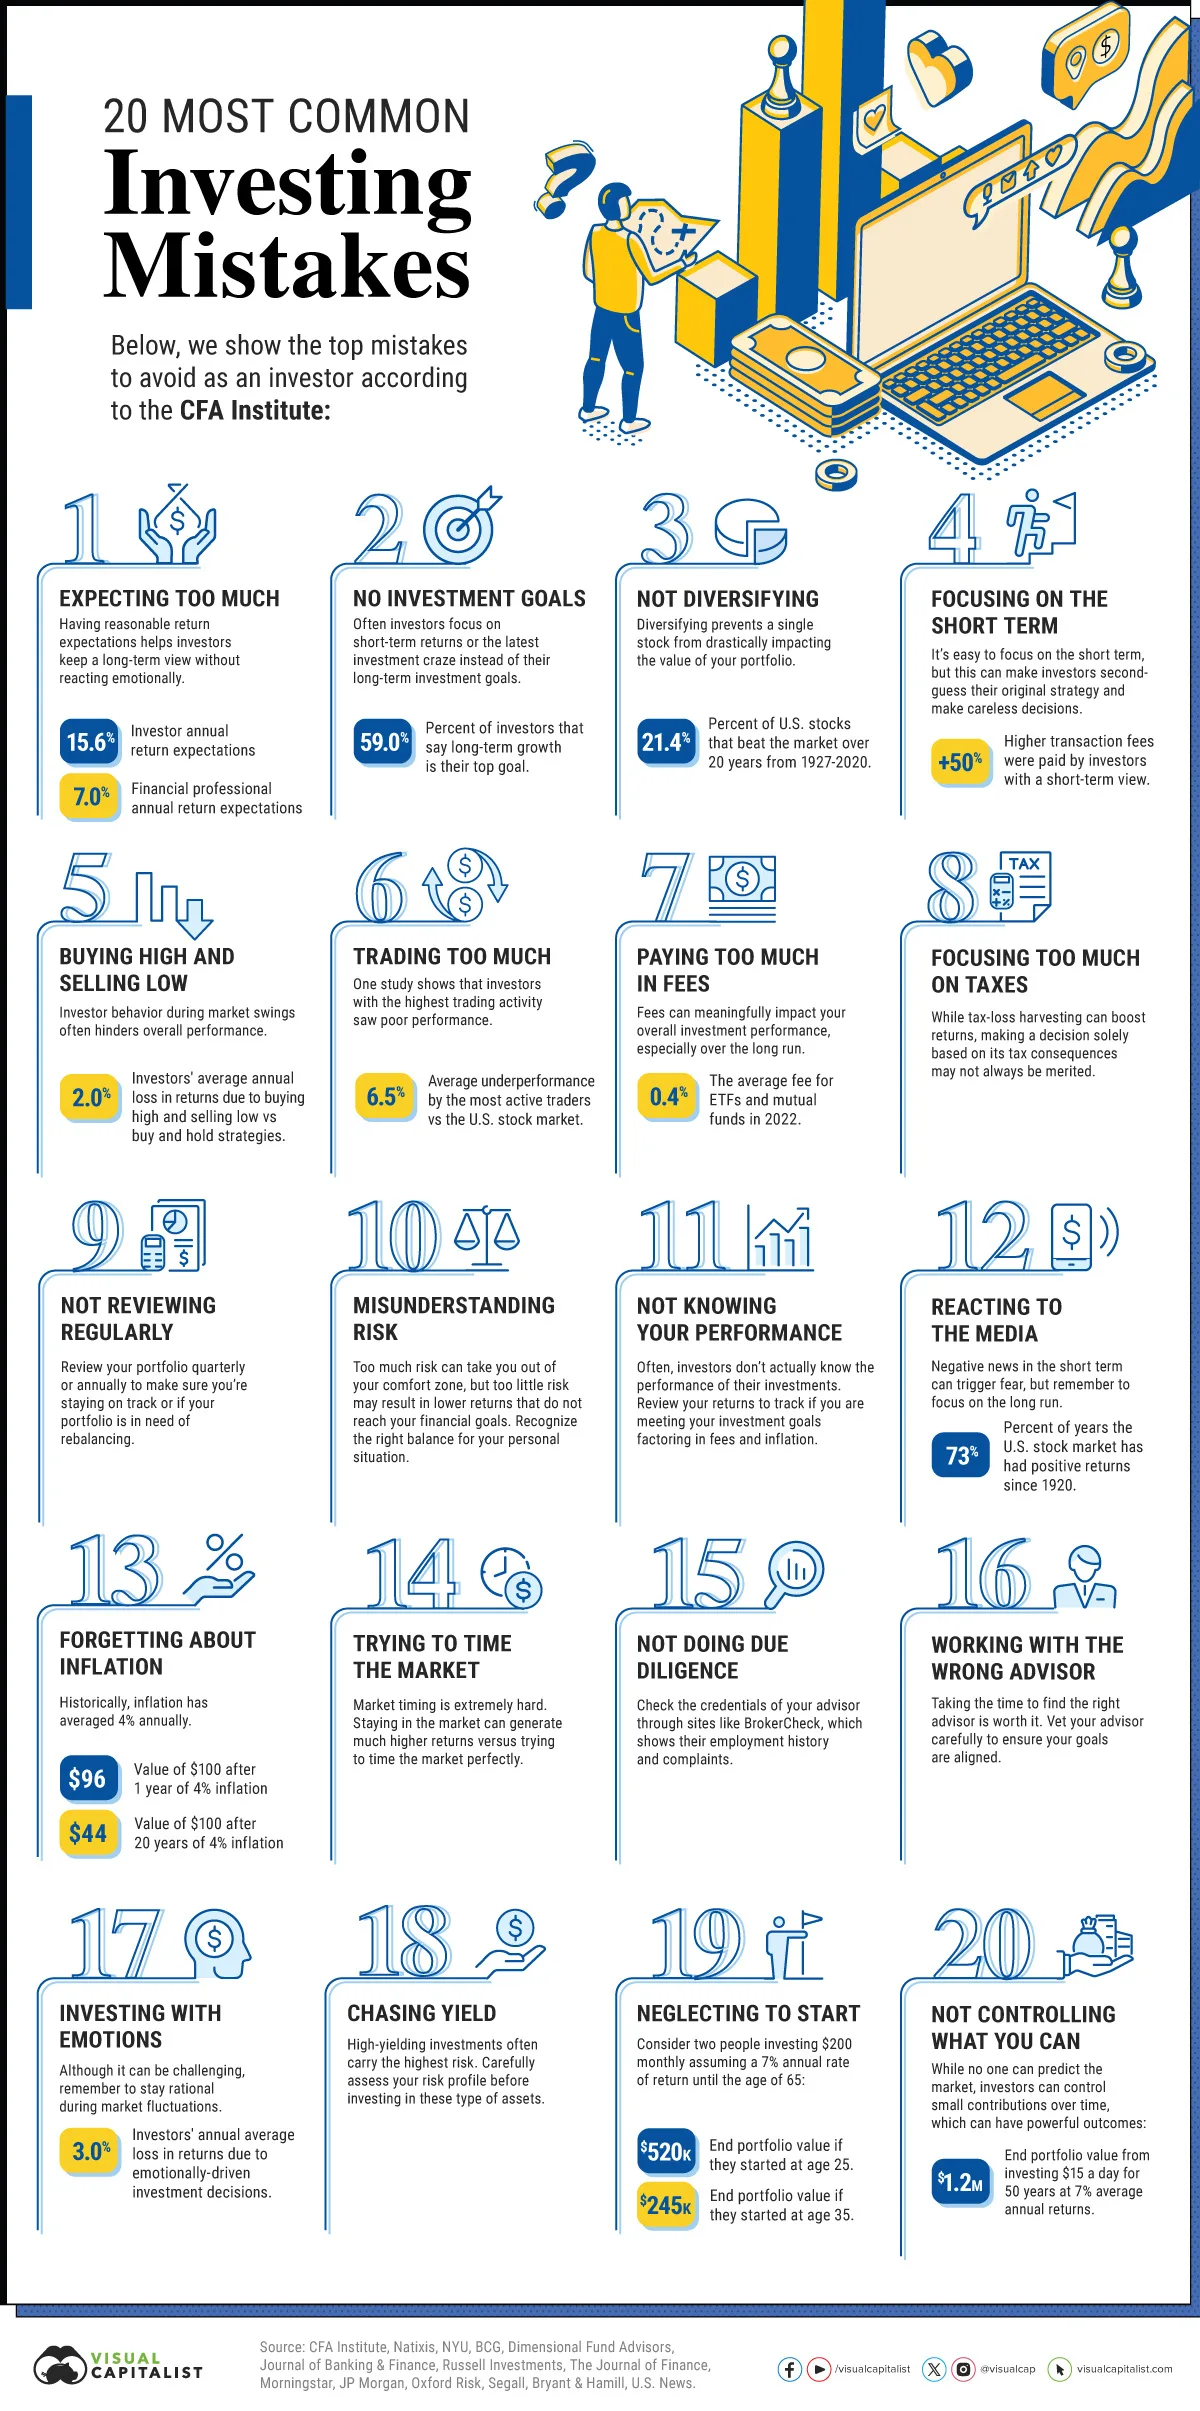
Reference Guide For Investing Common Mistakes To Avoid
I spent seven years managing small allocations before I actually learned what I was doing, and most of that time was wasted on the same handful of errors. I am not going to insult your intelligence by explaining what compounding is. You can look that up anywhere. What I am going to tell you is what actually goes wrong when you try to apply it, and how to avoid the traps. Concentration risk disguised as conviction There is a fine line between having a thesis and having a gambling habit. I watched a colleague put 40% of his portfolio into a single small-cap biotech stock because he "understood the pipeline." The drug missed its primary endpoint on a Tuesday morning. His portfolio dropped 17% in after-hours trading. He held anyway, convinced the market was wrong, until the SEC filed an inquiry six months later. That was another 23% down. He never recovered it.
The rule is simple and unsexy: no single position should exceed 8% of your total allocation unless you have explicitly decided it is a satellite bet and capped it there. If you want more exposure, you add through a sector fund or ETF, not by picking another name. This keeps you alive when your thesis is wrong, which it will be, eventually. Chasing yield without reading the prospectus High yield is not a mistake. Mistaking high yield for safety is the mistake. I saw someone buy a 9.4% corporate bond fund in 2022 because the yield looked good compared to Treasuries. The fund was loaded with BB-rated issuance from companies that had been refinancing debt for two years straight. When rates stayed higher for longer, those bonds dropped. The yield didn't matter anymore. You were holding a 9% coupon on a declining principal.
Before you buy anything that promises above-market income, check the credit ratings, the duration, and the issuer's debt service coverage ratio. If the fund holds anything rated below BBB- and you are holding it for income, you need a stomach for volatility that most retail investors do not actually have. Tax inefficiency from ignoring account placement I used to trade actively in my taxable brokerage account because it felt like the right thing to do with my "main" money. That was before I calculated the hit I was taking on short-term capital gains every year. Moving to a simpler, less-traded strategy inside an IRA and putting the taxable account toward buy-and-hold dividend stocks and municipal bonds cut my annual tax drag by roughly 1.2% of assets. Over a decade, that difference was larger than my entire initial portfolio.
Get the Full Details

The placement hierarchy I follow now is basically: tax-advantaged accounts first for high-turnover or high-yield strategies, taxable accounts second for muni bonds and qualified dividends, and cash sweep vehicles last. It is boring. It works. Panic selling at the worst moment because of a headline This is the most common mistake and also the cheapest to avoid. In March 2020, the market dropped fast. A lot of people sold because a news headline said "recession coming." They bought back three months later at 15% higher prices after the Fed intervened. I watched this happen to multiple people I know. The exact same pattern repeated in October 2022 when inflation headlines spiked fear again.
The workaround is mechanical, not philosophical. Set a rebalancing schedule and stick to it. If your target allocation is 60/40 stocks to bonds, you rebalance once per quarter regardless of what the headlines say. When stocks drop hard, your fixed contribution automatically buys more of them at lower prices. When they rally, you trim. This removes the emotional decision entirely. Ignoring fees because they seem small A 1.5% annual fee on an actively managed fund sounds minor until you run the numbers over twenty years. On a $100,000 investment growing at 7% annually, that fee costs you roughly $38,000 in foregone returns. A 0.05% index fund in the same scenario costs about $950 in fees. The difference is not trivial. It is your money, sitting on the table, every single year.
Check the expense ratio before you buy anything. If it is above 0.50% for a domestic equity fund, you should have a very strong reason for it. Management alpha does not reliably overcome fees at that level. The liquidity trap with alternative investments I got interested in a private equity fund offered through my employer's 401(k) plan because the projected internal rate of return looked attractive on the one-pager. What the summary did not emphasize enough was the ten-year lockup and the fact that you could not touch a dollar until liquidity events happened. I would have needed the money for a house down payment in year four. I could not get it.

Keep at least twelve months of expenses in a liquid account before allocating to anything illiquid. Then, if you still want PE, RE, or private credit, limit those allocations to no more than 10% of your total portfolio. Illiquidity premium is real, but only if you do not need the cash. Using leverage without stress-testing the margin call I have seen too many retail investors borrow against their portfolio at 50% LTV during a bull market and then get caught flat-footed when volatility hit. A 30% drawdown on a 2x leveraged position is not a paper loss. It is a margin call. Brokers do not give you time to wait for a recovery. They liquidate.
If you use leverage, calculate the maximum drawdown your portfolio can withstand before hitting the maintenance margin, assuming a worst-case 40% decline in the underlying asset. Most people do not do this math. I started doing it after watching a friend get liquidated during the 2022 tech selloff. He had not modeled the scenario. He assumed the market would bounce before the broker acted. It did not bounce fast enough. Mixing time horizons Putting money you need in five years into equities is a mistake that sounds reasonable until you need that money in year four and the market is down 25%. The sequence-of-returns risk at that point is devastating. You sell low, you lock in losses, and you cannot recover.
Match the asset class to the timeline. Money needed within three years belongs in T-bills, CDs, or short-term bond funds. Money needed in five to ten years can tolerate some equity exposure but should be balanced. Money needed beyond ten years is where equities belong. This is not a theory. It is basic liability matching, and it prevents the kind of forced selling that wrecks portfolios. Overfitting your strategy to past data I built a simple moving-average crossover system back in 2019 that looked great on ten years of historical data. It worked perfectly in the test. The moment I ran it live with real money in 2020, it whipsawed me through three false signals in four months and lost money on every trade. The market regime had shifted. The strategy was optimized for a different environment.

Backtests are not predictions. They are histories. Always walk-forward test on out-of-sample data and expect performance to degrade. If a strategy looks too good in the backtest, it almost certainly is overfitted. Reduce complexity. Simple systems tend to survive regime changes better than sophisticated ones. Buying because a stock is cheap A stock at 8 times earnings is not a bargain just because it is cheap. It is cheap for a reason. I picked up a consumer staples name in 2021 that looked undervalued compared to peers. The P/E was half the industry average. The reason was declining market share, a failing distribution channel, and management that was quietly restructuring. The stock went another 40% lower before it stabilized. The valuation was the trap, not the opportunity.
Relative valuation without understanding the business dynamics is just math without context. Always check why the multiple is compressed before you buy. Usually, it is not a mystery. The behavior gap This is the largest mistake most investors make, and it is not about any single security or fund. It is about the difference between what an investment earns and what the investor actually earns. According to SPIVA data, the average active fund underperforms its benchmark by about 1% annually after fees. The average investor underperforms the fund by another 1-2% because they buy high and sell low. The behavior gap eats both numbers.
The fix is unglamorous: automate contributions, automate rebalancing, and remove yourself from the decision loop. I set up automatic monthly investments into a target-date fund in 2018 and have not looked at it since. My returns are exactly what the fund returns. Nothing more, nothing less. And that has been plenty.