The Reality of Refinancing a Second Mortgage
Refinancing a second mortgage is one of those things most homeowners think is simple until they're three weeks into it and realize the process is completely different from refinancing a first mortgage. The mechanics are similar on the surface, but the paperwork, lender appetite, and timing issues make it a distinct beast entirely. Here is what actually happens when you go through it. First, let me be clear about what a second mortgage refinance looks like. You have an existing home equity loan or HELOC on top of your primary mortgage, and you are replacing that second lien with a new one, usually at a better rate or different term. Sometimes people combine their first and second mortgages into a single cash-out refinance instead. Both are common. The combined refi route gets talked up more because it eliminates the second lien entirely, but it is not always the right move.
How Refinance 2nd Mortgage Actually Works
The process starts the same way any mortgage refinance does. You check your credit score, pull your current mortgage statements, and figure out your loan-to-value ratio. That last number matters more here than for a first mortgage refinance because the second lien position changes the calculus. If your total debt against the home exceeds 80 percent, you are likely dealing with private mortgage insurance or a higher rate to begin with. That changes your options significantly. From there, you shop lenders, but here is where it gets strange. Not every lender touches second mortgage refinances. The big national banks often push these aside in favor of first-lien work because the processing is heavier and the margins are thinner. Credit unions and regional lenders tend to be more willing to take them on. I have found that calling around to at least four or five lenders before submitting an application saves a lot of time, because several will simply decline to work the file. Once you submit, the appraisal comes next. For a second mortgage refinance, some lenders will accept a desktop or automated valuation model instead of a full appraisal if the numbers support it. Others insist on a full interior appraisal because the risk profile is different. This is not a minor detail. A full appraisal can add five to seven business days to your timeline and cost you $400 to $600 out of pocket at closing.
The underwriting phase is where most people hit friction. Because your second mortgage is a subordinate lien, the underwriter has to verify that the first mortgage holder will agree to stay in first position. That means sending a subordination request to your primary lender, which can take anywhere from three business days to three weeks depending on who holds your first mortgage. I once had a file sit in limbo for eleven days because the first mortgage was held by a small community bank that took a business day to respond to each follow-up email. The workaround was having my borrower call the bank's loss mitigation department directly and ask for expedited subordination due to a refinance closing deadline. That got a response within forty-eight hours instead of thirteen days. It is not a guaranteed fix, but it is something most people do not know to try. After subordination clears, the rest of the process mirrors a standard refinance. Title search, closing documents, funding, and recording. Your new second mortgage gets recorded, and your old one is paid off and released. Total timeline if everything goes smoothly is roughly thirty to forty-five days. If your first mortgage servicer drags on or the appraisal comes in low, add another two to three weeks. There are some counter-intuitive things about this process that most guides miss. One is that your first mortgage payment does not change during a second mortgage refinance, but it will get your attention more. The second lien refinance triggers a full credit pull and a debt-to-income recalculation. If your DTI is already close to the 43 percent threshold, adding the new second mortgage payment on top of the first can push you over even if you paid off the old second mortgage. This trips up a surprising number of people.
Get the Full Details

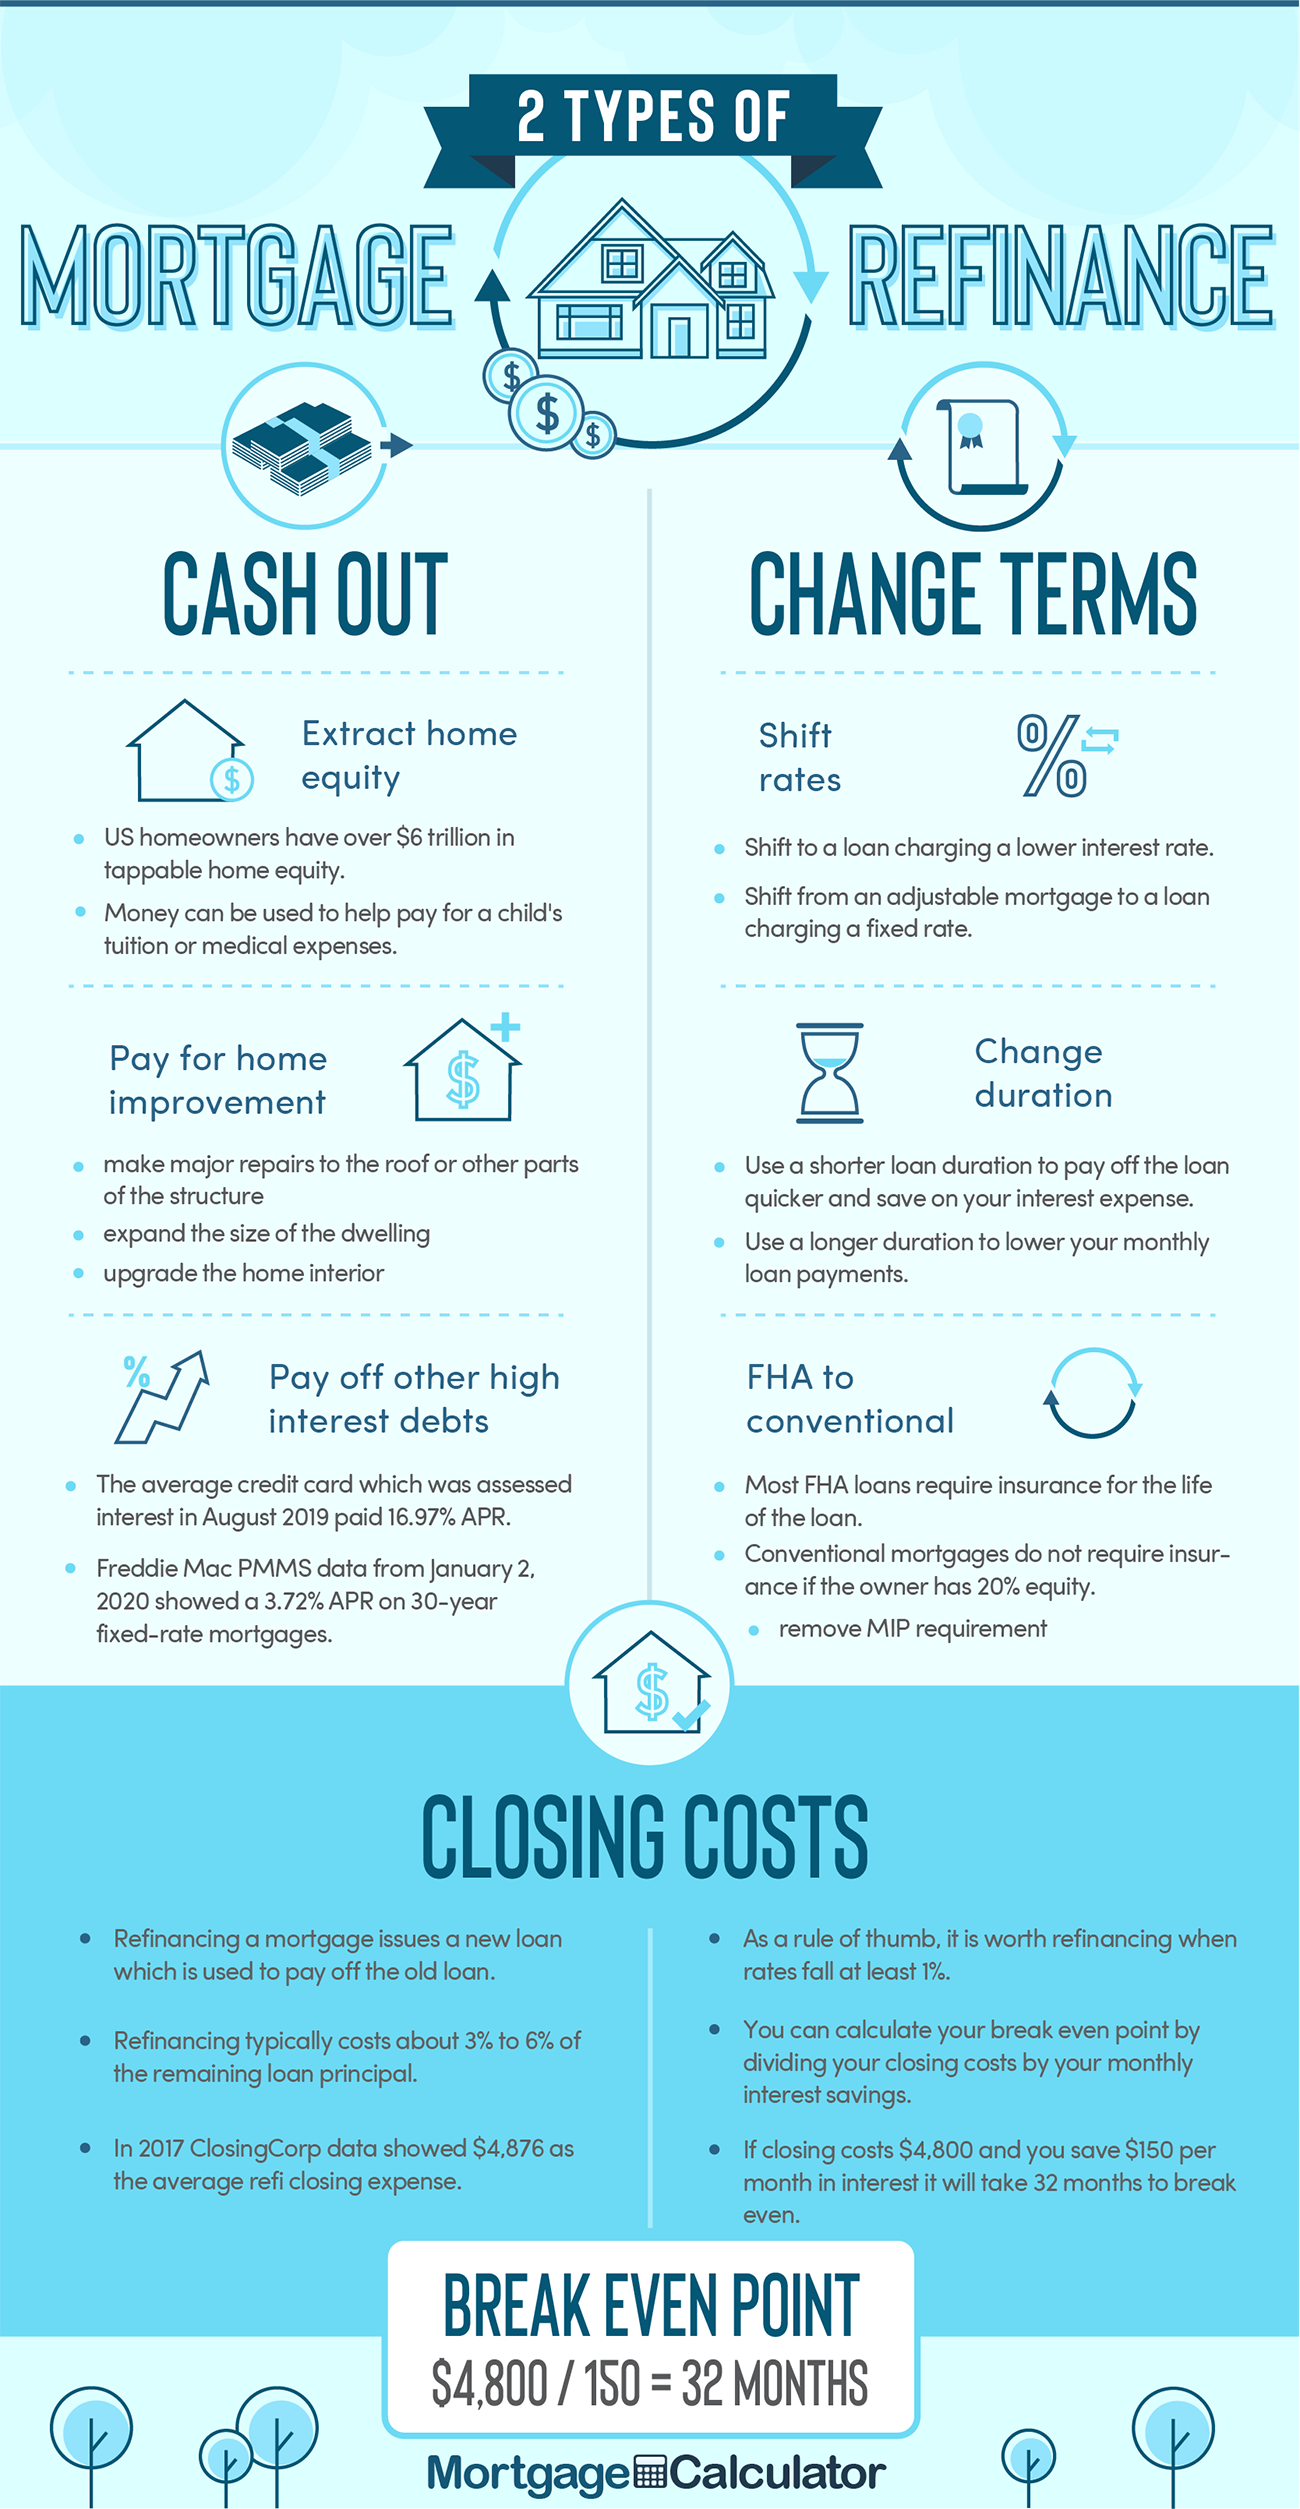
Another thing that surprises borrowers is how much the current interest rate environment affects available programs. A year ago, cash-out refinance rates on second liens were competitive with first mortgages in many cases. Now, secondary lien rates typically run 0.5 to 1.25 percentage points above first mortgage rates because the collateral risk is higher. That gap matters when you are calculating whether the refinance actually saves you money. Here is the blunt part that nobody likes to hear: a second mortgage refinance does not always make financial sense. I have seen people refinance their home equity loan from 9 percent to 7 percent and spend $3,500 in closing costs to save $120 a month. That is a twenty-nine month break-even, and if they move or sell before then, they have lost money. Run the numbers against your actual timeline, not your hopes. There is also the question of whether combining your first and second mortgages into one loan makes more sense. This is what I mentioned earlier, and it deserves its own consideration. A combined refinance simplifies your payments and can lower your rate by eliminating the secondary lien premium. But it also means you are putting all your debt back into a first-lien position, which increases your risk if you fall behind. It also typically requires a larger cash-out amount to pay off both loans, which pushes your LTV higher. If you are at 80 percent combined LTV, you are looking at PMI again. That changes the math entirely.
If you decide to proceed, keep a few practical things in mind. Get your first mortgage servicer contact information before you start. Know your exact payoff amount for the second mortgage. Do not apply for new credit during the process. And make sure you understand whether your new second mortgage is a fixed rate or adjustable, because some lenders push ARMs on second liens since they carry less risk for them. The bottom line is that refinancing a second mortgage is doable but requires more preparation than a first mortgage refinance. The subordination step alone adds unpredictability to your timeline. The rate difference between first and second lien products means you need to run the numbers carefully. And not every lender will touch it, so shopping early matters. If your situation is straightforward with a strong credit profile and healthy equity, you should be able to close in a month and a half with minimal headaches. If you are carrying a high balance with a borderline credit score, expect delays and consider whether paying down the second mortgage is a better use of your money than refinancing it.