Why Second Mortgages Are Different From What You Think
Refinancing a second mortgage isn't the same as refinancing your primary home loan, and most online tools don't tell you that upfront. I've seen people run their numbers through generic calculators, get excited about the monthly savings, and then hit a wall when the lender's actual amortization schedule came back completely different. The math looks clean on paper, but the reality of how second lien positions work throws off a lot of the assumptions built into standard calculators.
How the Refinance 2nd Mortgage Calculator Actually Works
At its core, a Refinance 2nd Mortgage Calculator takes your current second mortgage balance, interest rate, remaining term, and the new rate you're shopping for, then compares monthly payments and total interest across both scenarios. Some calculators also factor in closing costs, prepayment penalties, and the lien position impact on your combined loan-to-value ratio. It seems straightforward, but the devil is in the details of what gets included and what gets glossed over.The key inputs you need are your existing second mortgage balance, the original term length, how many months are left, the current interest rate, and the new rate you're being offered. You'll also need your property's current appraised value and the balance on your first mortgage, because lenders care about the combined LTV when approving a refinance on a second lien. Without those numbers, the calculator is just guessing, and the guess won't help you much.
Where Most People Mess This Up
I spent years watching borrowers ignore the prepayment penalty clause in their second mortgage documents. One of my clients had a 5/1 ARM second mortgage with a 4% yield maintenance fee if paid off before year seven. She was sitting in year four when she saw some "amazing" refinance rates online. The calculator showed her saving nearly $300 a month. The yield maintenance fee ate three years of those savings and then some. She ended up paying more by refinancing than staying with the original loan. This is exactly the kind of edge case that no free calculator flags without you feeding it the right data.Another thing nobody warns you about is the recasting versus refinancing distinction. Some lenders let you recast a second mortgage instead of fully refinancing it. You pay a small fee, provide proof of increased income or a larger down payment, and they reamortize the remaining balance at your existing rate over a shorter term. The monthly payment drops, but you avoid the closing costs and the full credit check that comes with a refinance. A standard Refinance 2nd Mortgage Calculator won't even show this option because it's not actually a refinance. You have to know to ask for it.
Pitfalls You Should Know About Before You Run the Numbers
First, many calculators assume a standard amortizing second mortgage, but a significant number of second liens are interest-only for the initial period. If yours is interest-only, the monthly payment stays flat until the amortization kicks in, and refinancing during that window can reset your clock entirely. You might trade a lower rate for a longer amortization schedule and end up paying more over the life of the loan without realizing it.Get the Full Details
Second, the tax implications are often miscalculated. Interest on a second mortgage is only deductible if the proceeds were used to buy, build, or substantially improve the home that secures the loan. If you took a home equity second mortgage to consolidate debt or pay off credit cards, that interest isn't deductible under current tax law. A calculator that shows you interest savings without noting this might make a refinanced second mortgage look more attractive than it actually is on an after-tax basis. You should be running these numbers with a tax professional, not a spreadsheet. Third, and this one is genuinely overlooked: the impact on your first mortgage insurance. If you have PMI on your primary mortgage and refinancing the second changes your total debt structure in certain ways, some lenders require you to recalculate PMI eligibility. Your first mortgage's private mortgage insurance premium could go up even if your combined loan balance goes down. I worked with a borrower who refinanced her second to take advantage of lower rates, saved $150 a month on the second lien, and then got hit with a $60 a month increase in PMI on her first. The net savings disappeared quickly.
What to Do If You're Actually Considering Refinancing a Second Mortgage
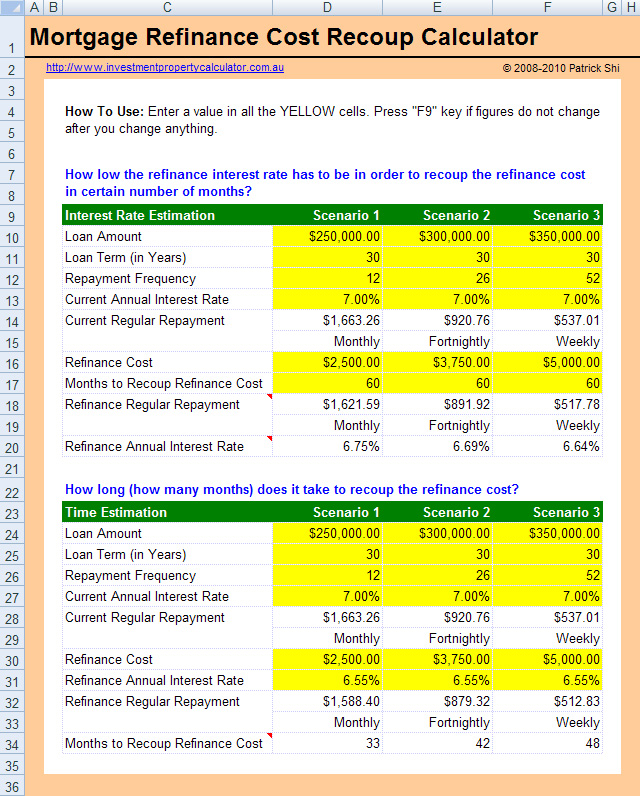
Start by pulling your original second mortgage documents and finding the prepayment penalty section, the origination date, and whether it's a fixed or adjustable rate. Check if there's a rebate of unearned interest if you pay it off early. Then run the numbers through a calculator, but manually add in the prepayment penalty as a one-time cost and the closing costs that typically run between 2% and 5% of the loan amount. Don't rely on a calculator that only shows the monthly payment comparison. I keep a simple spreadsheet for these calculations because most online calculators don't let you layer in all the variables simultaneously. You enter the current balance, the old rate, the new rate, the remaining months, the prepayment penalty amount, the closing costs, and then it gives you the breakeven point in months and the total cost difference over the remaining life of the loan. This takes about ten minutes to set up and saves you from making a decision based on incomplete information. If your second mortgage has less than three years remaining, refinancing rarely makes sense unless the rate differential is enormous. The upfront costs usually outweigh the monthly savings before you get anywhere near the break-even point. I've seen this happen multiple times where people kept refinancing second mortgages without realizing the clock was ticking down on the savings window. After year three, the remaining term is often too short to recover the closing costs, even at a significantly lower rate.
The Hard Truth About When This Makes Sense
Refinancing a second mortgage works when you have at least five to seven years remaining on the original term, the rate drop is substantial enough to overcome closing costs within three years, and you aren't triggering any prepayment penalties that would erase the benefit. It also helps if you're in a lower tax bracket now than when you took out the second mortgage, because the after-tax cost of the new loan will be lower than the calculator's pretax numbers suggest. None of this is obvious from a simple payment comparison tool, which is why you should treat any online calculator as a starting point, not a decision-making instrument. The real answer to whether you should refinance your second mortgage depends on your specific loan terms, your remaining time horizon, and the actual costs involved. A calculator gives you a rough idea. It doesn't give you a recommendation, and no tool on the internet will do that properly either. You need your documents, your numbers, and ideally someone who can review the fine print before you commit to anything.