How to Actually Use a Refinance Break Even Calculator
A break even calculator tells you how long it will take for your monthly savings from refinancing to cover the closing costs. That's it. Nothing dramatic about it. Most people skip this step and just refinance because the rate is lower, which often works out fine, but there are cases where it doesn't and you end up paying more over the life of the loan. The core math is straightforward. You take your total closing costs and divide by your monthly savings. The result is the number of months until you recover what you spent. For example, if closing costs are $4,200 and your new payment is $180 cheaper per month, the break even point is 23.3 months. After month 24, you're ahead. But the real work is in the inputs, not the division. A lot of people plug in their estimated monthly payment from the new loan and compare it to their current payment, then call it done. That's where things get messy. Your current payment might include escrow for taxes and insurance, which won't change when you refinance. If you don't isolate the principal and interest portion of both payments, your savings figure is wrong and your break even date is meaningless. I've seen people get told they'd break even in 14 months when the real number was closer to 31 because someone hadn't separated the escrow component properly.
The Input Problem That Nobody Talks About
Closing costs are the hardest part to pin down accurately. Lenders give you a Loan Estimate that shows origination fees, appraisal, title insurance, recording fees, and prepaid items like property taxes and homeowner's insurance. Some of those prepaids are just advancing money you'd owe anyway, so they shouldn't count as true refinancing costs. When I'm running these calculations, I only include the actual fees: origination, underwriting, appraisal, title search, title insurance, recording, and any points bought down. The escrow advance for taxes is not a cost. It's a deposit. Leave it out. I ran into a specific issue last year with a client who had an ARM that was about to reset. Her break even calculation came out to 18 months on paper, but the clock was already ticking. She'd been in the loan for four years and the adjustment was coming in nine months. If she waited to refinance until after the reset, the new higher payment would destroy her cash flow before she could recover anything. The workaround was to refinance immediately even though the break even window was tight, because staying put meant a $340 monthly jump that left zero room for error. The calculator said 18 months, which sounded long, but relative to her remaining time in the property, it was the only move that made sense.
How to Run the Calculation Yourself
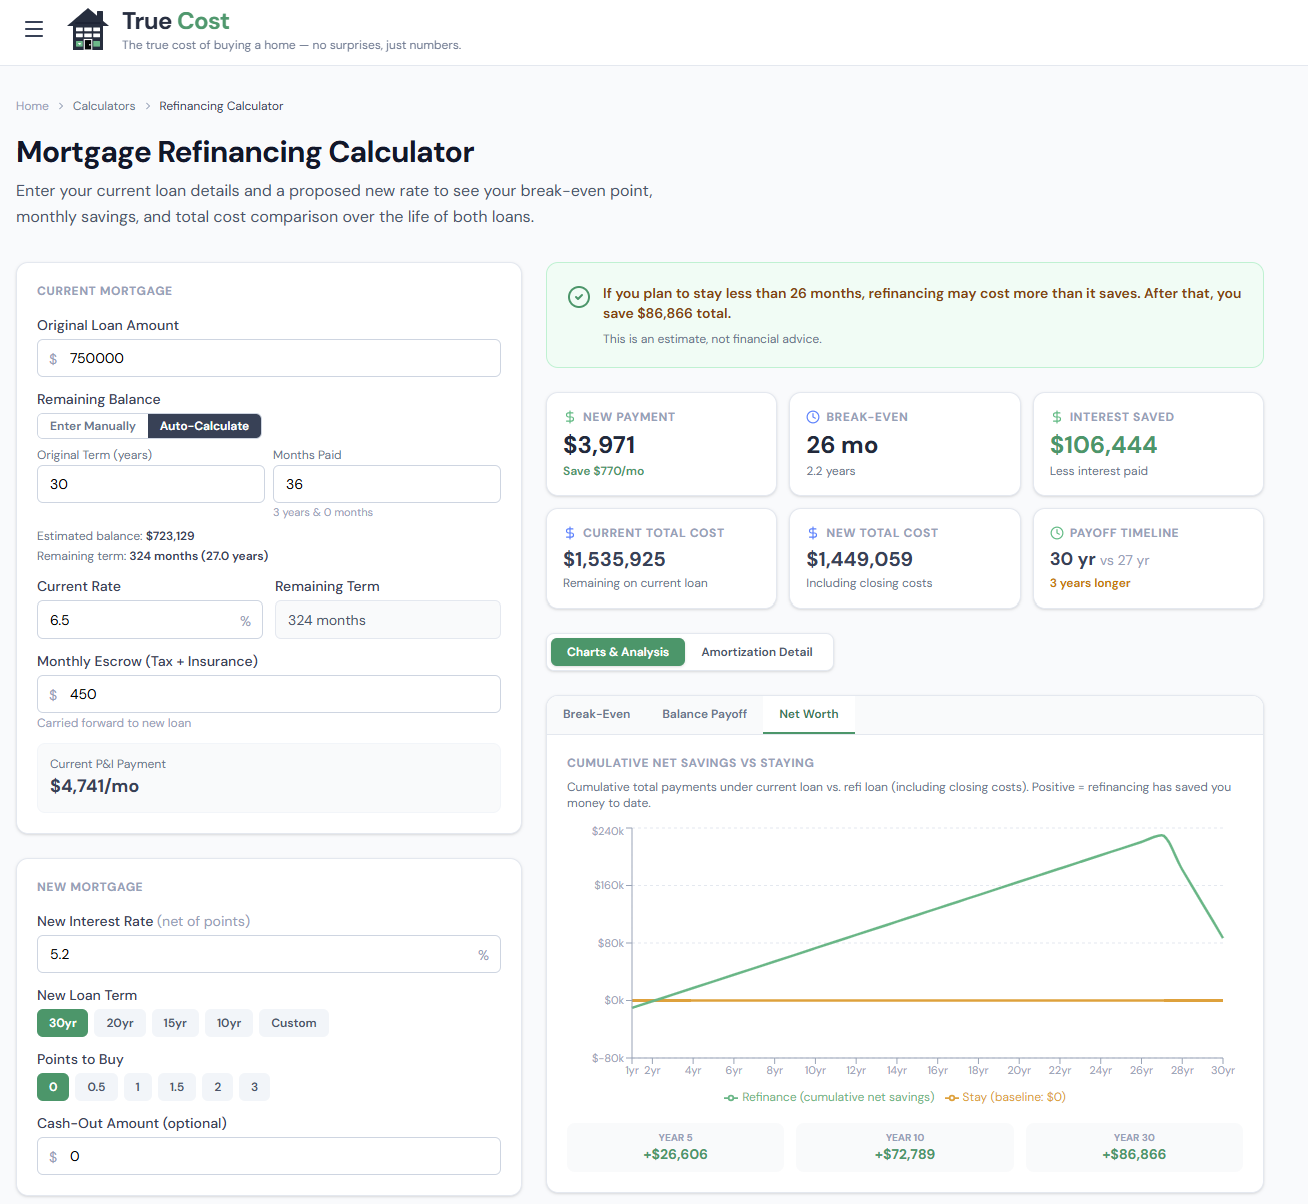
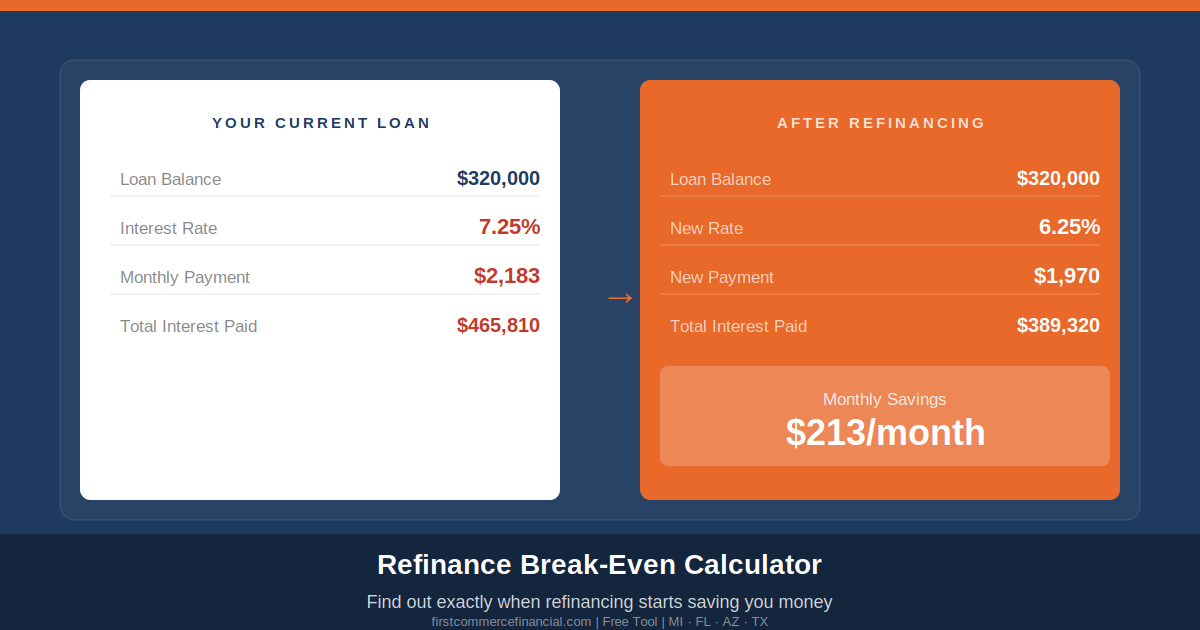
Most lenders will do this for you if you ask, but having a Refinance Break Even Calculator tool you control is useful because you can stress-test different scenarios. Here's the practical way to do it. First, get your current loan details. What's the remaining balance? What's your current interest rate? What's your current monthly P&I payment? Pull this from your most recent statement or log into your servicer's portal. Don't estimate. If you're off by even a few hundred dollars on the balance, your payment calculations drift. Next, get the new loan terms. This comes from the Loan Estimate your lender sends. Take the new interest rate, the new loan amount, and the remaining term. Calculate the new monthly P&I payment using any standard amortization formula or online calculator. Make sure you're using the correct remaining term. A lot of people refinance a 30-year loan and assume the new payment is based on 30 years, when really they should be comparing it to whatever years are left on the current loan or what they actually need.
Get the Full Details
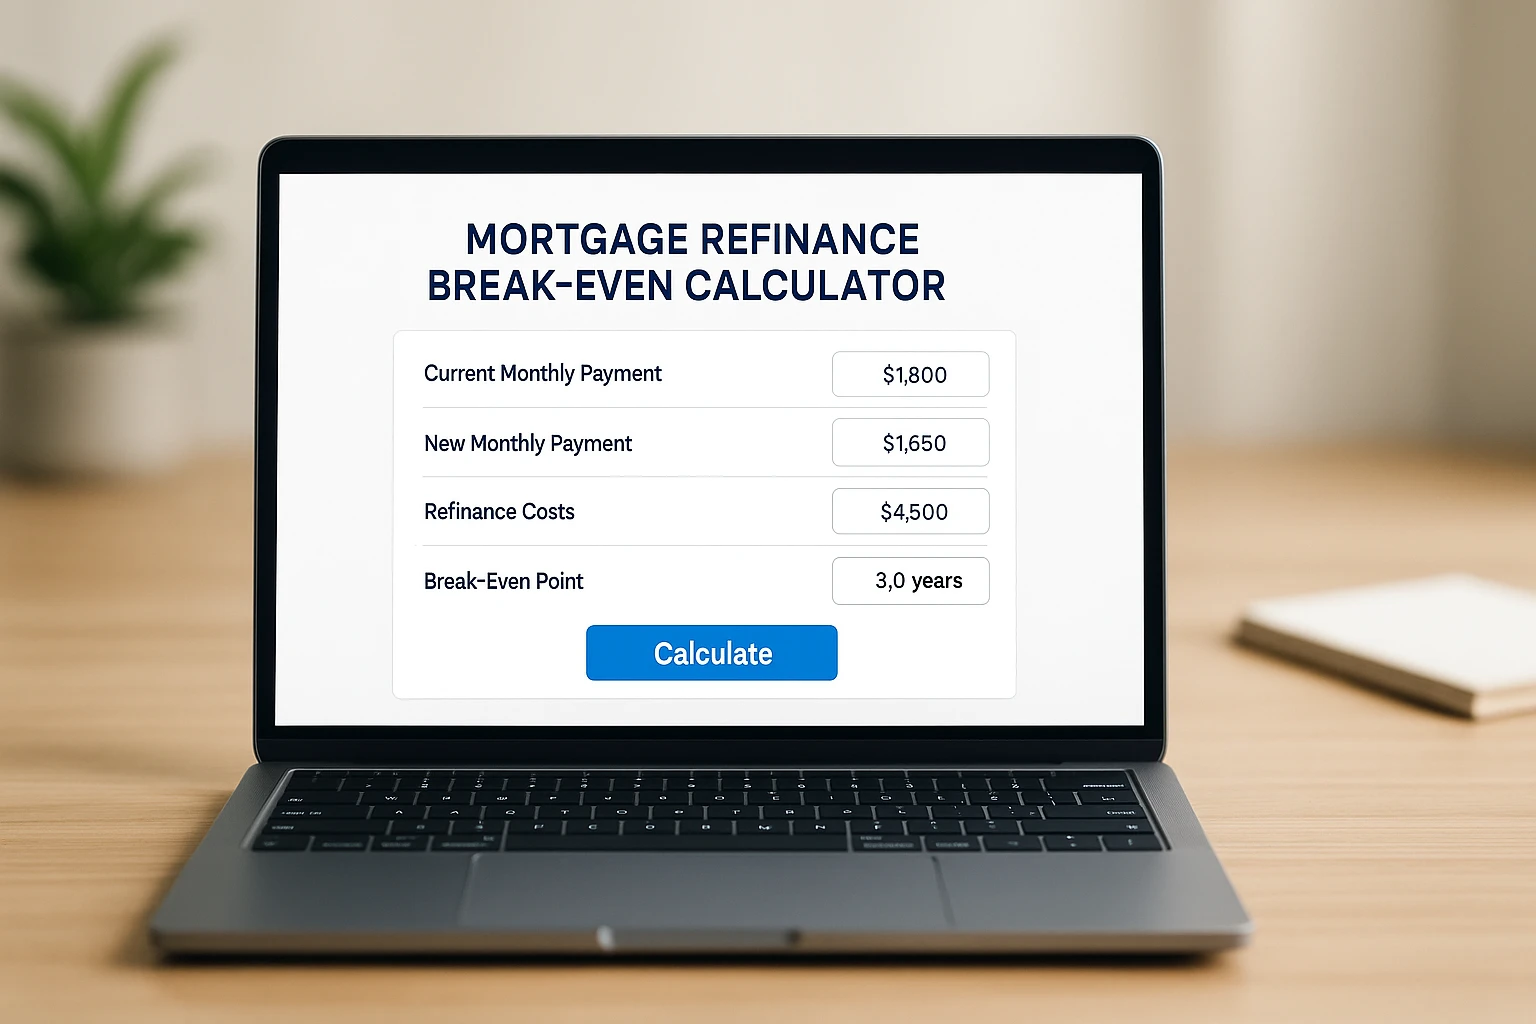
Then add up your qualifying closing costs. Origination at 1% on a $300,000 loan is $3,000. Appraisal runs about $500 to $750 in most markets. Title insurance varies by state but expect $1,000 to $2,000. Recording fees are usually under $200. Points, if you buy any, are 1% of the loan amount per point. Total this up. Use the actual numbers from your Loan Estimate, not the lender's verbal guess. Subtract the new P&I from the old P&I to get your monthly savings. Divide total closing costs by that monthly savings. The result is your break even in months. Round up to the next whole month because you don't get partial months of savings. That process takes about 20 minutes if you have all your documents open. Without them, an hour or more.
What Beginners Miss About Break Even Analysis
The biggest blind spot is ignoring how long you plan to stay in the home. Break even means nothing if you move in 14 months and the calculation showed 23. If you're confident you'll stay longer than the break even point, refinancing makes sense. If your timeline is shorter, you're just spending money on closing costs with no recovery. I had a situation where a borrower was offered a rate drop of 0.75% that looked great on paper, but the break even was 28 months and he was planning to sell in 18. He walked away and saved $3,800 in closing costs instead. The second miss is not factoring in rate buydowns. Sometimes a lender will offer a lower rate if you pay discount points upfront. That lowers your monthly payment further but increases your closing costs. The break even calculation handles this naturally if you include the points in your cost total, but people often leave points out and then wonder why their actual savings don't match the projection. One point on a $300,000 loan is $3,000. That's a significant addition to your cost basis. There's also the issue of cash-out refinancing. If you're pulling equity out, your loan balance increases, your payment goes up, and the monthly savings figure changes entirely. The break even math still applies, but you need to make sure you're comparing apples to apples. The savings come from the rate difference and potentially the term restructuring, not from the cash you took out. That cash is a separate financial decision.
When the Calculator Lies to You
Break even analysis assumes your current payment stays exactly the same. That's not always true. If you have an adjustable-rate mortgage, your current payment could change next year. A ARM that's currently at 5.5% and resets to 7% next year changes the entire comparison. Your "savings" from refinancing might actually be a loss if the ARM resets upward. Always check whether your current loan is fixed or adjustable before running the numbers. The calculator doesn't know your loan type. You do. Another scenario where it fails is when your current loan has a prepayment penalty. Some loans charge a penalty if you pay off the balance early, typically a percentage of the remaining principal or a certain number of months of interest. That penalty is an additional cost that needs to be included in your closing cost total. If you skip it, your break even is artificially short. I've seen a $2,100 prepayment penalty completely flip a refinancing decision from viable to not worth it. Check your note and truth in lending disclosure for that clause before you do anything.
Practical Thresholds to Keep in Mind
A rate drop of less than 0.5% almost never justifies refinancing unless your current rate is absurdly high or you're doing a cash-out. The closing costs outweigh the monthly benefit. A drop of 0.5% to 1% is the typical window where break even makes sense if you're staying in the home for at least two years. Above 1% is usually a clear yes, assuming your stay timeline aligns. If your break even point is under 12 months, go ahead without much deliberation. Between 12 and 36 months, it depends on your confidence in staying. Over 36 months, you should probably reconsider whether refinancing is the right move at all unless there's something else going on, like switching from an ARM to a fixed rate for stability. The tool itself is simple. The context around it is what determines whether it matters. Run the numbers, check your actual costs, verify your timeline, and then decide.