How Refinance Calculators Actually Work (And Where They Lie to You)
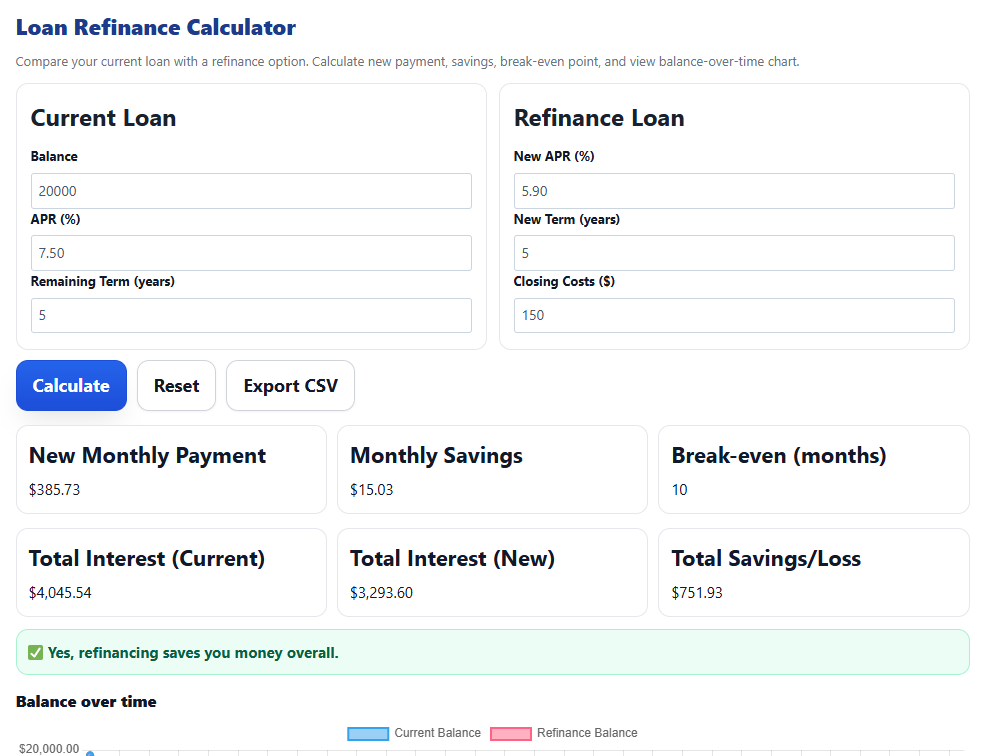
I built and maintained loan calculators for a living for about eight years before moving on. The short version is that a Refinance Calculator Calculator takes your current loan details, plugs them into an amortization formula, and tells you whether swapping loans saves you money over time. The long version is considerably more annoying. The core formula most people see is the standard annuity calculation: Monthly payment equals the principal multiplied by the monthly rate divided by one minus the monthly rate, all raised to the negative power of the number of months. It's correct for a fixed-rate loan with no fees. The moment you introduce closing costs, points, or an adjustable rate, the math gets messier and the typical calculator on a random website starts hand-waving. Here is where I ran into a problem that still comes up regularly. A user submitted their refinance data and the calculator showed a clear monthly savings of about $220. Break-even was 14 months. Everything looked fine until I realized the calculator wasn't accounting for the existing loan's prepayment penalty. The borrower's current mortgage had a 3% slip clause for the first seven years. That penalty alone was $12,000 and wiped out any realistic chance of the refinance making sense. The generic tool didn't have a field for it. The workaround was to manually add the penalty amount to the closing costs input and rerun the comparison. Most calculators never even ask about penalties.
Using a Refinance Calculator Calculator Step by Step
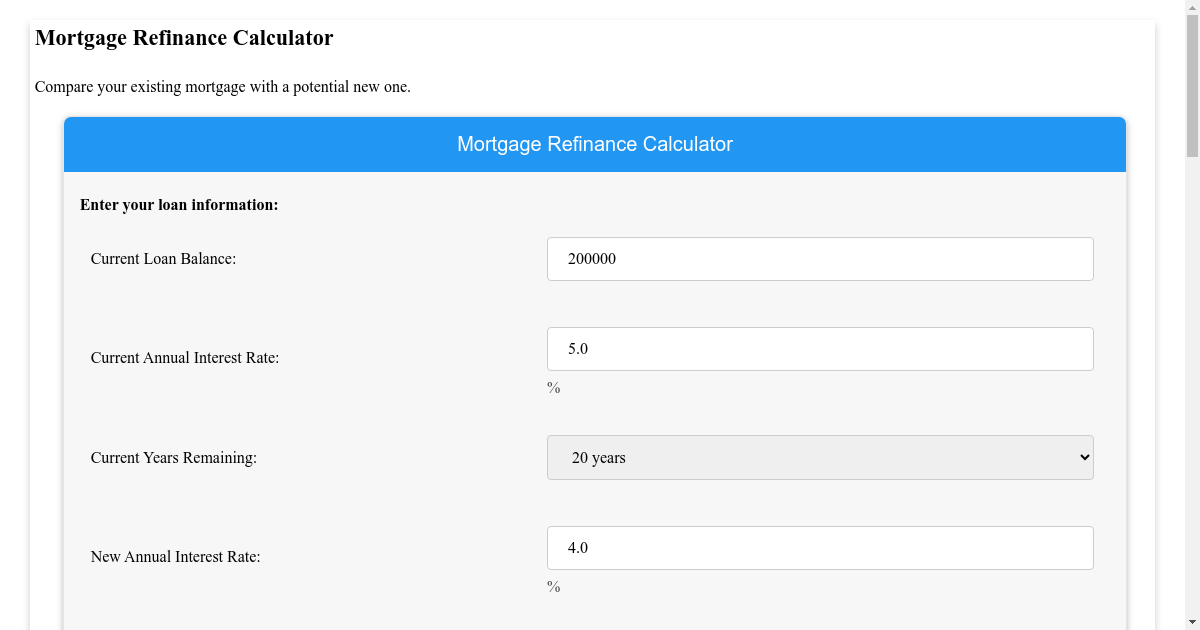
You need six pieces of information before opening the tool: your current loan balance, your current interest rate, your remaining term in months, the new loan's interest rate, the new loan's term, and the total closing costs including origination fees, appraisal, title insurance, and any discount points. If you skip closing costs, the calculator is basically just showing you fantasy numbers. Enter each value exactly as it appears on your latest statement. Do not round your current balance down to the nearest thousand just because it looks cleaner. That small rounding can shift the monthly payment by a few dollars and move your break-even point by a month or two, which matters if you are borderline on the decision. Run the calculation. Compare the new monthly payment to your old one. Then divide the total closing costs by the monthly savings to get your break-even period in months. If you plan to sell before that number, the refinance loses its justification on pure cash-flow grounds, even if the rate drop feels psychologically appealing.
Counter-Intuitive Things Most People Miss
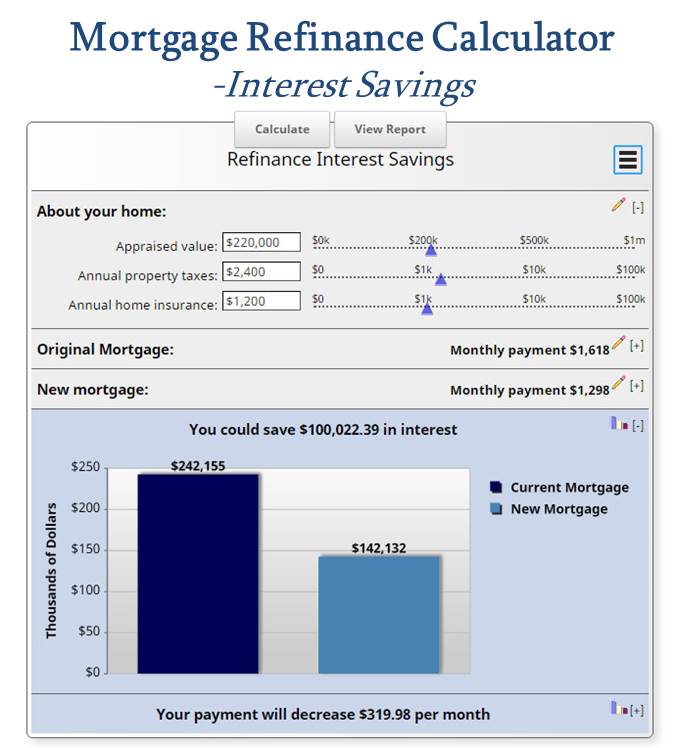
First, a lower rate does not always mean lower total cost over the life of the loan. If you take a 30-year loan to replace a 15-year loan, you will pay dramatically more in total interest even though your monthly payment drops. The calculator will show you the monthly difference but it won't highlight the long-term trap unless you explicitly compare total interest paid across both loans. I have seen borrowers walk away convinced they saved money when they actually doubled their interest expense over the life of the loan. Second, discount points behave differently than most homeowners expect. Paying one point upfront lowers your rate by roughly 0.125 to 0.25 percent depending on the lender and market conditions. The math says points make sense only if you stay in the home long enough for the monthly savings to exceed the upfront cost. But the break-even calculation changes if your current loan already has prepayment penalties or if property taxes and insurance are bundled into escrow and those escrow adjustments shift after refinancing. Those hidden escrow changes can eat into your apparent monthly savings by $30 to $80 without you noticing until the first payment cycle.
Get the Full Details
When the Calculator Completely Fails You
The biggest limitation is that every online refinance tool assumes a static scenario. It cannot model what happens if rates reset on an ARM, what happens if you miss a payment and get penalized, or what happens if your employer changes your income and you qualify differently under a new debt-to-income calculation. It also cannot factor in your specific tax situation. Mortgage interest deductions matter less now after the 2017 tax law changes, and the standard deduction is high enough that many borrowers no longer benefit from itemizing. A calculator will treat the rate and payment as the only variables, which means the real net savings is almost always lower than what the tool shows. If you have an adjustable-rate mortgage, an interest-only loan, or a portfolio loan with unusual terms, skip the free online tool and use a spreadsheet or a licensed loan officer who can build a custom projection. The free tools work fine for straightforward conventional fixed-rate refinances. They break down fast once the loan structure gets nonstandard.
What to Do After the Calculator Shows Results
Don't stop at the break-even number. Pull your current loan disclosure documents and verify the balance, rate, and remaining term yourself. Loan servicers sometimes report outdated balances that make your refinance look more attractive than it actually is. Get a Loan Estimate from at least two lenders and compare the fees line by line. Originations fees can vary by 0.25 to 0.5 percent between lenders on the same loan amount, which is thousands of dollars and enough to flip a borderline refinance into a clear loser. If the calculator shows a break-even under 24 months and your closing costs are under 3 percent of the loan balance, you are generally in safe territory. If the break-even is over 60 months, you should probably question whether you intend to stay in the property that long. The math becomes much weaker the further out you push the timeline. There is no single perfect tool for this decision. The calculator is a starting point, not a verdict. Run the numbers, then verify them against your actual paperwork and your actual plans for the next five to ten years.