What This Tool Actually Does
A Refinance Equity Loan Calculator is just a specialized spreadsheet or web form that takes your current loan balance, remaining term, interest rate, and the new loan terms you're considering, then projects whether refinancing saves you money over time. Most people think it's about monthly payments. It's really about total cost across the life of the loan, and how closing costs eat into any savings. I've built and used more of these than I can count, and the frustrating part is that almost nobody reads the output correctly. They look at the lower monthly payment and assume they've won. Then they forget about the appraisal fee, the origination charge, and the fact that resetting the clock on a 25-year balance can wipe out three years of equity gains.
Using a Refinance Equity Loan Calculator Step by Step
First, pull your current payoff statement. Not your last monthly statement — the payoff quote. It shows the exact principal balance as of today, plus any prepayment penalty or recorded fees that might apply. If you estimate from a statement, you're looking at a variance of maybe two to four hundred dollars depending on how far into the month you are. Enter that balance, your current interest rate, and the remaining number of months until payoff. Next, enter the new loan amount you're targeting, the new rate, and the new term. If you're doing a cash-out refi, add the withdrawal amount to the new loan balance. Make sure the calculator includes your estimated closing costs — typical range is 2 to 5 percent of the loan amount on a cash-out refi, higher on a rate-and-term refi if you're negotiating hard. The output should show two things side by side: the monthly payment difference and the break-even point in months. That break-even is the number that actually matters. If it's longer than half your remaining loan term, the refinance is probably not worth it unless you have a cash-flow problem that the lower payment solves.
One thing I've learned the hard way: input errors are the #1 reason people make bad decisions here. I once had a client enter her current rate as 4.5 percent instead of 6.5 percent. The calculator showed a $200 monthly saving and a break-even at 18 months. The real numbers were barely positive and broke even at nearly 5 years. She would have walked away from a legitimate deal if she'd seen the correct figures. Double-check every field before you let the calculator decide anything for you.
Get the Full Details
What the Numbers Don't Tell You
These calculators assume a static environment. Your rate won't change. The loan won't be paid off early. Prepayment penalties don't exist. None of that is true in practice. When I run a calculation and the break-even is eight months, I immediately ask whether the borrower plans to sell within five years. If they do, the calculator is lying to them, because the closing costs never get recovered. Another blind spot: the calculator doesn't account for the new loan's total interest paid. You can see a lower monthly payment and miss that you're paying significantly more interest over a longer term. I always add a column that subtracts total interest under the old loan from total interest under the new one, including all fees. That net number is the real story. Also, escrow changes matter. A lower principal and interest payment might be offset by a higher property tax or insurance escrow adjustment on the new loan. Lenders often underestimate these, and the payment you thought would drop can stay flat or even rise by twenty or thirty dollars once everything gets re-escrowed.
When the Calculator Is Useless
If your credit score has dropped since you took out the original loan, the rate the calculator spits out won't match what you'll actually qualify for. I've seen this cost people two percentage points on their new rate after a divorce or a collections item hit their report between application and closing. Always run the calculator with a worst-case rate, not the rate you saw advertised, or you're building a plan on sand. Adjustable-rate mortgages are another case where these tools break down. A standard fixed-rate calculator will show you a clean comparison, but an ARM refi introduces rate caps, adjustment schedules, and initial teaser periods that the basic tool ignores. You need a separate projection model that steps through each adjustment period. Otherwise you're comparing a fixed payment to a future payment that doesn't exist yet on paper. If you're underwater on your mortgage or close to it, the calculator assumes you can refinance at all. Most lenders won't touch a cash-out refi with less than 20 percent equity, and many won't do a rate-and-term refi below 80 percent loan-to-value without private mortgage insurance adjustments. The tool can't predict whether you'll get approved. Run the qualification check first, before you spend an hour optimizing numbers that won't apply to you.
A Practical Workaround I Use
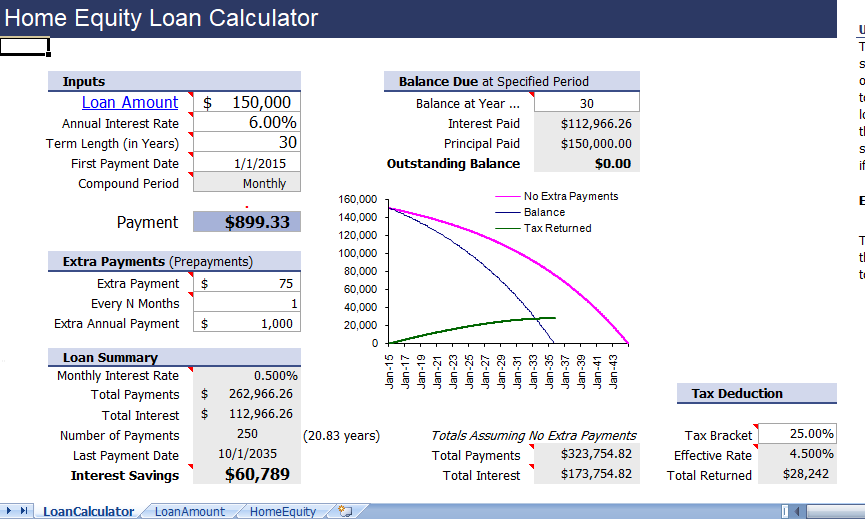
Instead of relying on a single calculator output, I build a quick side-by-side in a blank spreadsheet. Column A is the old loan payment breakdown month by month. Column B is the new loan. Column C is the difference. Column D is the cumulative difference, which is where the closing costs get factored in as a negative spike at month zero. After about ten minutes, you can see exactly when the cumulative line crosses into positive territory — that's your break-even, adjusted for fees, in a way most online calculators won't show you cleanly. This approach also lets you test scenarios: what if the rate is half a point higher than quoted? What if you sell in three years? What if the property taxes jump 8 percent next year? Running those three variations takes about five minutes and usually reveals something the default calculation hides. There isn't a perfect downloadable tool that does all this out of the box. Most free calculators online are built by lead-generation companies, and their output is designed to push you toward a specific lender product. If you want something you can trust, build your own sheet or use a calculator from a reputable mortgage broker who isn't trying to close you that afternoon. The math is the same either way. The incentive behind the tool is different.
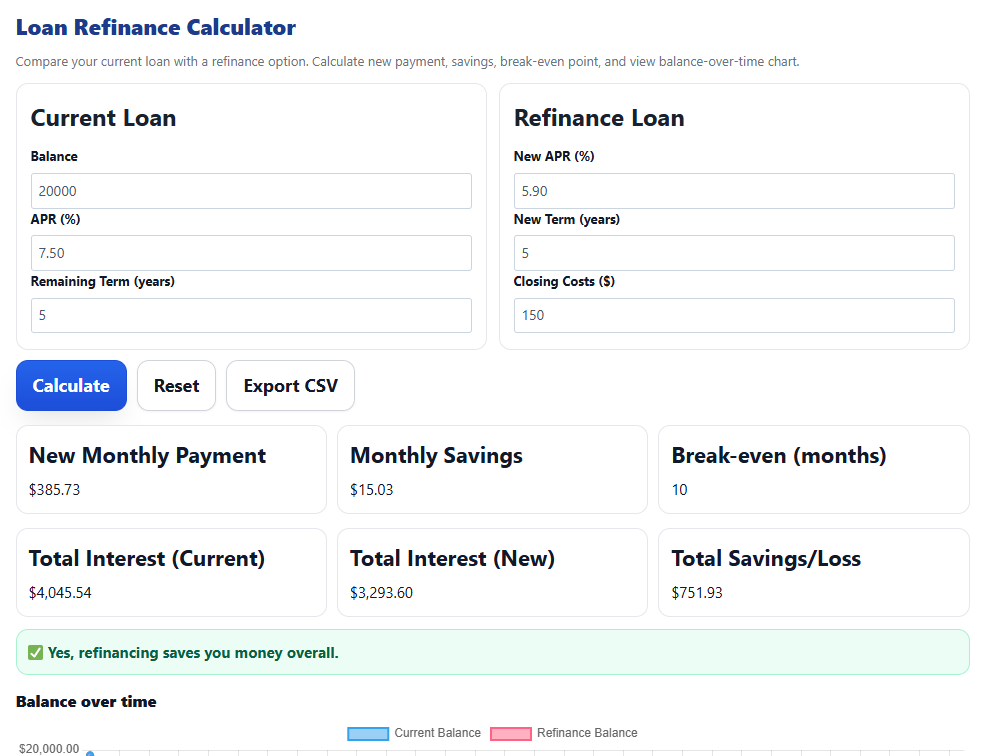
The bottom line is that a Refinance Equity Loan Calculator is a starting point, not a decision engine. It tells you the mechanical outcome of two sets of numbers. It doesn't tell you whether your life situation makes one of those numbers irrelevant. Read the output, sanity-check the inputs, run a couple of stress scenarios, and only then decide whether the refinance is actually worth pursuing.