How a Remodel Loan Calculator Actually Works in Practice
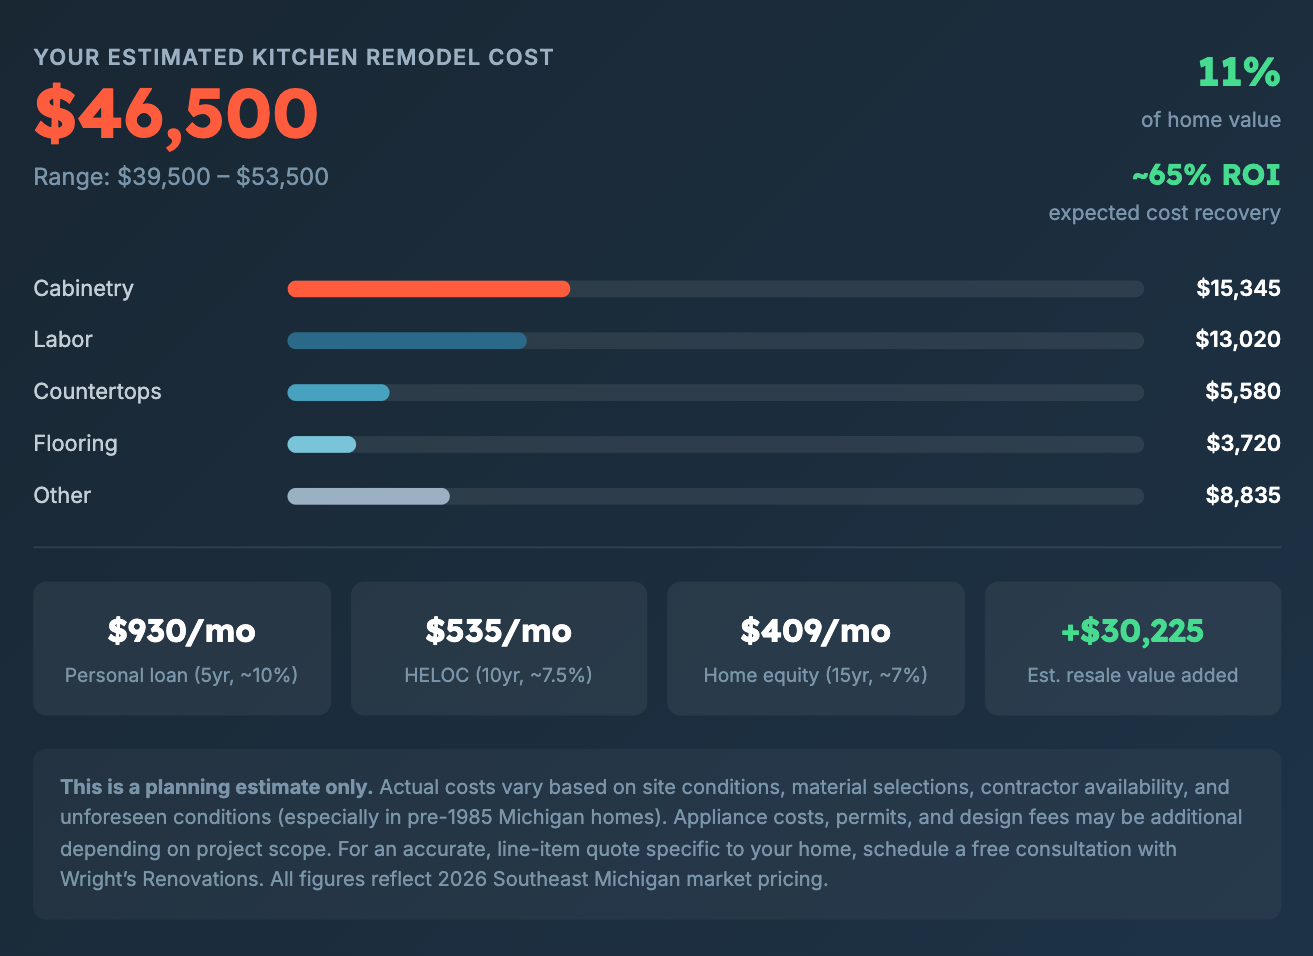
I spent three years working in loan operations before I ever got tired of looking at spreadsheets. The thing about a Remodel Loan Calculator is that most people treat it like a magic box where you throw in numbers and get an answer. It's not. It's a tool that approximates your monthly payment based on the inputs you give it, and those approximations can be wildly off if you don't understand what's happening behind the scenes. The basic math is straightforward. You take your loan amount, divide by the number of payments, add in the interest component calculated on a monthly basis, and you get a monthly figure. Most online calculators use the standard amortization formula. That formula assumes equal monthly payments across the entire term, which means your payment doesn't change whether your project hits a snag in month two or runs smoothly until closing. The calculator doesn't know about your project. It only knows about the numbers you type into it. I ran into a situation last year with a borrower who had a $45,000 home renovation loan at 6.75 percent for ten years. The calculator showed a monthly payment of around $522. Seemed fine. The problem was that the lender was rolling closing costs into the financed amount without the borrower realizing it. The actual loan balance came out to $48,200, pushing the real payment closer to $559. The calculator was correct based on the input it received. It just didn't know about the fees that weren't disclosed upfront.
Using a Remodel Loan Calculator Without Getting Lied To
Here's what most people miss when they run the numbers. They enter the home value and the projected renovation cost, hit calculate, and call it a day. But the loan-to-value ratio matters enormously for rate determination. A calculator will show you the payment on a 7 percent rate, but if your LTV comes in above 80 percent after the remodel, you could be looking at 8.25 percent or higher. That difference shows up as roughly $40 to $60 per month on a typical renovation loan, and over the life of the loan it adds thousands in interest. The appraisal gap is another thing nobody thinks about. You might want to refinance $30,000 of improvements into your mortgage, but if the post-renovation appraised value only comes in $10,000 higher than your current home value, the lender might refuse to finance the full amount. A good Remodel Loan Calculator will let you adjust the projected value and see how the payment changes. Most free ones online don't. They assume the appraised value will always cover what you need, which is naive. I learned to work around the limitations by running parallel calculations. I'd take the base payment from the calculator, then manually add estimated escrow for taxes and insurance, then layer on the HOA if applicable. Then I'd go back and recalculate using a rate that was quarter-point higher than the quoted rate, just to see what the worst case looked like. It takes about ten minutes extra and it saves you from that awkward phone call three weeks later when your actual payment is $80 higher than you budgeted for.
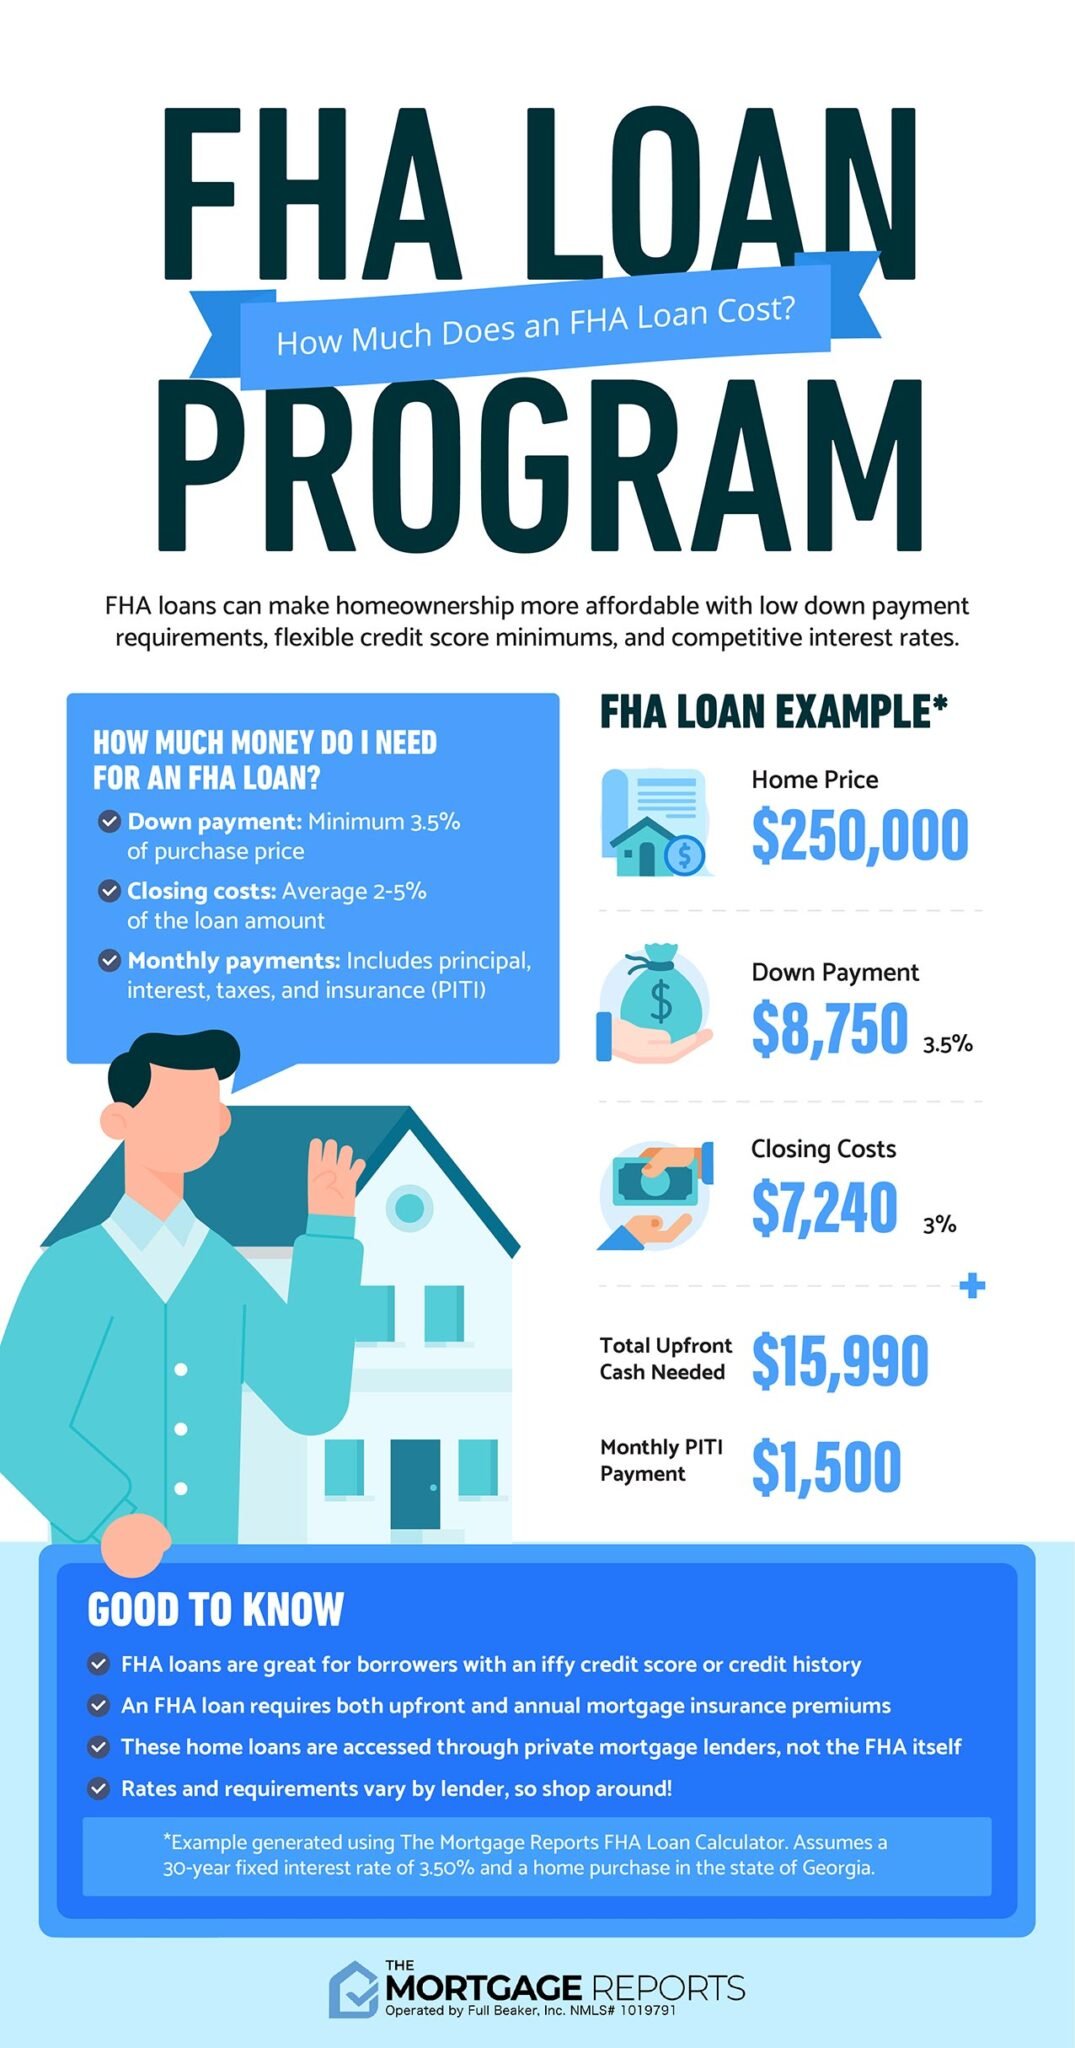
There are a few edge cases where these calculators simply break down. If you're looking at an adjustable-rate renovation loan, the calculator's output is only meaningful for the initial fixed period. After that, the payment could shift based on the index, and no online tool will predict that for you. If you're doing a FHA 203k loan, the calculation gets more complicated because there are reserve requirements and inspection holdbacks that affect the actual disbursement schedule. The monthly payment might be lower on paper, but your actual out-of-pocket costs during the renovation phase can be significantly higher than the calculator shows. Another limitation worth noting: most calculators don't account for property tax increases that come with a higher assessed value after a major renovation. In some counties, a $50,000 improvement can push your annual property taxes up by $600 to $1,200 depending on local millage rates. That's an additional $50 to $100 per month that nobody mentions until you get the first tax bill. The most practical approach I've found is to use the calculator as a starting point, not a final answer. Run the numbers, then ask your lender for a Good Faith Estimate that includes everything. Compare the two. If the difference is more than five percent, something isn't being counted correctly in the estimate or in your calculator inputs. Either way, you now have a concrete number to dispute rather than a vague feeling that something is off.
Get the Full Details

What to Look for in a Reliable Calculator
Not all Remodel Loan Calculator tools are built the same. The ones I trust let you adjust the term length, toggle between fixed and adjustable rates, and see a breakdown of principal versus interest for each payment period. Some of them also include fields for PMI, escrow, and tax adjustments. The simpler the calculator, the more likely it is to give you a number that sounds right but misses important costs. If you're working with a specific lender's calculator on their website, keep in mind that it's often calibrated to their products and rates. That means it could make their loan program look better than it actually is compared to what's available elsewhere. Cross-reference with at least one independent calculator before you commit to anything. The time investment is minimal and the potential savings are real. I keep a simple spreadsheet template that tracks my own calculations alongside what the official tools show. When they diverge, I dig into the assumptions. Usually it comes down to one of three things: the calculator is using a slightly different rate, it's rounding the payment differently, or it's omitting a fee that the lender includes. Finding which one it is takes maybe five minutes and prevents a lot of confusion down the line.
The bottom line is that these calculators are useful but incomplete. They give you a baseline. They don't replace a conversation with a lender who understands renovation financing, and they certainly don't replace a written estimate from your contractor. But if you know where the gaps are and how to work around them, they save you a significant amount of time during the planning phase. Just don't treat the number on the screen as gospel. It's a starting point for a much longer conversation.