What Rent To Own Actually Looks Like When You're Living It
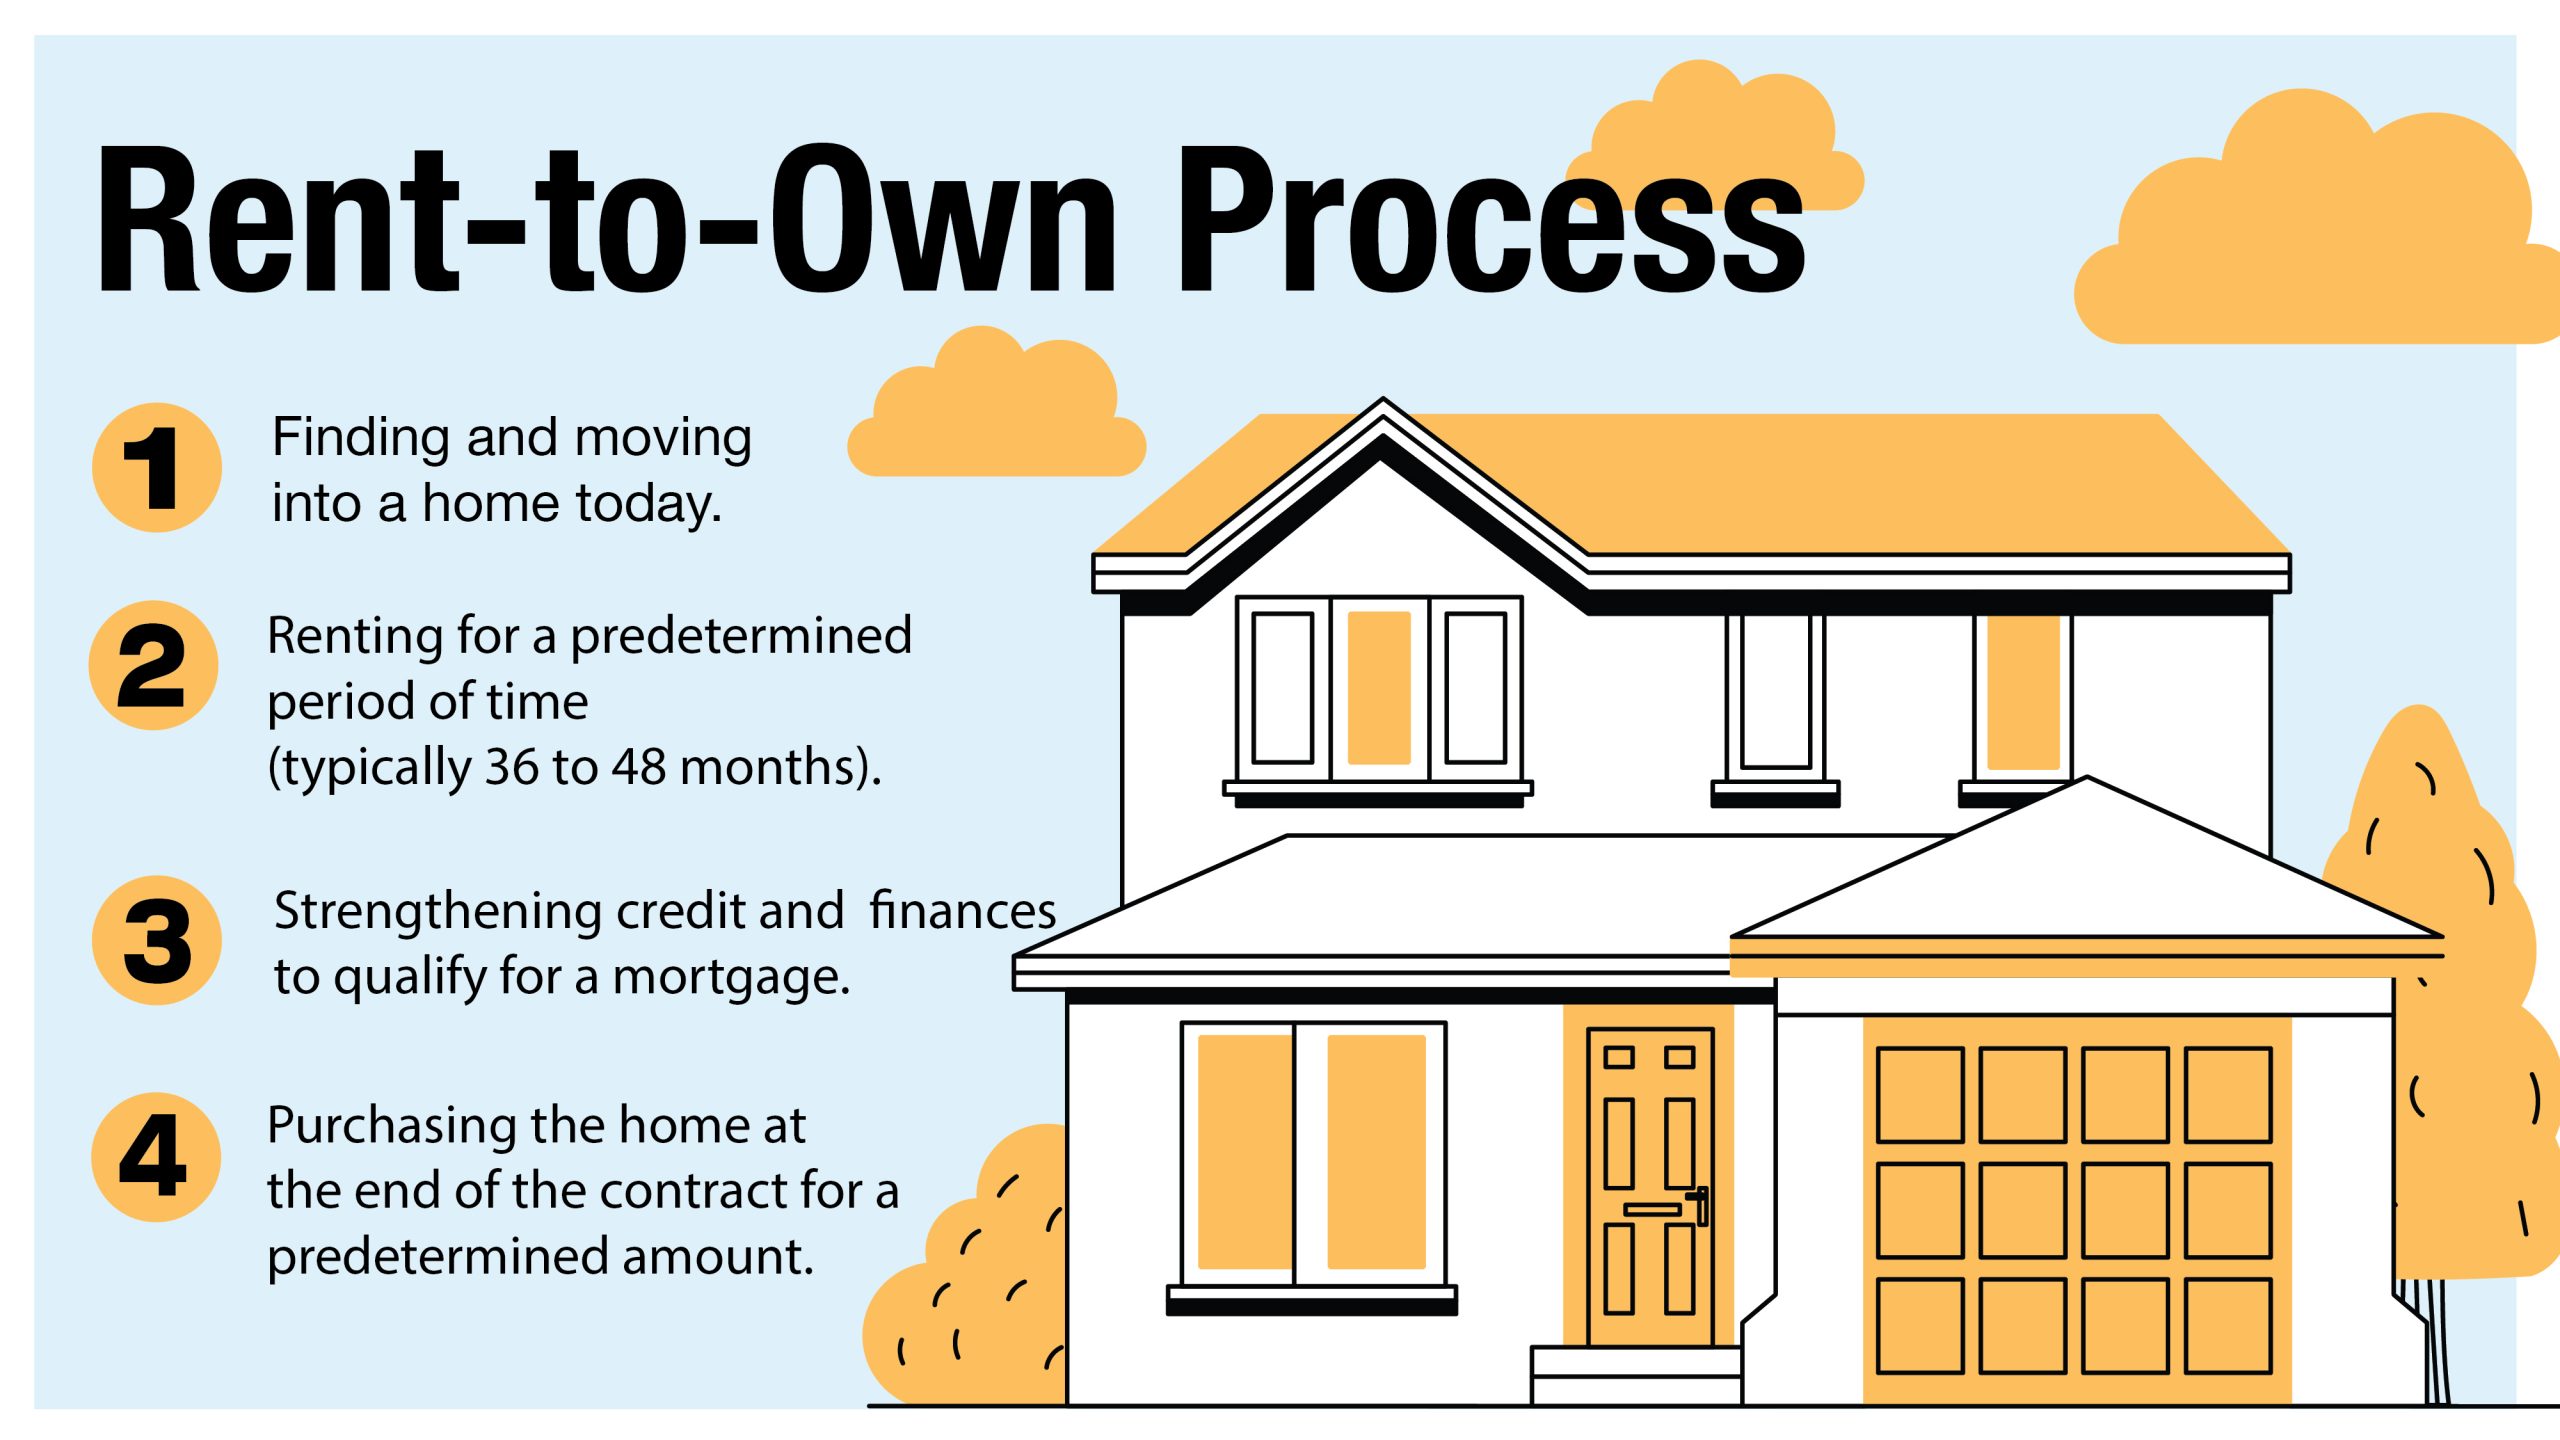
Rent to own is one of those arrangements that sounds straightforward until you read the fine print. The basic idea is simple: you agree to pay a monthly fee for use of an asset, with a portion credited toward eventual ownership. In practice, it exists across several sectors, and each one operates differently. I've sat through enough conversations about it to know that most people enter these deals without understanding the mechanics. That gap is where problems start. I'm going to walk through the model as it shows up in two specific areas: vehicle rent to own programs and equipment rental with purchase options. Those are the corners I've actually worked in. There are other variations, but they share enough DNA that the principles transfer. If you want to learn more about how the industry handles rent to own careers specifically, I'll cover that in a dedicated section below.
The Math Behind Rent To Own Deals
The monthly payment you see is almost never a fair market rent. It's priced to include a profit margin for the company, plus a built-in equity credit component. Here's a concrete example from a real deal I worked with last year. A used commercial van listed at $18,000 on a rent to own plan ran about $680 per month for 36 months, with $150 of each payment going toward the purchase credit. That means you'd pay roughly $24,480 total, of which $5,400 accumulated as equity. The remaining $19,080 covers interest, fees, insurance coordination, and the company's margin. Compare that to financing the same vehicle at 7% APR over three years, which would cost about $550 per month and $19,800 total. The rent to own path costs $4,680 more. That extra amount is the price of convenience and looser qualification standards. Whether it's worth it depends entirely on your situation. The key metric to track is the annualized cost of capital embedded in the payment structure. Most rent to own contracts don't disclose this directly. You can reverse-engineer it by treating the total payments as a loan and calculating the implied APR. If it's above 15%, you're paying a significant premium for access.
How to Vet a Rent To Own Provider
I've seen people get burned by three types of companies. Type one charges hidden fees that only appear in month three or four. Type two structures the credit allocation so slowly that you barely build equity in the first year. Type three makes it nearly impossible to exercise the purchase option because they demand paperwork that contradicts what was originally agreed to. Before signing anything, request a complete amortization schedule showing exactly how each payment splits between equity credit, fees, interest, and base rent. If they refuse or hand you a vague spreadsheet, walk away. Reputable operators will provide this without friction. Check whether the contract includes a clear purchase option clause with a defined buyout price at each point in the term. Some deals tie the buyout to current market value, which creates uncertainty. Others fix it upfront, which is far more predictable. I prefer fixed buyout pricing because it lets you calculate exactly what you owe at any given month.
Get the Full Details
Also verify whether the provider holds a state license for rental-purchase agreements. Requirements vary by jurisdiction, but operating without one is a red flag in most places. You can usually verify this through your state's consumer protection or attorney general office website.
The Practical Mechanics of Entering a Rent To Own Arrangement
The application process is intentionally lightweight compared to traditional financing. Most providers won't run a hard credit check, or if they do, they weight income and employment history more heavily than credit score. That's the tradeoff: easier access, higher cost. I've approved people with credit scores in the 520 range through rent to own, and I've also seen people with 680 scores end up paying more than they needed to because they didn't compare financing options. Documentation typically includes proof of income, a bank statement showing cash flow, and sometimes a reference from a current landlord or employer. If you're applying for equipment rather than a vehicle, you may also need to demonstrate how you'll use the asset to generate revenue. This is especially common with tools, machinery, and commercial vehicles. Insurance is another area where rent to own deals differ from standard purchases. The provider usually requires you to carry comprehensive coverage with them named as loss payee. Some bundle insurance into the monthly payment, which simplifies things but often inflates the total cost. Getting your own policy and providing proof of coverage can save money, but you need to verify that the provider accepts third-party insurance before you commit to that route.
One thing most people overlook is the early termination clause. If you decide to sell or refinance the asset before the term ends, you'll typically owe the remaining balance minus any equity already accumulated, plus a possible early payoff fee. I've seen contracts with penalties as high as 10% of the remaining balance. Negotiate this down or find a provider that doesn't charge it.

My Experience With a Problematic Contract Clause
Last fall I worked with a client who signed a rent to own agreement for a delivery van. Everything looked reasonable on paper. Then at month 14, the provider sent a notice requiring a mandatory vehicle inspection at a specific facility 40 miles away, with a $200 fee. The contract mentioned inspections but didn't specify the fee or location. When I pushed back, the provider cited a clause buried in section 8, subsection D about "periodic condition assessments at provider-designated locations." The workaround was straightforward: I pulled the original signed agreement and cross-referenced it with the addendum they'd added six months earlier through their online portal. The addendum contained the inspection fee but wasn't referenced in the main contract. I wrote a formal dispute citing the contradiction, referenced the doctrine of contradictory provisions favoring the non-drafting party, and demanded a waiver. They conceded within 11 business days. The lesson is that providers will slip additional terms into digital addendums without making them prominent. Always check every document in your account, including versions and updates, not just the original signature package.
Rent To Own Careers: What the Industry Actually Offers
When people search for rent to own careers, they're usually looking for one of two things. Either they want to work inside a rent to own company, or they want to use rent to own as a pathway into a trade or business. I'll address both. Working inside the industry breaks down into a few roles. Sales representatives handle client outreach and deal structuring. Operations staff manage asset maintenance, insurance coordination, and documentation. Collections and accounts receivable teams handle payment processing and delinquency management. Technology roles exist too, particularly in customer portal development and payment automation. Entry-level positions typically require no more than a high school diploma and basic computer literacy. Mid-level roles pay between $38,000 and $55,000 annually depending on location and responsibility. Management tracks can reach $70,000 to $90,000. Using rent to own as a career pathway is different. Some people use it to acquire tools, vehicles, or equipment needed for a trade. A roof contractor might rent to own a ladder system. A landscaper might do the same for a trailer. An electrician might acquire diagnostic tools through a lease-to-own program. The math has to work for your specific situation, but it's a legitimate strategy when traditional financing isn't available.
There's also a growing niche in rent to own training programs and certification courses. Some providers partner with trade schools to offer equipment packages bundled with coursework. You rent the tools during training, and the payments apply toward ownership once you complete the program. These arrangements vary widely in quality. I recommend verifying that the training provider holds proper accreditation before committing.

Common Pitfalls That Beginners Miss
The biggest mistake I see is people treating rent to own like a long-term financial strategy when it's designed to be a short-term bridge. The effective APR on most programs ranges from 18% to 35%. That's predatory lending territory if you stay in the arrangement for the full term. The smart move is to use it for three to six months while you rebuild credit or stabilize income, then refinance into traditional financing. Another pitfall is failing to track equity accumulation. Some providers report equity incorrectly or delay crediting payments. I keep a personal spreadsheet that tracks every payment against what the provider reports. When I found a discrepancy of $340 in one case, I escalated it with documentation. The provider corrected it and adjusted future statements. Without tracking, you'd never know. A third mistake is ignoring the total cost comparison. Before signing, run the numbers against at least two alternative options. Credit union loans, employer equipment programs, and used car dealer financing often beat rent to own on price. If the rent to own deal is the only option available, that's fine, but go in aware of what you're paying.
When Rent To Own Makes Sense and When It Doesn't
Rent to own works well if you need an asset immediately and qualify for nothing else. It works if you can identify a clear refinance path within six to twelve months. It works for small-ticket items where the convenience premium is proportionally acceptable. It does not work as a long-term solution. It does not work for high-value purchases where the interest cost compounds significantly. It does not work if you have any ability to obtain conventional financing, because the cost difference will eat into your savings faster than the convenience saves you time. If rent to own is your only path right now, use it deliberately. Set a concrete timeline for refinancing. Track every payment. Read every clause. And when you exit the arrangement, get the title transfer in writing within the same business day. I've seen delays of three to four weeks on title processing, and during those weeks you own nothing and have no leverage.


