Building a Retirement Expense Budget Worksheet That Actually Works
Most retirement planners hand people a blank spreadsheet and tell them to figure it out. It does not work. The problem is not lack of data. The problem is structure. Without a clean framework, you end up double-counting or forgetting expenses that disappear in month one. I spent years watching this go wrong at client tables, so let me walk you through how to actually build this thing.How to Build Your Retirement Expense Budget Worksheet
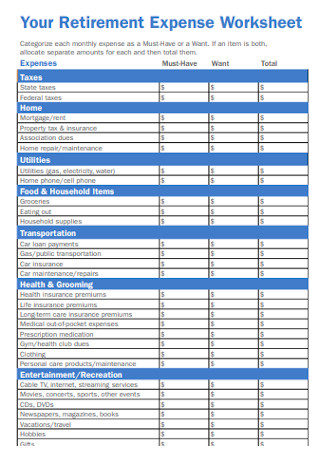
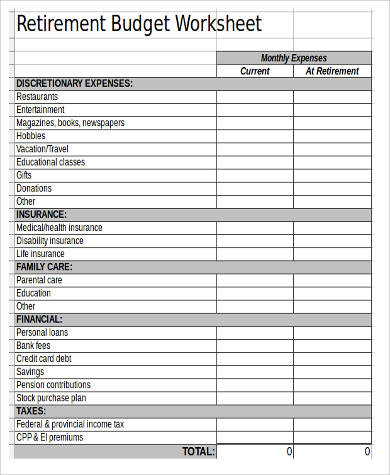
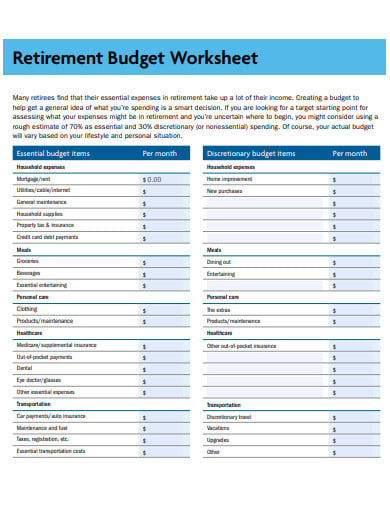
Start with a blank sheet. Do not pull a pre-made template from the internet unless you are prepared to tear it apart and rebuild it. Most free templates assume a two-income household and ignore healthcare spikes, property tax variations, and the fact that your spending pattern changes dramatically between age 60 and age 75. Here is the basic skeleton.Column A: Category. House it under Housing, Healthcare, Food, Transportation, Insurance, discretionary, and unexpected.
Column B: Annual amount. Put the raw dollar figure. Not monthly. Annual. Keeps things consistent across categories that some people pay quarterly or annually. Column C: Inflation adjustment factor. This is where most worksheets fail. Use 3% as your baseline for general inflation, but bump healthcare and long-term care to 5-6%. The gap between 3% and 6% compounds into real pain over a 30-year retirement. Column D: Year-by-year projection. Rows for year one through year thirty or however long your planning horizon runs. Simple formula: previous year total times one plus the inflation factor for that category.
Column E: Income offset. Social Security, pensions, required minimum distributions, annuity payments. This row subtracts guaranteed income from annual expenses to show your shortfall or surplus by year.
I built a version of this worksheet for a client who was retiring at 62 from a union pension job. On paper, the numbers looked fine until I added the healthcare column. He was buying into a Medicare supplement plan at 62 instead of waiting until 65. That cost him roughly $12,000 a year out of pocket. The base template nobody gave him had health insurance lumped into a generic "medical" line item at $4,000 annually. Completely wrong number. I added a separate bracket for the three-year gap before Medicare eligibility with the actual premium he was paying, and it shifted his year-one shortfall by almost $8,000. That difference changed the entire withdrawal strategy we recommended.Get the Full Details
Practical setup steps: 1. List every expense you have had in the last twelve months. Every single one. If it appeared on a statement, it goes in the list. 2. Group them into the six categories above. Be ruthless. Subscriptions belong in discretionary. Home warranties belong in housing maintenance, not insurance.
3. Assign each category its own inflation factor. Use historical data for your region if you can find it. Property tax reassessment schedules vary wildly by county. Check your local assessor's office website rather than guessing. 4. Add your income streams in a separate section. Social Security age matters enormously. Claiming at 62 versus 70 creates a $2,000 to $4,000 annual difference per $1,000 of monthly benefit. 5. Calculate the gap. Subtract total income from total expenses for each projected year.
6. Run a stress scenario. Assume a 25% market decline in year one and two. See which categories you cannot cut. Those are the ones that will force you to sell investments at a loss or dip into emergency savings.