The Actual Mechanics of Saving When You're the One Paying Yourself
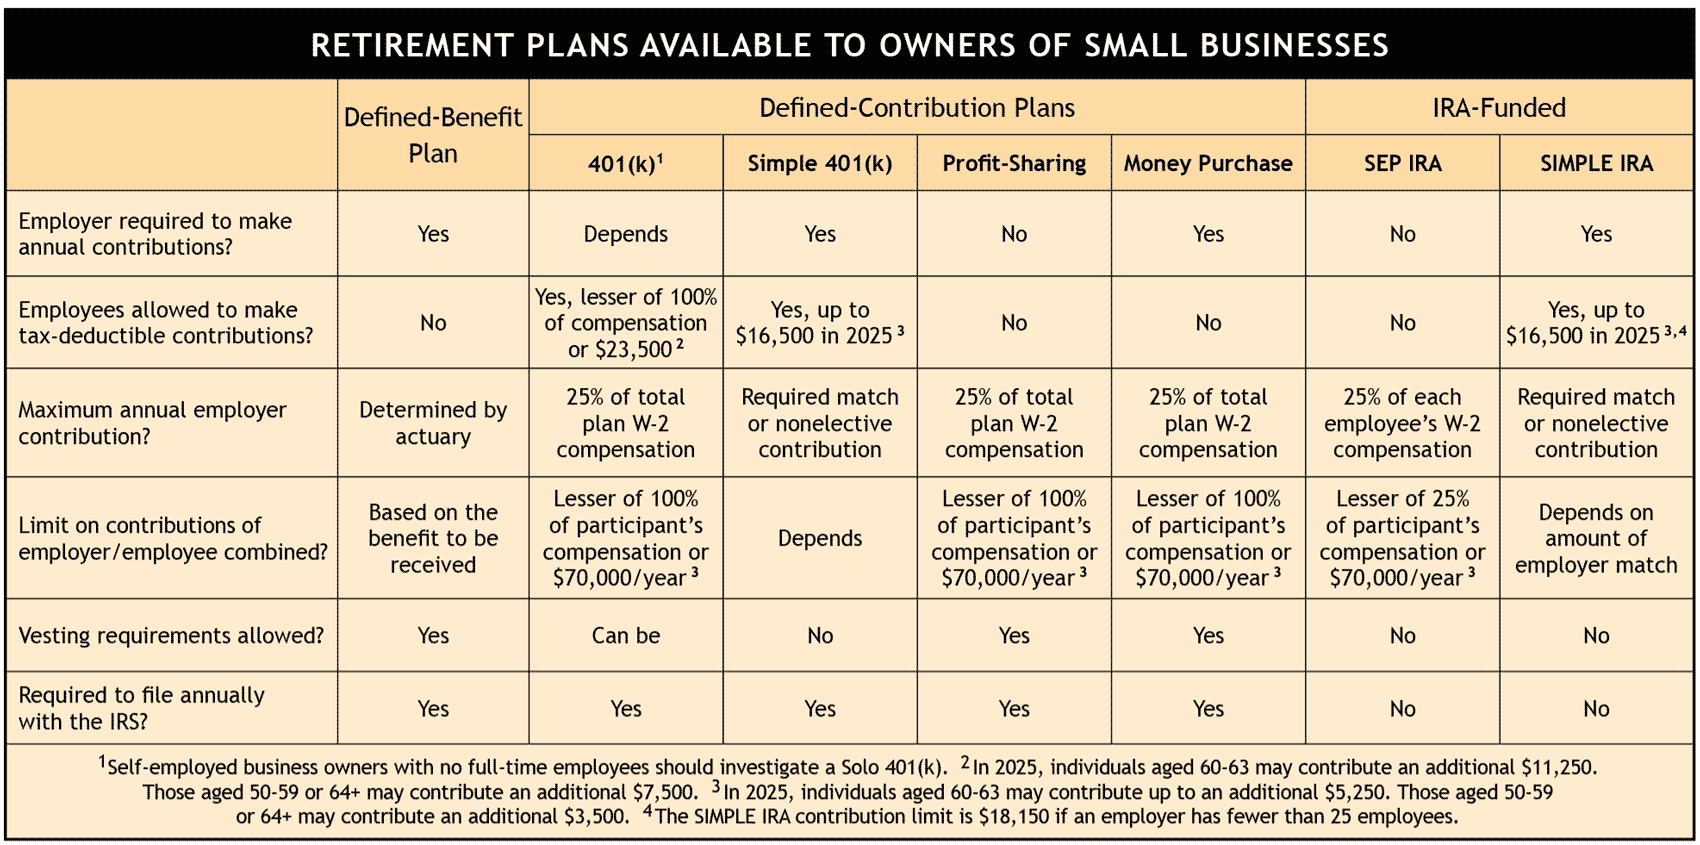
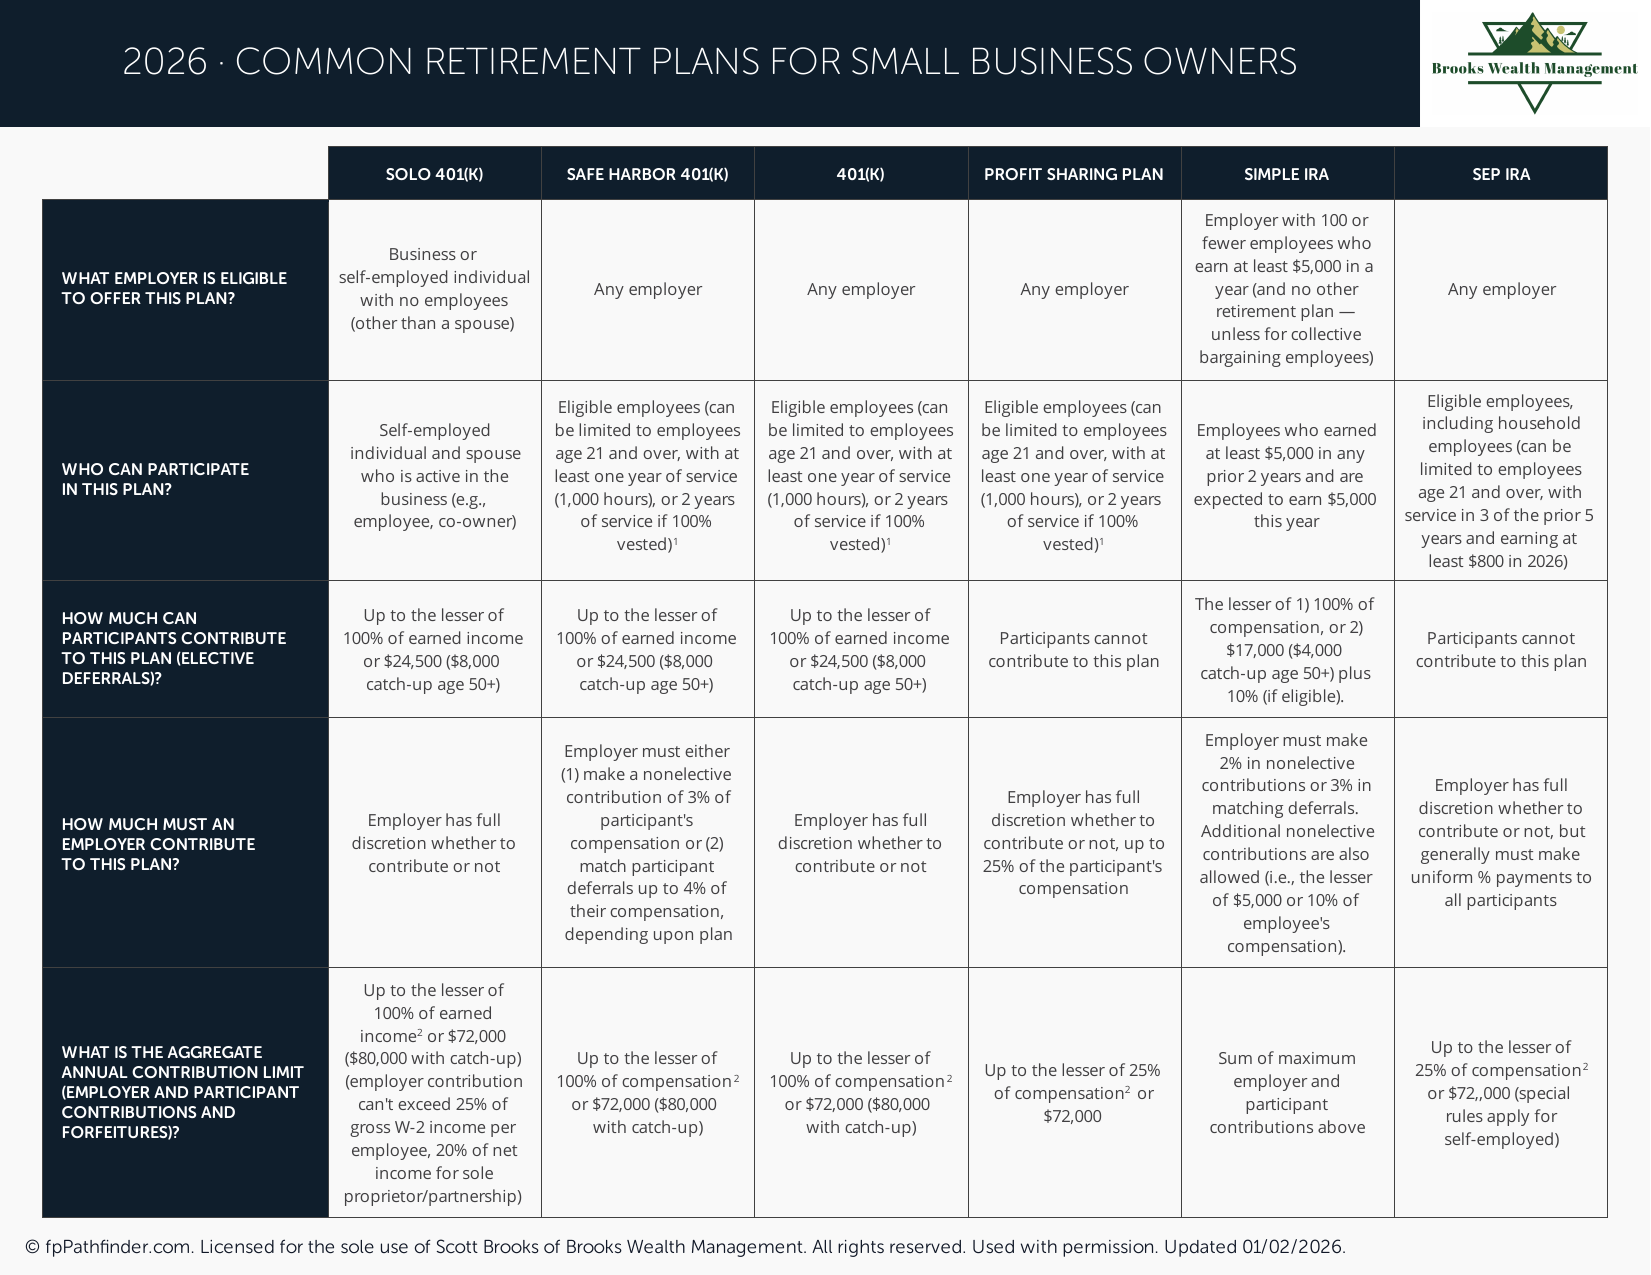
Most small business owners think they have two options: save a little through a regular 401(k) at a day job, or save nothing because their business is too volatile. Neither is accurate. The tools exist. They just sit unused because the setup feels like a tax filing exercise, and it is, but only once per year.The first thing I tell people who ask about Retirement Planning For Small Business Owners is to pick one vehicle and set it on autopilot before Q1. December is when everyone remembers they need to contribute, and by then the compounding gap is already real. A solo 401(k) lets you stash up to $23,000 of your own money in 2024, plus an employer profit-sharing contribution up to $69,000 total across both buckets, whichever structure fits your income profile. SEP IRA caps out lower on the employee side but is simpler to administer. SIMPLE IRA is roughly equivalent to a 401(k) with a mandatory employer match and lower contribution limits. Pick based on expected earned income, not hope.
Retirement Planning For Small Business Owners: The Cash Flow Problem No One Talks About
Here is the part that trips people up every single year. You can't just decide in October that you want to maximize your retirement contribution. With a solo 401(k), the employer profit-sharing portion has to be established by December 31st, but you actually have until your tax filing deadline plus extensions to fund it. That delay is useful if your income is lumpy, but it requires discipline most people don't have. I watched a contractor who made $180,000 in a good year deposit $4,000 into his SEP because he assumed he'd figure it out later. He ended up with $30,000 in tax savings he didn't use and a regret he carried for two years.The workaround I use with clients who have inconsistent revenue is to set a tiered contribution schedule. When the business hits certain milestones, say $50,000 in quarterly net earnings, a percentage automatically flows into the retirement account. When revenue dips, the contribution drops proportionally. This removes the emotional decision from the moment and keeps the habit intact without overcommitting during thin months. It usually takes about 20 minutes to configure through a brokerage platform like Fidelity or Vanguard, and once it's running, it requires zero attention until tax season.
Common Pitfalls That Cost People Real Money
Contributing to a retirement account doesn't reduce your self-employment tax. It reduces your adjusted gross income, which matters for other thresholds, but SE tax is calculated on Schedule SE before retirement contributions enter the picture. This catches people off guard. A self-employed person making $120,000 might think dropping $30,000 into a solo 401(k) saves them $4,680 in taxes. The actual self-employment tax savings from that contribution is closer to $2,100 because only about 92.35% of net earnings are subject to SE tax, and the retirement contribution itself doesn't touch that calculation. The income tax savings are real, but they are separate.Another issue is the RMD age change. The SECURE 2.0 Act pushed the required beginning date to age 73 for those who reach that age after 2022. If you are planning around a traditional solo 401(k), factor in that you will be pulling money out five years later than previous generations did. This actually helps compounding in the account, but it means you need to plan for a longer accumulation window and a different withdrawal strategy in your later years. Roth conversions in your low-income years between 55 and 70 can offset this shift significantly.
Get the Full Details
When the Standard Options Fall Apart
A defined benefit plan sounds extreme until you are a 55-year-old business owner earning $200,000 or more with no employees besides a spouse. These plans let you contribute $100,000 to $300,000+ per year depending on your age and actuarial assumptions. The catch is the administrative overhead: annual actuarial filings, trust setup, and plan document maintenance run $2,000 to $5,000 per year. If your business income fluctuates wildly or you are under 50, the math rarely works. I recommended one against it for a client making $150,000 because the setup cost alone would consume the tax advantage for three years of contributions. In those cases, a mega-backdoor Roth through a solo 401(k) is often the cleaner path, letting you funnel $7,500 in after-tax dollars beyond the standard limits if the plan allows it.The one scenario where almost nothing works well is when your business has significant debt service or seasonal cash drains that make any fixed contribution schedule impossible. In that case, treating retirement savings as the residual line item after debt and operations is a slow leak. The honest alternative is to establish a minimum floor contribution during peak months and treat the rest as optional, rather than letting the whole thing collapse to zero. Even $500 per month consistently beats $6,000 once a year and nothing the rest of the time, simply because the money has more years to compound.