What a Reverse Home Loan Calculator Actually Does
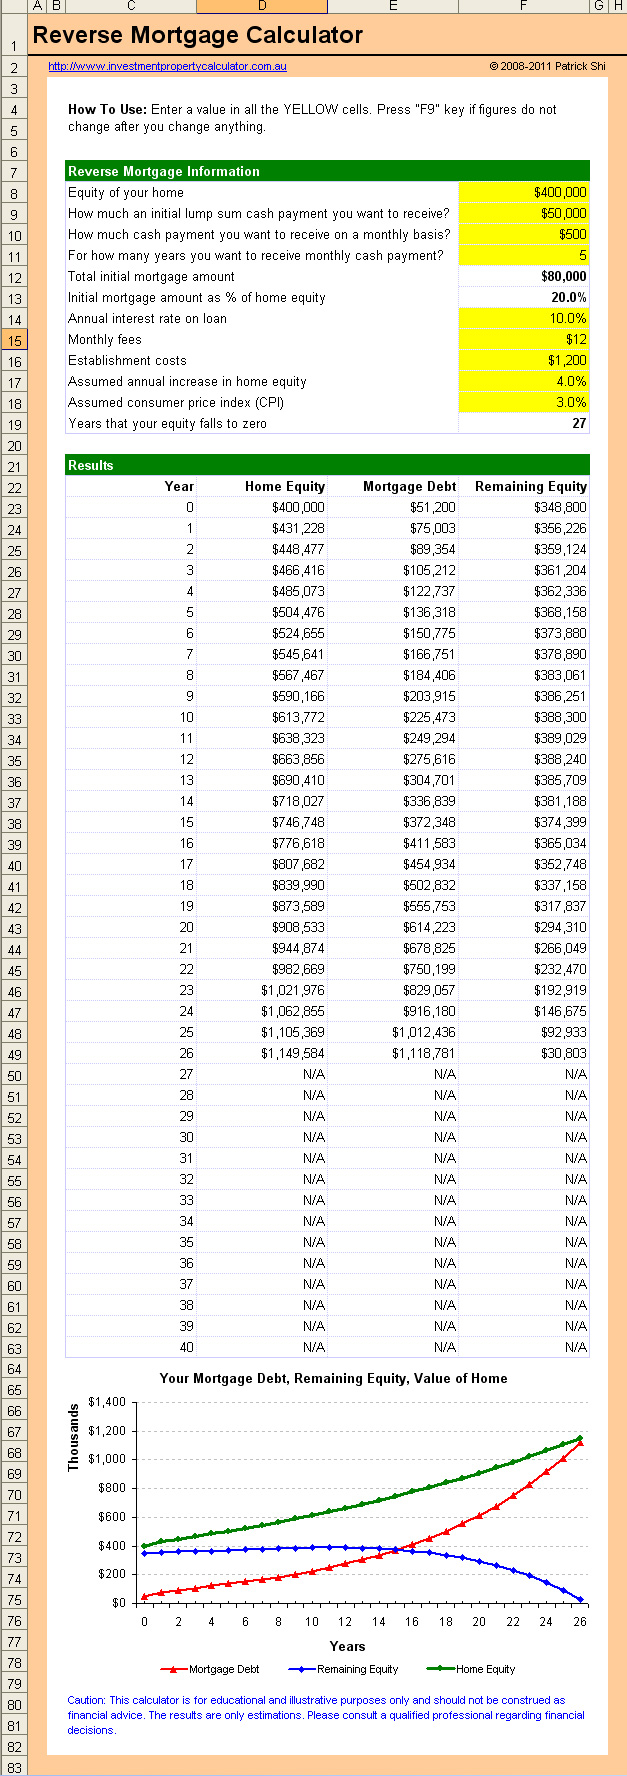
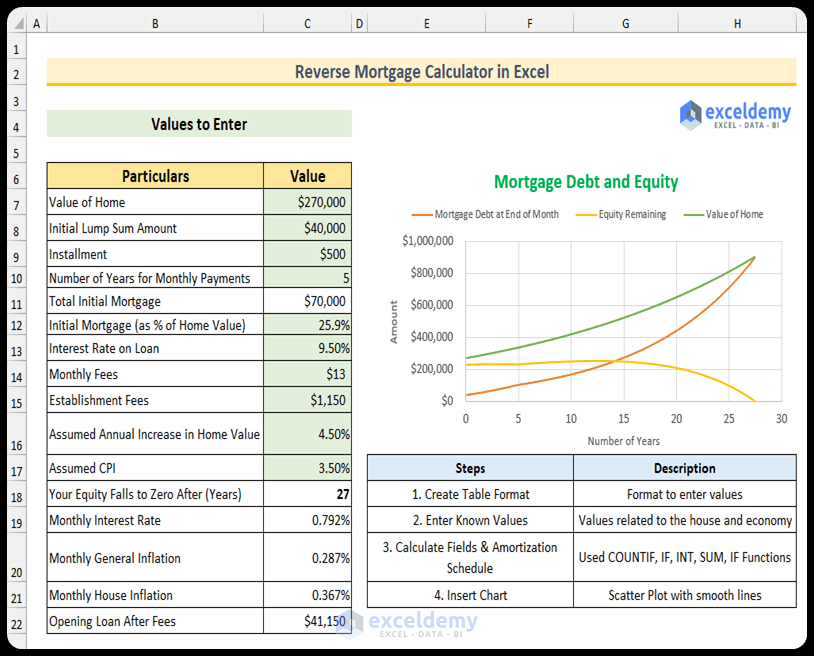
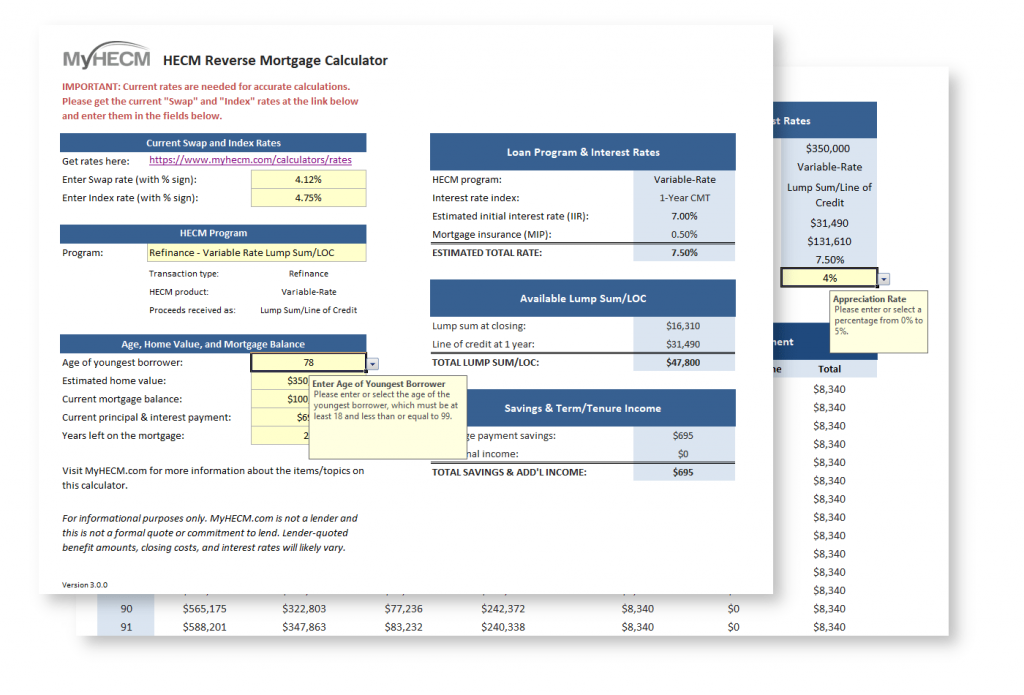
A reverse home loan calculator takes your home's appraised value, your age, and current interest rates and produces a single estimate of how much cash you could access. That's it. The output is not a guarantee, not an offer, and not a binding number from any lender. It is a directional figure based on HECM lending limits and standard qualification tables. The Federal Housing Administration publishes annual lending limits, and those limits cap the maximum home value most calculators use as input. If your home is worth more than the limit, the calculator assumes the cap. Everything above that stays on the table unless you have jumbo reverse mortgage products, which are far less common and use different formulas entirely. The thing nobody tells you is that the calculator does not know your financial story. It does not know you refinanced this house in 2009 because you were underwater. It does not know you carried a second lien for ten years and finally paid it off last spring. It does not know you intend to stay twenty years or plan to sell in three. Those details matter more than the number it spits out.
How to Use a Reverse Home Loan Calculator Properly
Enter the current appraised value of the home. Do not use the listing price. Do not use what you think it is worth based on a neighbor's sale. Use an actual appraisal or a professional comparative market analysis. The difference between a rough guess and a proper valuation can shift the available principal by ten to fifteen percent, sometimes more in volatile markets. Then enter your exact age on the date you would apply. Age is the single biggest variable in reverse mortgage calculations. A six-month difference can change the qualifying age and alter the loan amount. Lenders use the younger of the two borrower ages, so if you are married, both ages matter. Input the existing mortgage balance, if any. The calculator subtracts any open liens from the equity before applying the lending factor. This is where most people make mistakes. They forget to include a home equity line of credit they used for kitchen renovations, or they omit a tax lien. You must include every recorded lien, including municipal liens, HOA assessments, and judgment liens. An incomplete lien list produces an inflated result, and when the underwriter pulls the HUD-1 or closing disclosure later, the approved amount drops. Your closing meeting then becomes awkward. After you run the numbers, take the output and stress-test it. Subtract 3 percent from the result. That gets you closer to what a real underwriter might approve after factoring in the upfront mortgage insurance premium, origination fees, and the standard servicing fees. The calculator typically shows available principal, not net proceeds. Available principal means the maximum you could theoretically draw. Net proceeds means what lands in your bank account after fees. Those are not the same number. The gap widens quickly.
The Hidden Variables Nobody Puts in the Form
One edge case I dealt with recently still sticks in my mind. A client ran a Reverse Home Loan Calculator and got a result around $280,000 available. She was thrilled. Then we pulled her title report and found an abandoned mechanic's lien from a roof contractor in 2011 that had never been formally satisfied. It showed up on title but did not appear in her mental accounting. The lien was old, possibly unenforceable, but the reverse mortgage lender required it cleared before funding. We ended up using part of the reverse mortgage proceeds at closing to pay off that old lien. Her available principal dropped to approximately $247,000. The calculator never knew about the lien because the calculator never sees the lien. It only sees the mortgage balance you type in. Another detail that trips people up is the property type adjustment. Calculators usually assume a single-family owner-occupied home. If the property is a manufactured home, a condo, or a multi-unit building with non-owner-occupant tenants, the lending factor shifts. Manufactured homes often carry lower loan-to-age factors because the collateral deprecates. Condos require HUD approval or Fannie Mae eligibility, and not every complex qualifies. If your property type is non-standard, take the calculator number and discount it by roughly 10 to 15 percent as a working rule of thumb until you get a formal quote. The interest rate environment is also trickier than it looks. Most free calculators default to a fixed-rate assumption or use a blended rate that does not reflect current conditions. Since 2022, adjustable-rate reverse mortgages have been more common than fixed-rate products for new originations. The spread between the index and the margin matters. If a calculator shows a 6.5 percent rate but the actual product is priced at SOFR plus 2.75 percent, and SOFR is at 4.8 percent, your real rate is closer to 7.55 percent. Higher rates reduce the principal limit factor. The calculator will overstate your borrowing power if it uses an outdated or optimistic rate assumption.
Get the Full Details
When the Calculator Completely Fails You
There are scenarios where a Reverse Home Loan Calculator produces garbage results. The first scenario is homes valued above the HECM conforming lending limit. In high-cost counties, the ceiling can exceed $1 million, but if your home is appraised at $1.4 million, the calculator still uses the limit. You might genuinely qualify for more through a jumbo reverse mortgage, but free online calculators do not model that. You need a lender who specializes in non-HECM reverse mortgages and runs a proprietary quote engine. The gap between the calculator output and what you could actually access can exceed $100,000 in these cases. The second failure mode is reverse mortgage for government employees and military personnel with unique employment restrictions. Some calculators assume unrestricted occupancy, but certain VA-backed arrangements and specific employment contracts impose constraints that affect eligibility. Again, the calculator cannot see those constraints. The third is when you have non-standard income or credit issues. While reverse mortgages are non-recourse and do not require minimum income verification in the traditional sense, lenders still assess your ability to pay property taxes and insurance. If your calculated numbers look strong but your tax payment history is spotty, the lender may require an escrow account or reduce the principal limit. The calculator has no way to account for that.
A Practical Walk-Through
Here is a concrete example. Let us say you are 71 years old, your home is appraised at $425,000, and you have a $60,000 remaining mortgage. The calculator applies the current principal limit factor for a 71-year-old with a fixed rate around 6.75 percent. Let us assume the factor comes out to roughly 45 percent of the home value, capped by the lending limit. You multiply $425,000 by 0.45, giving you $191,250 in principal limit. Subtract the $60,000 mortgage balance, and you get $131,250 in available equity. That is the headline number most people see. Now strip out the costs. The upfront mortgage insurance premium is 2 percent of the home value at closing, which is $8,500. Origination fees vary but typically run $4,000 to $6,000. Closing costs, appraisal, title insurance, and recording fees add another $3,000 to $4,500. Settle on the mid-range and you are looking at roughly $18,500 in closing costs. Subtract that from the $131,250, and your true net available equity is closer to $112,750. The calculator showed $131,250. The reality is nearly $20,000 less. If you choose a line of account that grows over time rather than taking a lump sum, the math changes further. The unused portion of your credit line appreciates at the contract rate plus the mortgage insurance component. That growth is real and valuable, but it does not show up in a basic calculator output. If you plan to use the reverse mortgage as a financial buffer rather than a immediate cash dump, the line of credit structure is often the right call. Most calculators do not model that nuance clearly.
Alternatives When a Calculator Is Not Enough
If your situation involves a high-value home, complex title issues, or unusual property characteristics, skip the free calculator and go straight to a licensed reverse mortgage originator. A proper consultation with a HUD-approved counselor and a reputable lender will take you from a rough estimate to a Pre-Approval Estimate within two to three business days. The PEA includes actual lending factors based on your exact age, current rates, and verified property details. It replaces the calculator guesswork with a document you can bring to closing. For simple cases where you just want to understand the ballpark, a Reverse Home Loan Calculator works fine as a first step. But treat the number as a starting point, not a destination. The real number lives in the closing documents, and that number is always lower than what the calculator displays.