How Reverse Mortgage Amortization Actually Works
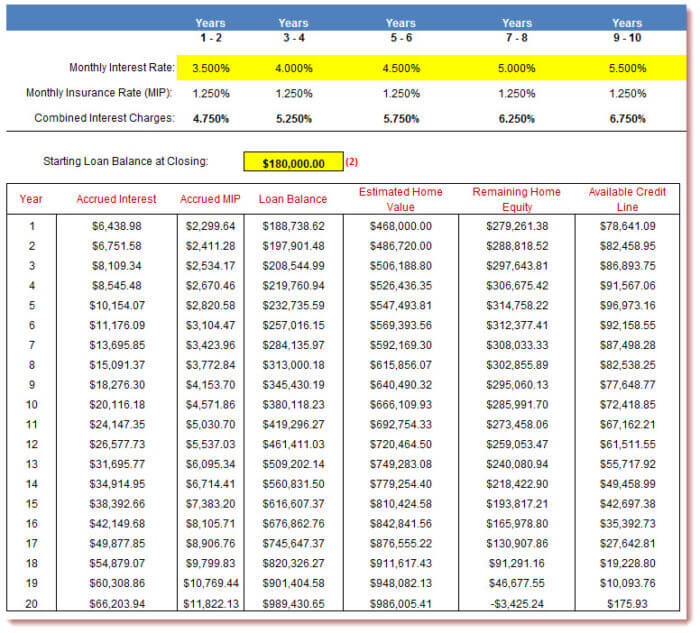
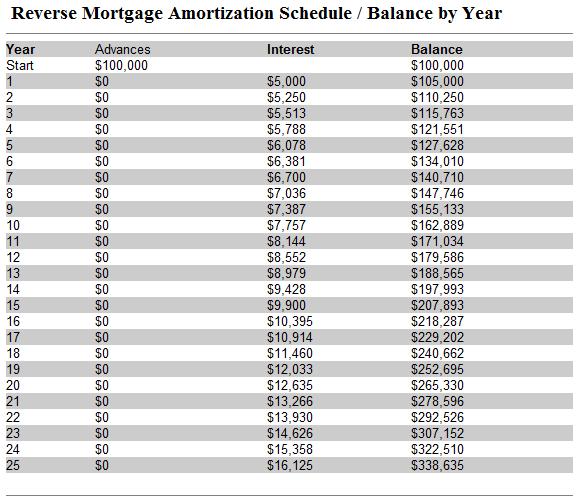
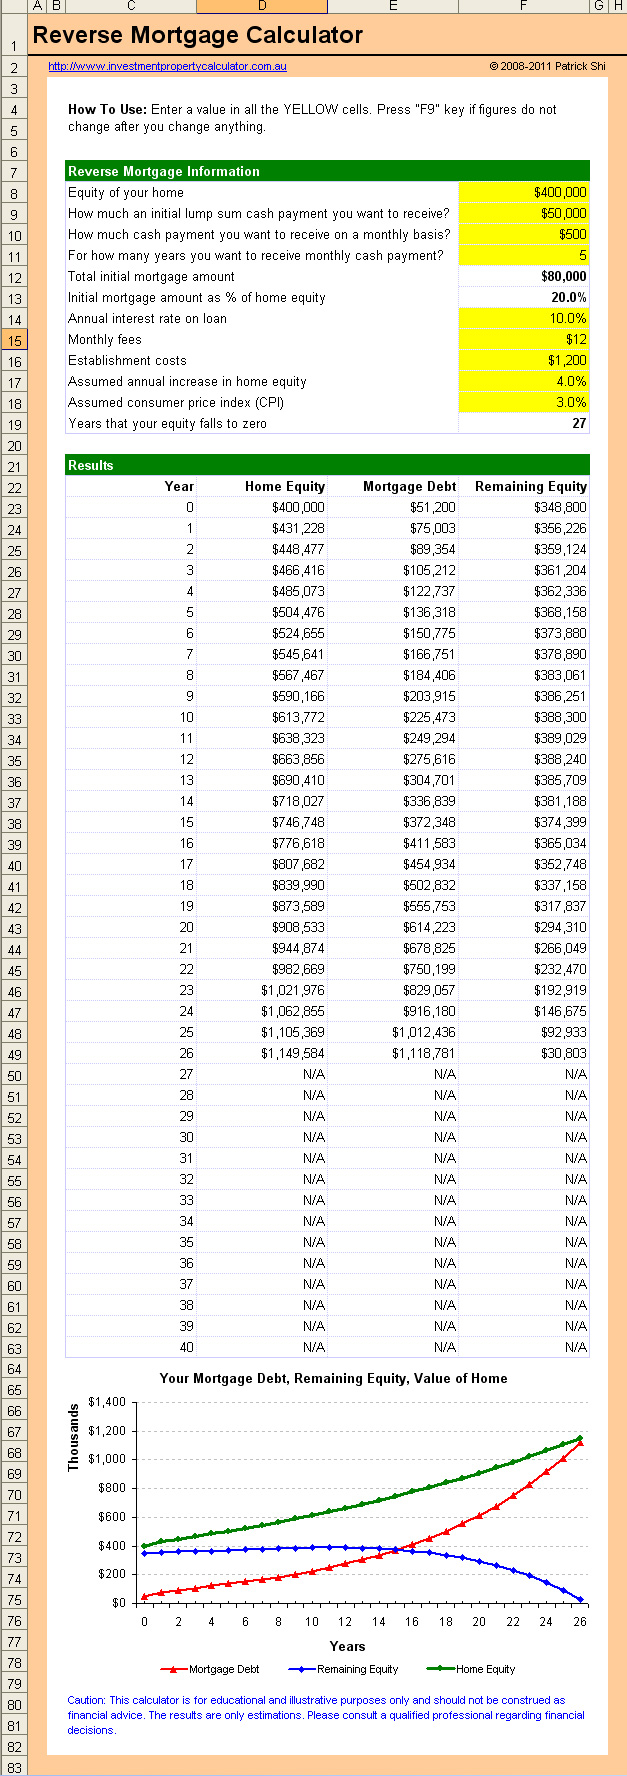
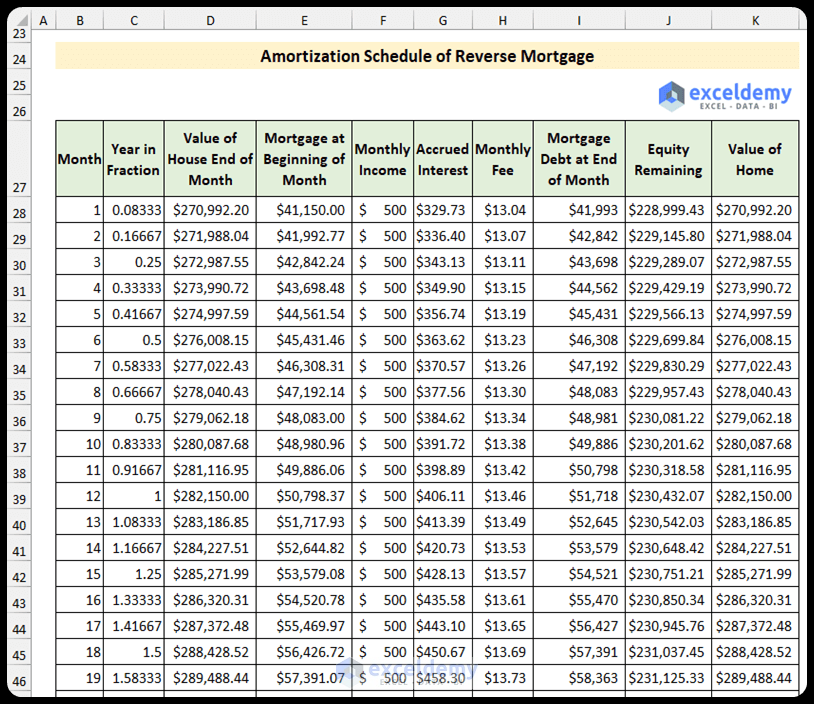
A reverse mortgage amortization calculator tracks the opposite of a traditional mortgage. Instead of paying down principal each month, the loan balance grows because unpaid interest compounds onto the existing balance. The borrower takes distributions, interest accrues on the full balance, and the total debt increases over time. That is the core mechanic. A standard reverse mortgage amortization calculator simply models this growth direction. The key variable most people miss is the expected rate, not the note rate. The expected rate is the FHA-required projection rate used for qualification and for building the amortization schedule. It is almost always lower than current market rates. That means the calculator output shows a slower balance growth than what may actually occur if market rates rise. When I ran a refinance analysis for a client last year who had taken a HELOC before converting to a HECM, their expected rate was 4.5% but the actual yield came in around 7.2%. I had to rebuild the schedule in my own spreadsheet using the note rate plus the actual margin to show the real exposure. The FHA calculator would have understated the projected balance by roughly $42,000 over ten years for their scenario.
Using a Reverse Mortgage Amortization Calculator Step by Step
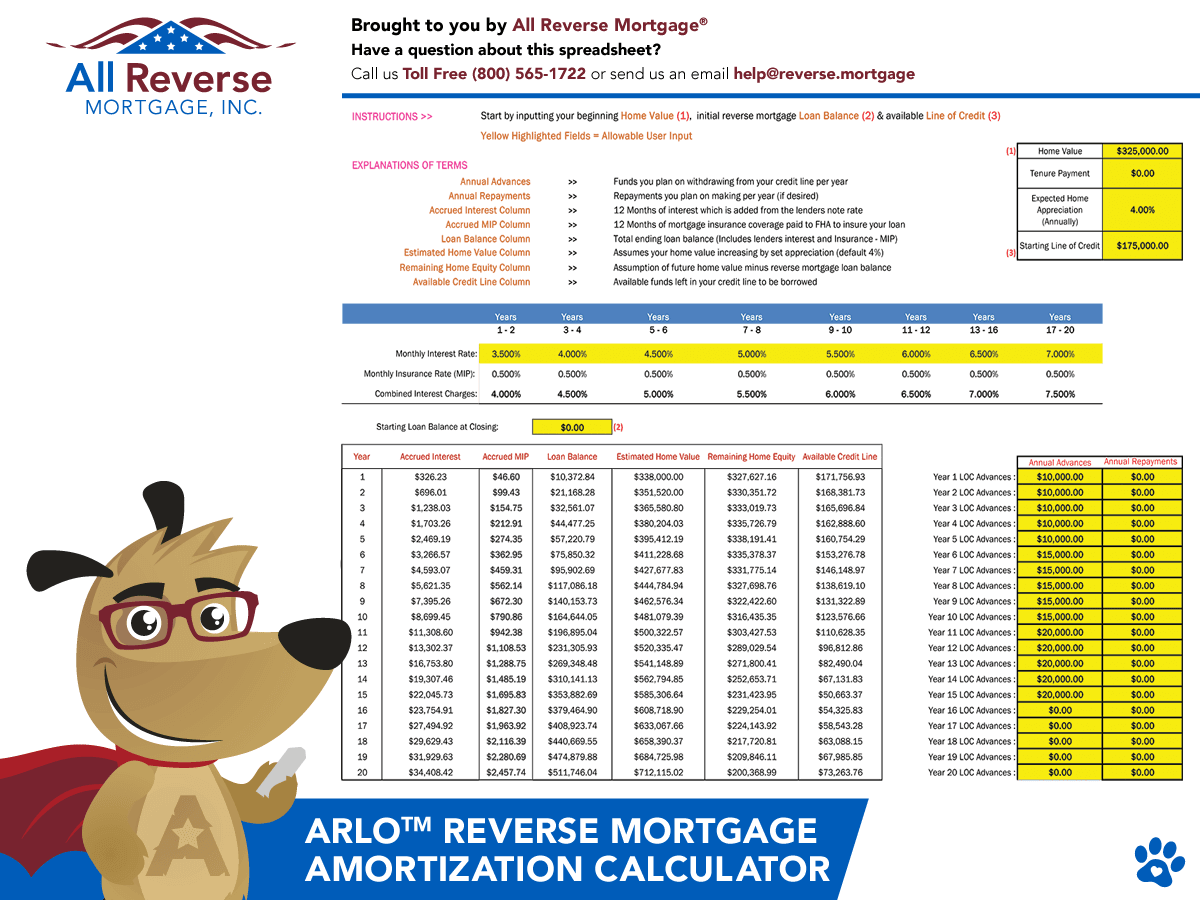
Here is the practical process I follow when building or running a reverse mortgage amortization schedule: Step 1: Gather the loan terms. You need the principal limit factor based on the youngest borrower's age and the home value, the current interest rate, the mortgage insurance premium (2.5% upfront and 0.5% annually for HECMs), and the closing cost estimate. The calculator will use these to determine the initial loan balance. Step 2: Input the payment structure. Most calculators assume monthly disbursements. If the borrower is receiving annual payments instead, switch that setting. Annual payment plans change the compounding frequency dramatically. A $300,000 line of credit with annual draws versus monthly draws can produce a balance difference of $8,000 to $12,000 over seven years depending on the interest rate environment.
Step 3: Run the schedule and check the early years. Reverse mortgage amortization is front-loaded in terms of interest accumulation because the balance starts small and compounds upward. The first three years typically account for the highest percentage of total interest accrual relative to the original principal. This is the period where most borrowers underestimate the speed of growth. Step 4: Stress test with a higher rate. Run the calculator at 2% above the current expected rate. If the balance still feels comfortable at that level, the original schedule is reasonable. If it blows past the property value threshold, the product selection or draw plan needs adjustment. One edge case I deal with regularly involves non-standard home types. A reverse mortgage amortization calculator will often throw an error or return misleading numbers when the property is a manufactured home built before 1976, a co-op, or a multi-unit property with non-owner occupancy. The FHA lending guidelines treat these differently, and the principal limit factors change. I learned this the hard way when a client brought in a 1972 mobile home. The online calculator I was using assumed a standard single-family residence and gave a principal limit that was $18,000 too high. I had to pull the HUD handbook tables manually and apply the correct adjustment factor for manufactured housing, which reduced the eligible amount by about 12%. After that correction, the amortization schedule showed the borrower would exhaust their line of credit four years earlier than the tool had suggested.
Get the Full Details
Common Mistakes That Break the Schedule
The biggest mistake I see is using a calculator that does not account for annual mortgage insurance premium accrual. The 0.5% annual MIP compounds monthly inside the loan balance. If the calculator ignores it, the output is artificially low. A second mistake is entering the home value instead of the appraised value at origination. If the home appreciate, that does not increase the available principal limit. The calculator should lock to the lower of the appraised value or the FHA lending limit at closing. Another hidden issue is property tax and insurance escrow. Some servicers add these to the loan balance each year if the borrower does not pay them separately. A basic amortization calculator will not include this unless you manually add it. I always build in a $2,000 to $4,000 annual escrow buffer depending on the county, because it shifts the balance growth curve enough to matter over a fifteen-year horizon.
When a Reverse Mortgage Amortization Calculator Falls Short
Standard calculators assume a fixed-interest product. If the borrower is looking at an adjustable-rate reverse mortgage, which most HECMs are, the calculator becomes a rough snapshot rather than a reliable projection. The ARM adjustment caps, the index margin, and the periodic and lifetime caps all change the trajectory after the first adjustment date. For adjustable scenarios, I recommend building a custom Excel model with year-by-year rate assumptions rather than relying on a web calculator. It takes about twenty minutes to set up and gives you a much more accurate picture of the eventual payoff balance. There is also the matter of refinancing mid-loan. If the borrower refinances to a larger HECM after five years, the old amortization schedule is irrelevant. You need a fresh calculation from the new principal limit, new interest rate, and remaining term. The calculator output from the original loan does not carry over in any meaningful way. The bottom line is that a reverse mortgage amortization calculator is a useful starting point, not a final answer. It works best for HECM fixed-rate products with standard draw schedules on single-family owner-occupied homes. Outside of that narrow band, you need to adjust the inputs manually or build a custom model. The math itself is straightforward, but the variables that shift the output are numerous and easy to overlook if you are not used to tracking them.