Working with Reverse Mortgage Amortization Schedules
The calculation process is straightforward once you understand the mechanics. You take the initial loan amount, apply the interest rate monthly, and add accrued interest to the balance each period. Unlike traditional mortgages where the balance shrinks, reverse mortgages grow. I built a spreadsheet tool that automates this in about 10 minutes per file, though the actual review of the results takes longer because of compliance requirements. Key components you need to track: The principal limit factor from HUD tables, the expected interest rate, and the borrower's age. These three variables determine your starting point. From there, it's just compound interest applied monthly until repayment triggers.
Reverse Mortgage Amortization Schedule Breakdown
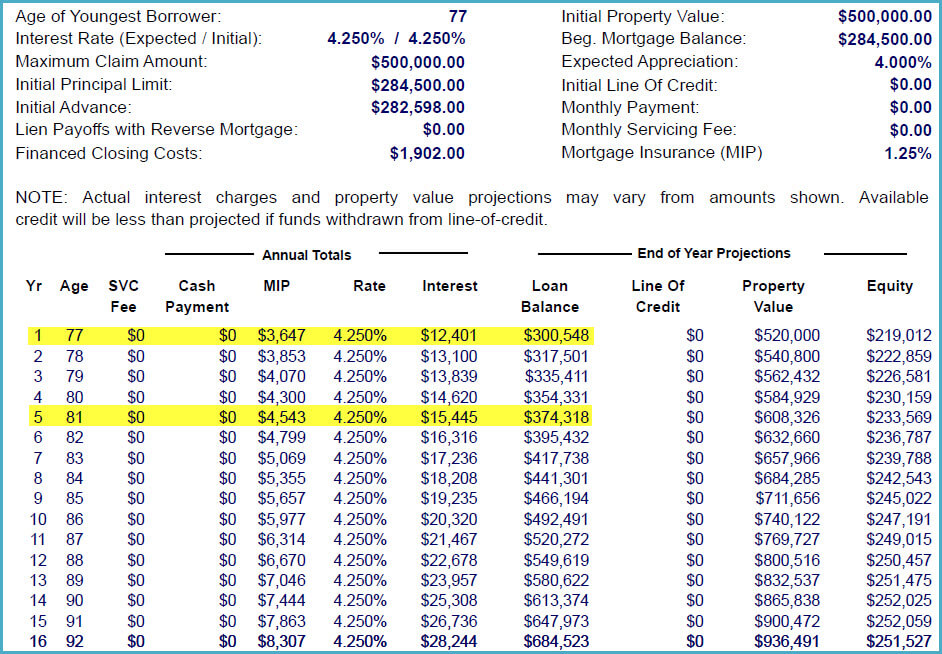
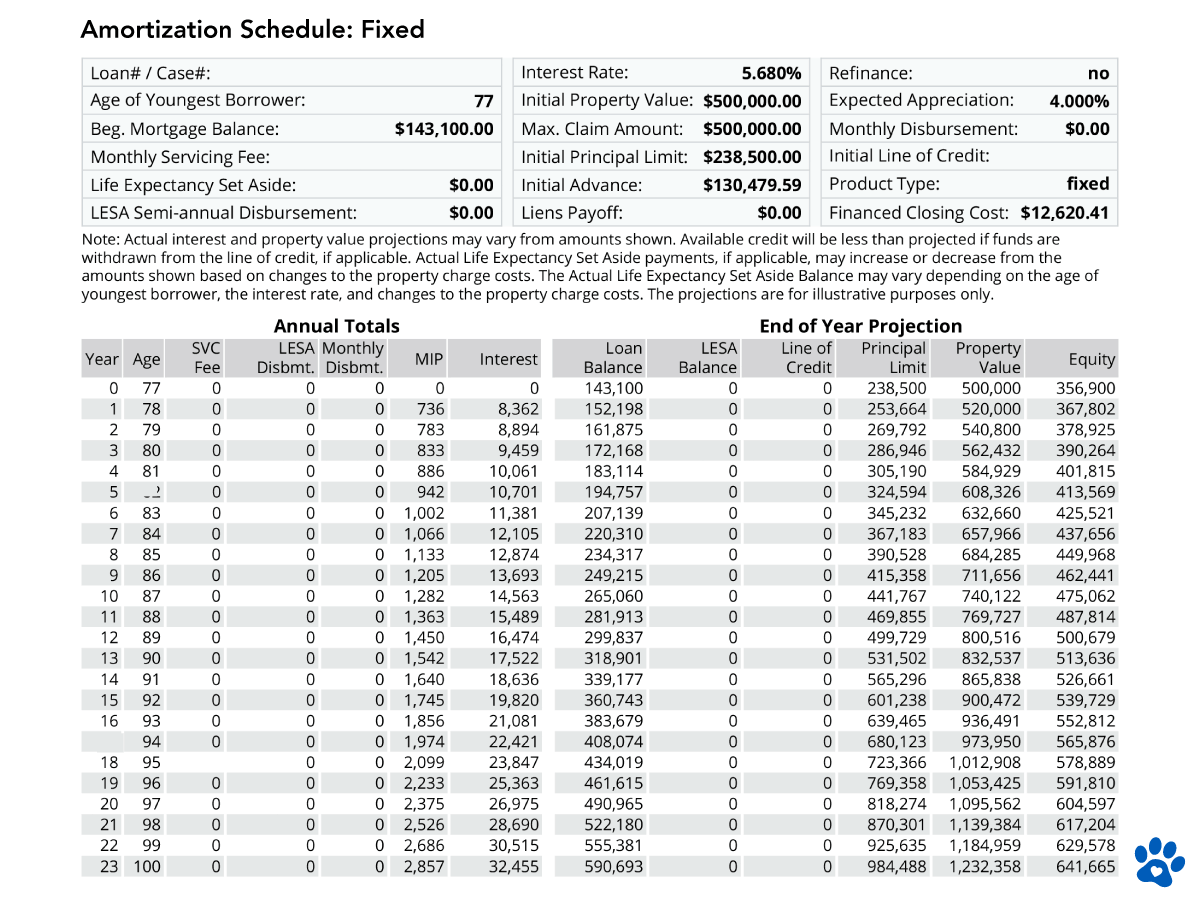
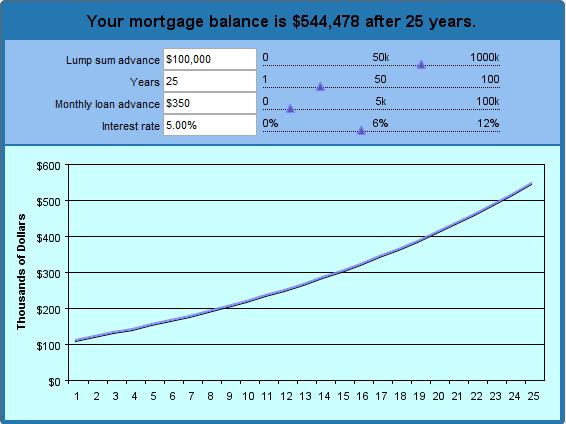
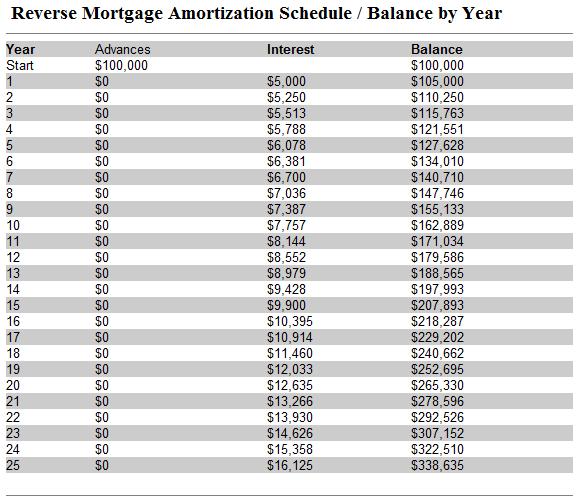
Here's what the schedule actually shows. Each row represents one month. The columns break down the opening balance, interest accrued that month, total disbursements received, and closing balance. That's it. Nothing fancy. Most people expect dramatic differences in payment amounts, but the growth is fairly linear in the early years because the balance is still relatively small. I ran into a specific problem last year that took me three hours to solve. A client wanted to refinance their HECM loan, and the new lender provided an amortization schedule that didn't match our projections by about $12,000 after five years. We traced it to a compounding difference. Their system used daily compounding while we used monthly. Daily compounding adds roughly 0.15% more interest per year on a $400,000 loan. The workaround was switching to daily calculations in our model and building a reconciliation report for the underwriter. Takes about 20 minutes now that I have the formula locked in. The math itself uses this formula: Ending Balance = Opening Balance + (Opening Balance × Monthly Rate) + Disbursements - Payments Made. Since reverse mortgages typically have no required payments, it simplifies to just adding monthly interest and any withdrawals. Very mechanical once you have it set up.
There are complications you should know about. The first is the mortgage insurance premium, which compounds into the loan balance and affects calculations differently depending on whether it's an upfront or monthly premium structure. I recommend tracking these separately in your spreadsheet so you can see their impact on the true cost. The second is the lending limit. HECM loans have maximums that change yearly. If your schedule goes beyond the limit, you'll need a jumbo component that carries different terms. This happens frequently with higher-value properties in coastal markets. Another counter-intuitive point: the amortization schedule doesn't tell you when the loan is due. There's no maturity date in the traditional sense. Repayment triggers are borrower death, sale, or permanent move-out. The schedule shows projection, not obligation. Many borrowers misunderstand this and think they're making progress toward payoff when they're really just accumulating debt. I always include a note on every schedule I produce clarifying this. The tool I use is a modified Excel workbook with lookup tables for the HUD principal limit factors. For a standard HECM refinance analysis, a complete schedule takes about 45 minutes to generate and verify. The bottleneck isn't the calculation itself—it's reconciling the numbers with the loan estimate documents and ensuring the interest rate assumption matches what the borrower locked. If the rate lock expires during processing, you may need to regenerate the entire schedule.
Get the Full Details
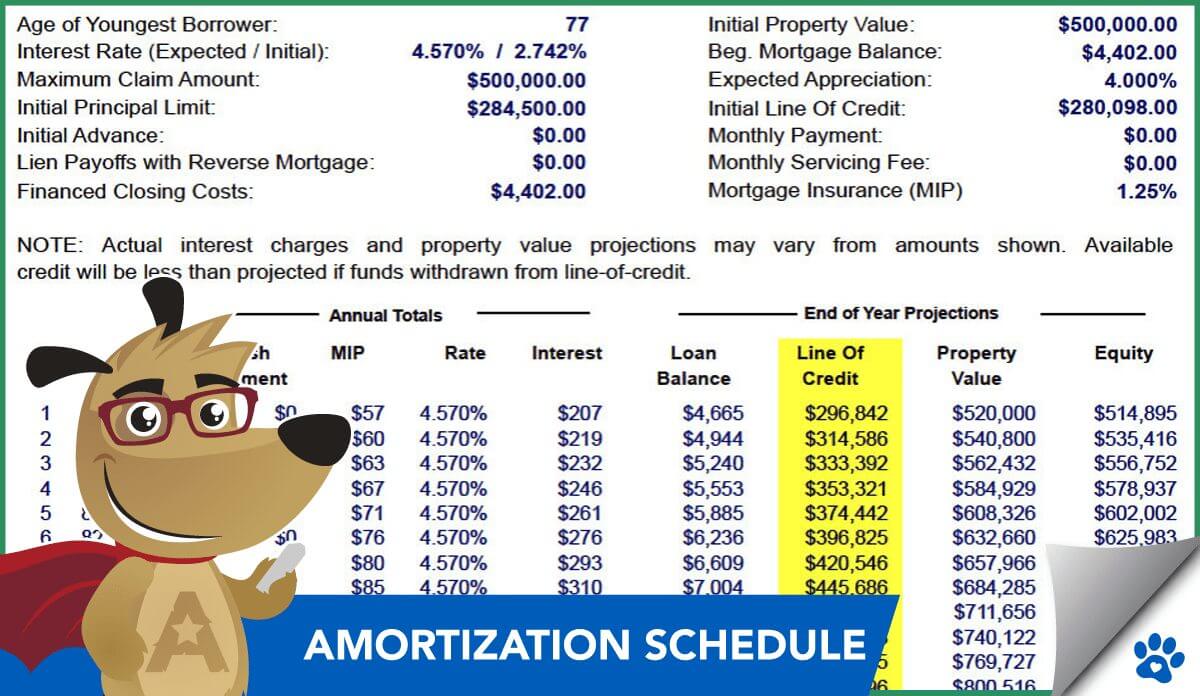
Some situations break the standard model entirely. Home equity lines of credit (HELOC) structures attached to reverse mortgages don't follow the same compounding pattern. The available credit portion doesn't accrue interest until drawn, but your schedule needs to account for both the committed and uncommitted portions separately. This tripped me up on a complex case involving a combined reverse mortgage and HELOC product. The workaround was creating two parallel schedules and merging them at the report stage, which adds about 15 minutes to the workflow but produces accurate results. If you're doing these manually, expect to spend 2-3 hours on your first schedule and about 45 minutes on subsequent ones once you have the template working. The learning curve is steeper than traditional mortgage amortization because of the compounding insurance premiums and the lack of fixed repayment terms. Most people underestimate the time required for proper verification.