How to Get a Reverse Mortgage Estimate That Actually Matters
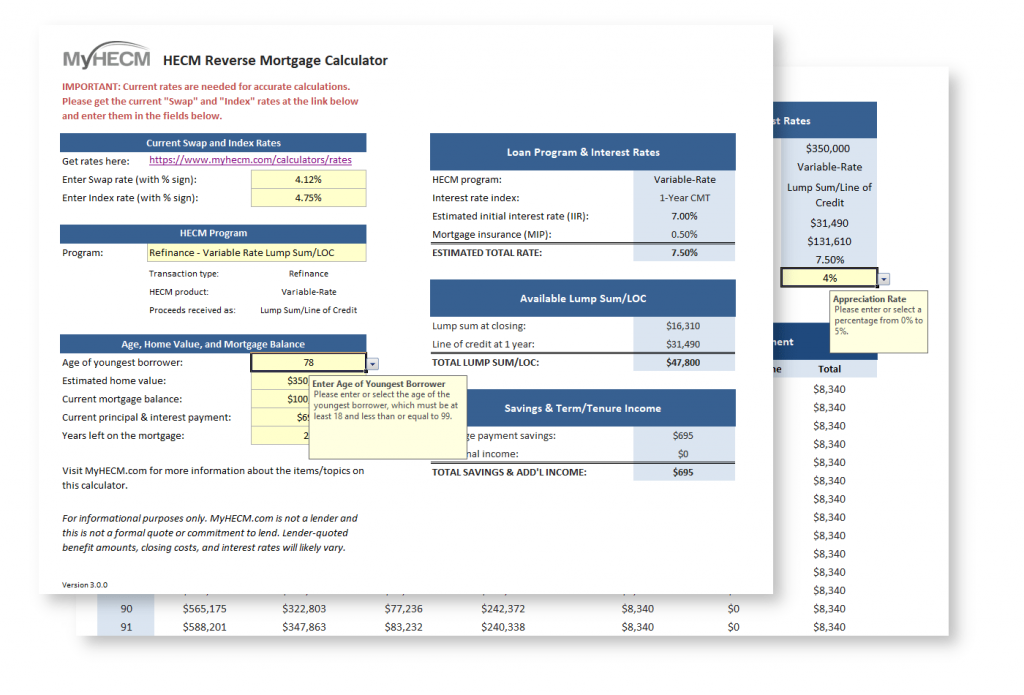
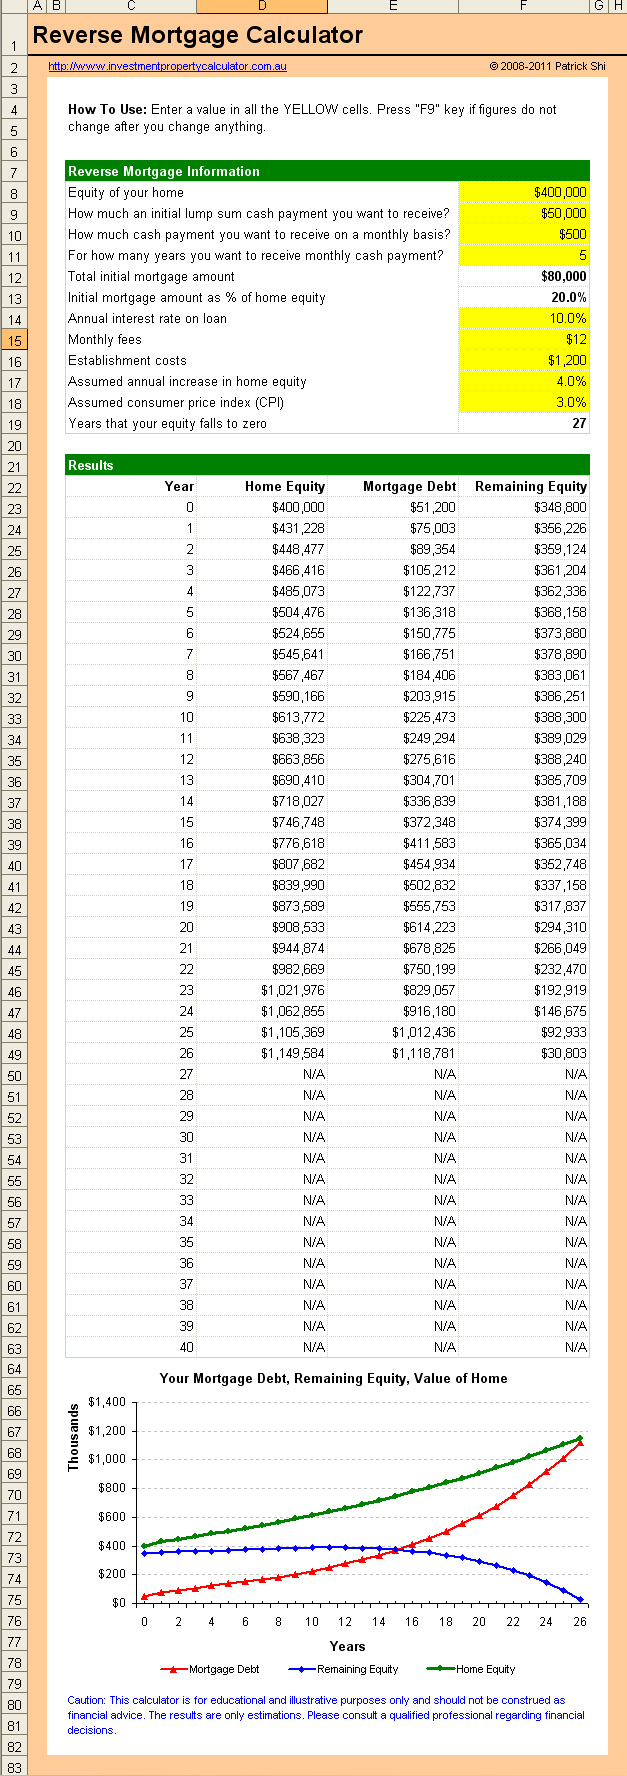
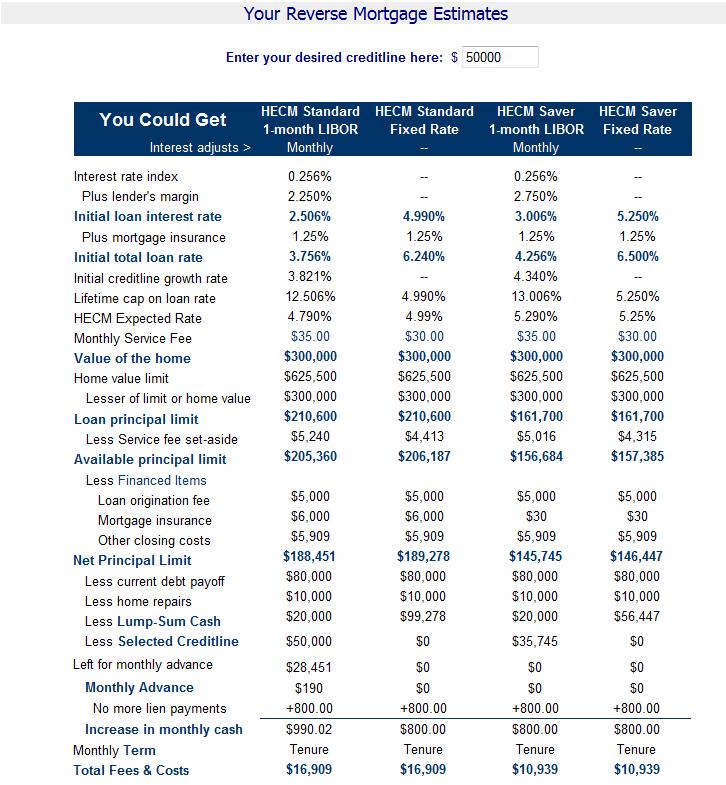
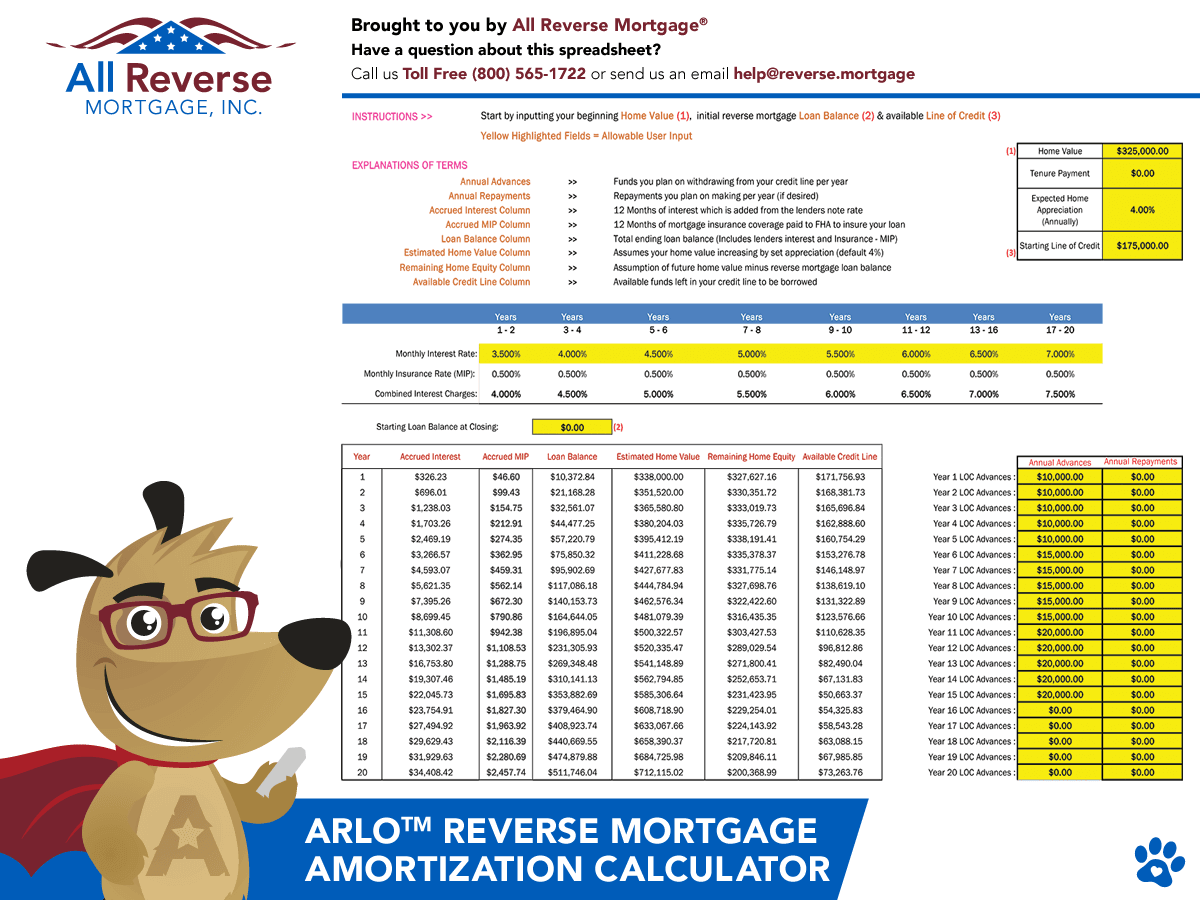
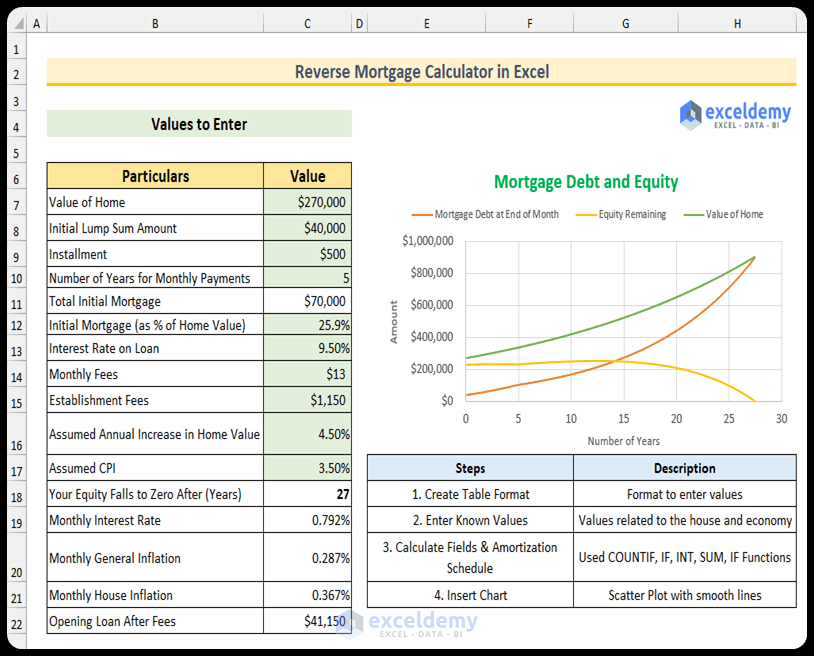
I spent three years doing reverse mortgage calculations for clients who couldn't tell the difference between a HECM estimate and a real closing disclosure. The first thing you need to understand is that a reverse mortgage estimate is not a binding offer. It is a projection, and projections can swing $40,000 depending on the interest rate you lock in and the age of the youngest borrower listed on the deed. A proper reverse mortgage estimate breaks down into four components: the appraised value of your home, the principal limit based on age and current interest rates, the closing costs that get rolled into the loan, and the net proceeds you will receive at settlement. Most people focus on the last number and ignore the first three. That is how you end up with $12,000 less cash than you expected because someone quoted you a rate from six months ago. The math itself is straightforward but the variables are not. The principal limit factor comes from a table published by HUD every year. A 75-year-old with a primary residence qualifies for a different percentage than a 62-year-old with the same property value. If you refinance or remortgage into a reverse mortgage, the calculation resets. I had a client in Florida who refinanced at age 71, waited four years, and then refinanced again thinking she would get more equity. She actually got $18,000 less because the principal limit factor dropped when the interest rate climbed from 4.5% to 6.8%.
Where People Mess Up the Estimate
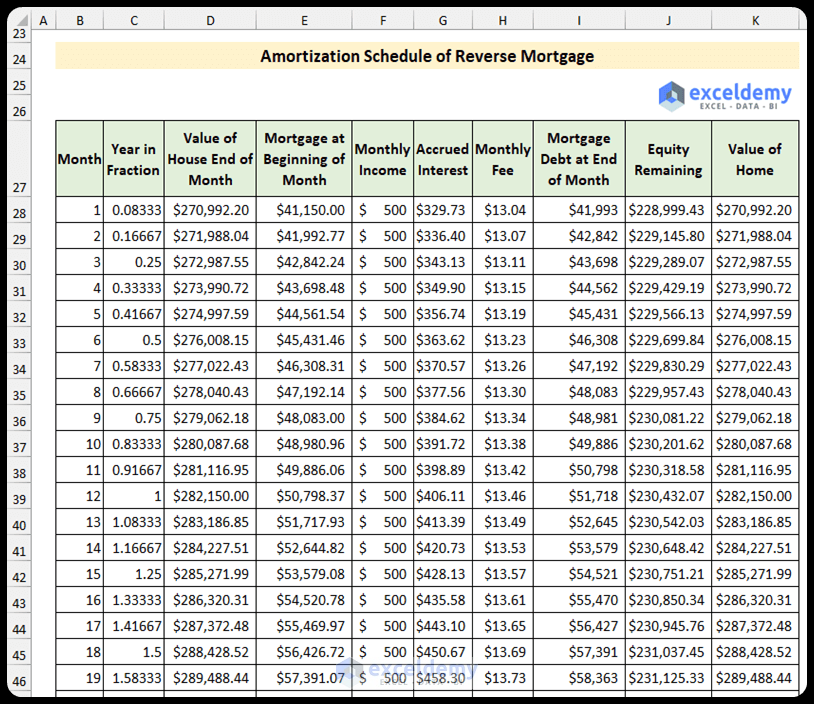
The biggest mistake I see is using an outdated appraisal. Reverse mortgage appraisals have to meet FHA guidelines, and not every appraiser knows what that means. A standard residential appraisal might value your home at $450,000, but the FHA appraisal could come in at $415,000 if the appraiser spots deferred maintenance or comparable sales issues. I learned this the hard way in 2019 when my client's roof was 22 years old and the appraiser flagged it as a repair requirement before underwriting. That $25,000 repair had to be completed before closing, and it ate into her net proceeds by almost that much. Another issue is ignoring the servicing fees. Your monthly service charge accumulates over time and reduces the amount available to you. The standard fee is around $60 per month, but some lenders charge more. Over ten years, that is $7,200 in fees that never gets repaid until the loan comes due. You do not have to pay it monthly, but it still matters.
How to Get an Accurate Reverse Mortgage Estimate
Start by pulling your most recent property tax assessment. Use that number as your starting point, not the Zillow estimate. Then call three lenders who specialize in HECM loans and ask for a Principal Limit Factor quote based on your exact age and the property type. Write down the interest rate they quote and the date. Ask them to run the calculation again using the current rate, not the rate from their marketing brochure. Next, get an FHA appraisal if you are within 12 months of applying. This step alone usually saves two to three weeks of closing delays. The cost runs about $500 to $750, and it protects you from surprises. I always tell my clients to budget $3,000 for closing costs on top of the mortgage insurance premium. The upfront MIP is 2% of the home value, and it gets added to your loan balance immediately. Finally, read the Good Faith Estimate form line by line. Most people skip to the signature page. The lender must provide this document within three business days of your application. If they do not, walk away. I had a borrower in California who signed with a lender who rushed the paperwork. The closing costs were $8,000 higher than the estimate, and she was stuck because she had already moved out of state.
Get the Full Details
When an Estimate Is Wrong
Sometimes the estimate looks good but the closing disclosure tells a different story. This happens when the lender uses a higher interest rate assumption than they actually offer, or when they exclude certain fees to make the numbers look better. Always compare the Loan Estimate and the Closing Disclosure side by side. Any difference larger than $100 in closing costs requires an explanation. If the lender cannot provide one, find another lender. The biggest limitation of a reverse mortgage estimate is that it does not account for property taxes or homeowners insurance falling behind. These payments are due monthly, and if you miss them, the loan can go into default. I saw a case in Arizona where the borrower stopped paying property taxes because she thought the reverse mortgage covered everything. The county put a lien on the home, and the lender called the entire loan due within 30 days. She lost $90,000 in equity because she misunderstood the terms. Another pitfall is assuming you can spend all the proceeds at once. The first disbursement is usually limited to 60% of the principal limit in the first year. If you need more cash, you have to wait or request a line of credit. This restriction exists to protect borrowers from exhausting their equity too quickly. It also means your estimate needs to account for the spending timeline. A client in Texas wanted $50,000 immediately for a kitchen renovation. The estimate showed $85,000 in net proceeds, but the first-year limit cut that to $51,000. She had to reconsider her plans.
Alternatives When a Reverse Mortgage Estimate Falls Short
If the estimate does not give you enough equity, consider a home equity line of credit instead. The borrowing limit is usually lower, but the costs are cheaper and you control when you take the money. A HELOC typically charges $500 to $1,000 in closing costs versus $6,000 to $10,000 for a reverse mortgage. The tradeoff is that you have to make monthly payments on the HELOC, while the reverse mortgage does not require any payment until you sell or move out. For people who qualify for both, I usually recommend running the numbers for each option and comparing the total cost over five years. The reverse mortgage wins if you plan to stay in the home long-term and need predictable cash flow. The HELOC wins if you want flexibility and lower upfront costs. Neither option is perfect, and the right choice depends entirely on your situation.
Reading the Fine Print
The final step is reviewing the loan documents before you sign. Pay attention to the prepayment penalty clause, the due-on-sale provision, and the occupancy requirement. If you rent out the property for more than 12 consecutive months, the lender can demand full repayment. This rule exists to prevent investors from using reverse mortgages as profit tools. It also means you need to understand what happens if your circumstances change. I always tell my clients to keep a copy of the estimate and the closing disclosure in a safe place. You may need them later when refinancing or selling the home. The estimate is valid for 90 days from the date of issuance, but the closing disclosure is the final word. Any discrepancy between the two should be resolved before you sign. If the lender refuses to explain it, walk away and find someone else. The math behind reverse mortgages is not complicated, but the details matter. A $10,000 difference in closing costs can change the outcome significantly. Use a calculator, get multiple quotes, and verify every number before you commit. The process usually takes 30 to 45 days from application to closing, and rushing it often leads to mistakes. Take your time, read every page, and ask questions until you understand exactly what you are agreeing to.